


What’s Going On With CenterPoint Energy (CNP)?
DOE award and dividend move put CenterPoint Energy in focus
CenterPoint Energy (CNP) just picked up a $50 million U.S. Department of Energy award for advanced substation upgrades, while also affirming a regular quarterly dividend of $0.24 per share.
CenterPoint Energy’s recent DOE award and dividend affirmation come as the share price trades at US$37.79, with a 90 day share price return down 15.29%. This is in contrast to the three year total shareholder return of 51.82% and the five year total shareholder return of 67.87%, which point to a stronger longer run record.
Spot similar grid and infrastructure plays moving on fresh catalysts by scanning our hand picked 40 power grid technology and infrastructure stocks.CenterPoint Energy now trades below the average analyst target, even after the recent slide. The next step is figuring out whether that discount reflects an opportunity or justified caution based on the fundamentals.
Most Popular Narrative: 16.7% Undervalued
CenterPoint Energy’s most followed narrative pegs fair value at $45.35, above the last close at $37.79, which frames the current pullback as a potential valuation gap rather than just a weak chart.
CenterPoint Energy expects to grow non-GAAP EPS at the mid to high end of a 7% to 9% range annually through 2028 and through 2035. This ties long dated earnings growth directly to its US$66.7b capital investment plan and large-load expansion, and therefore to future revenue and earnings.
See why 5 investors see CenterPoint Energy as 17% undervalued.
Result: Fair Value of $45.35 (UNDERVALUED)
Still, the narrative around CenterPoint Energy could be hit if its US$66.7b spending plan runs into regulatory pushback, or if funding through new debt and equity dilutes returns.
Find out about the key risks to this CenterPoint Energy narrative.
Another view on CenterPoint Energy’s valuation
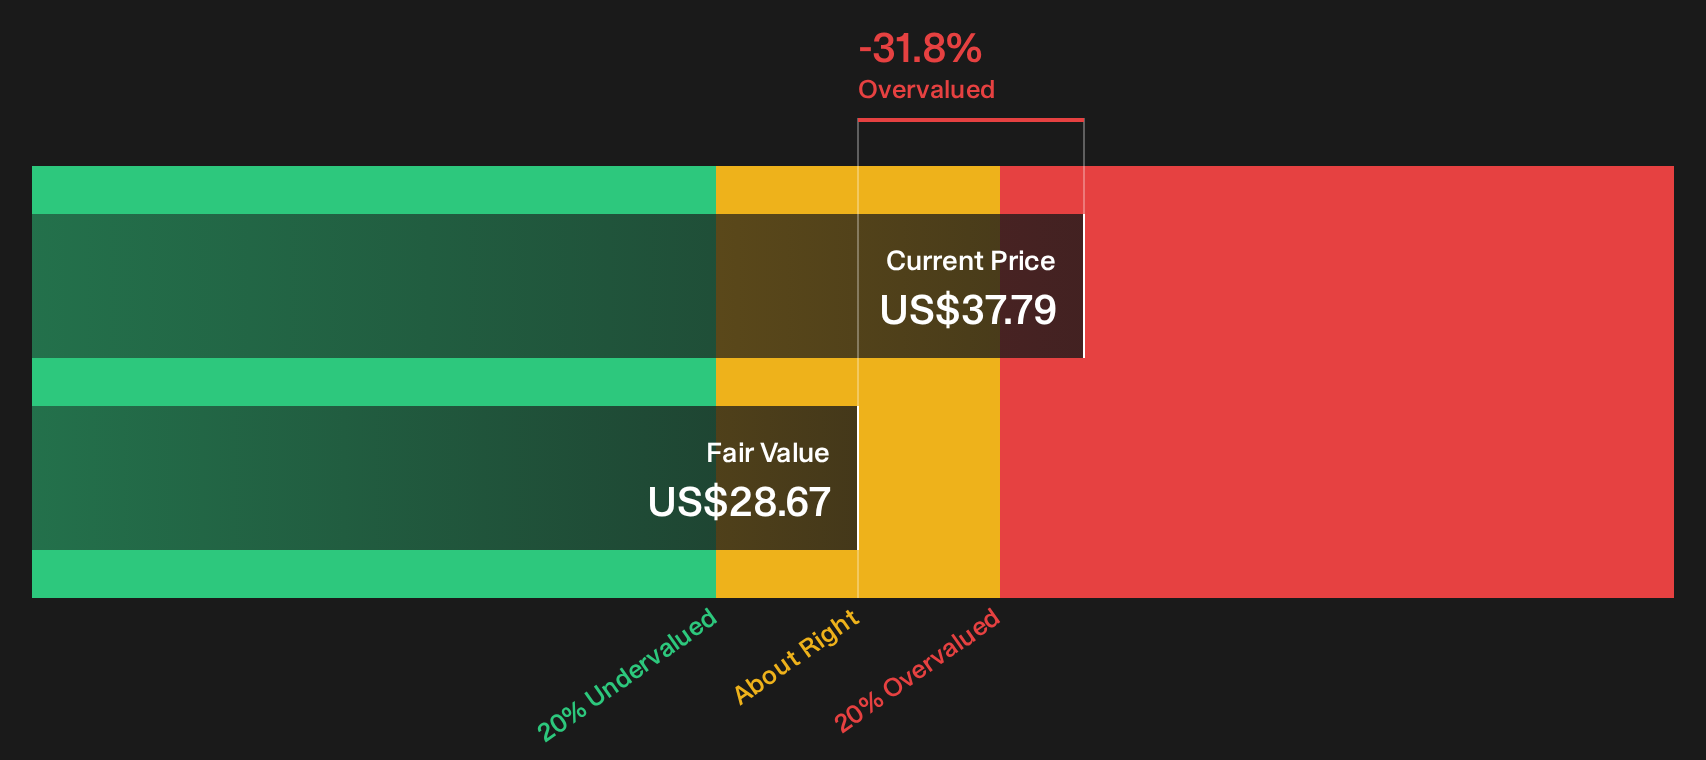
The earlier narrative frames CenterPoint Energy as about 16.7% undervalued based on future earnings and a premium P/E. The SWS DCF model points in the opposite direction. On that cash flow lens, CNP at $37.79 trades above an estimated value of $28.67, which leans toward overvaluation. That kind of split leaves a simple question: Which risk are you more comfortable with, paying up for growth or waiting for price to meet cash flows?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around CenterPoint Energy can make the story feel messy, which is exactly why you should review the data now and pressure test your own thesis using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CenterPoint Energy?
If CenterPoint Energy is on your radar, do not stop there. Broadening your watchlist with fresh ideas can help you spot opportunities others overlook.
- Target stability first and check companies with strong financial footing through a list of solid balance sheet and fundamentals (26 results) that highlights robust balance sheets and fundamentals.
- Hunt for value by scanning a 31 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Prioritize resilience and peace of mind by reviewing a 31 resilient stocks with low risk scores focused on companies with lower risk scores and steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com