


Eton Pharmaceuticals (ETON) Moved, What Is Behind The Fresh Attention?
Eton Pharmaceuticals and the IMPAVIDO launch event
Eton Pharmaceuticals (ETON) has just launched IMPAVIDO capsules for several forms of leishmaniasis in adults and adolescents, giving investors a fresh product event to factor into the rare-disease story.
The IMPAVIDO launch lands after a sharp rerating in Eton Pharmaceuticals, with the share price up 47.63% over 90 days but down 10.65% over 30 days, and a very large 3-year total shareholder return of 12.7x. This points to momentum that has cooled in the short term.
Scan rare-disease peers that are moving on product catalysts such as IMPAVIDO by reviewing the hand-picked 19 high quality undiscovered gems positioned around similar specialist treatment themes.
After a 12.7x three year run and a recent pullback, Eton Pharmaceuticals now sits in a grey zone between momentum and patience. Does committing capital here make more sense than waiting for a deeper reset in valuation?
Most Popular Narrative: 22% Undervalued
Eton Pharmaceuticals closed at $55.36, against a widely followed narrative fair value of $71.00. This puts the focus firmly on whether execution can keep matching those expectations.
Eton's investments in digital patient support platforms, targeted education campaigns, and specialist distribution (e.g., Eton Cares) are removing historical barriers to access and supporting higher therapy adoption and retention. This is driving increased penetration in niche markets and supporting recurring revenues.
Operational leverage is expected to improve earnings and net margins as recent SG&A and marketing investments are now largely complete, while revenues continue to grow from new and existing products. This indicates that profitability may scale more rapidly than expenses in coming quarters.
See why 15 investors see Eton Pharmaceuticals as 22% undervalued.
Result: Fair Value of $71 (UNDERVALUED)
Still, the Eton Pharmaceuticals story can be knocked off course if key rare disease products face tougher pricing pressure or if planned regulatory submissions are delayed.
Find out about the key risks to this Eton Pharmaceuticals narrative.
Another View on Eton Pharmaceuticals’ Valuation
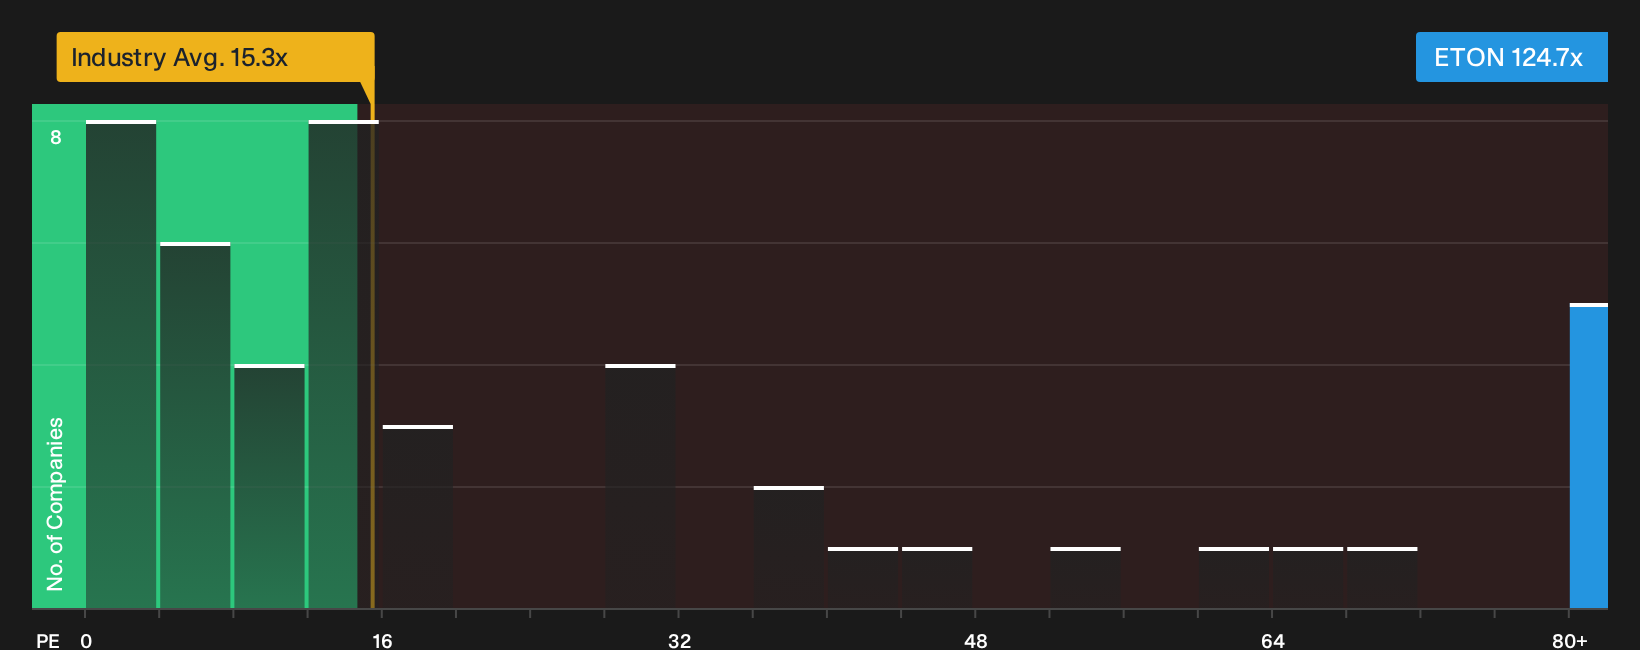
On a simple earnings yardstick, Eton Pharmaceuticals looks expensive. The current P/E of 124.7x sits far above the US Pharmaceuticals average of 15.3x and even the fair ratio estimate of 30.9x. That gap suggests meaningful valuation risk if sentiment cools or earnings forecasts are revised.
See what the numbers say about this price and find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Eton Pharmaceuticals story so far, right. If the mix of concern and optimism feels familiar, take a closer look for yourself and weigh the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Eton Pharmaceuticals?
If Eton Pharmaceuticals has your attention, do not stop there. Broader opportunity often sits in sectors and themes you have not checked yet.
- Target potential mispricings by scanning companies that screen as quality but overlooked through the 31 high quality undervalued stocks.
- Prioritise resilience by reviewing a curated 31 resilient stocks with low risk scores that emphasises financial strength and steadier profiles.
- Hunt for early-stage potential by checking a focused 9 elite penny stocks with strong financials that filters for stronger financial characteristics in lower-priced stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com