


CoreCivic (CXW) Could Be 20% Below Fair Value Following CEO Change
CoreCivic (CXW) is back in focus after a rapid reshuffle at the top, with Lucibeth N. Mayberry stepping in as both President and CEO following Patrick D. Swindle’s health driven resignation.
Recent trading suggests investors are reassessing CoreCivic in real time. The stock has a 1-day share price return of 2.89% and a 7-day move of 4.05% around the leadership reshuffle. A 75.76% year to date share price return and a 5-year total shareholder return of 255.64% point to strong momentum that markets are now weighing against the risks and opportunities of a new CEO at the helm.
Broaden your watchlist by comparing CoreCivic’s leadership driven momentum with other hand picked operators in corrections, detention, and related services through our 31 resilient stocks with low risk scores
CoreCivic has already moved sharply on the leadership change, so the real call now is whether to accept today’s price or wait for a cleaner entry as the valuation picture comes into focus next.
Most Popular Narrative: 20% Undervalued
Against CoreCivic’s last close of $33.43, the most widely followed narrative points to a fair value of $41.80, which frames the leadership change against a valuation gap that investors now have to judge for themselves.
The unprecedented increase in mandatory government funding for federal detention and border security (notably, $75 billion for ICE and multi-year appropriations through 2029) is catalyzing rapid contracting activity, reactivation of idle facilities, and will significantly boost CoreCivic's recurring revenue and occupancy rates in future quarters.
Pressing demand for secure and reliable detention capacity due to record-high ICE populations and anticipated increases in U.S. Marshals Service detainees is driving new and expanded contracts, this will lift utilization rates at CoreCivic's facilities, with high incremental margins as idle beds are filled.
See why 15 investors see CoreCivic as 20% undervalued.
Result: Fair Value of $41.80 (UNDERVALUED)
Still, the narrative around CoreCivic can break if government policy shifts away from detention capacity, or if key ICE and U.S. Marshals contracts change materially.
Find out about the key risks to this CoreCivic narrative.
Another View on CoreCivic’s Valuation
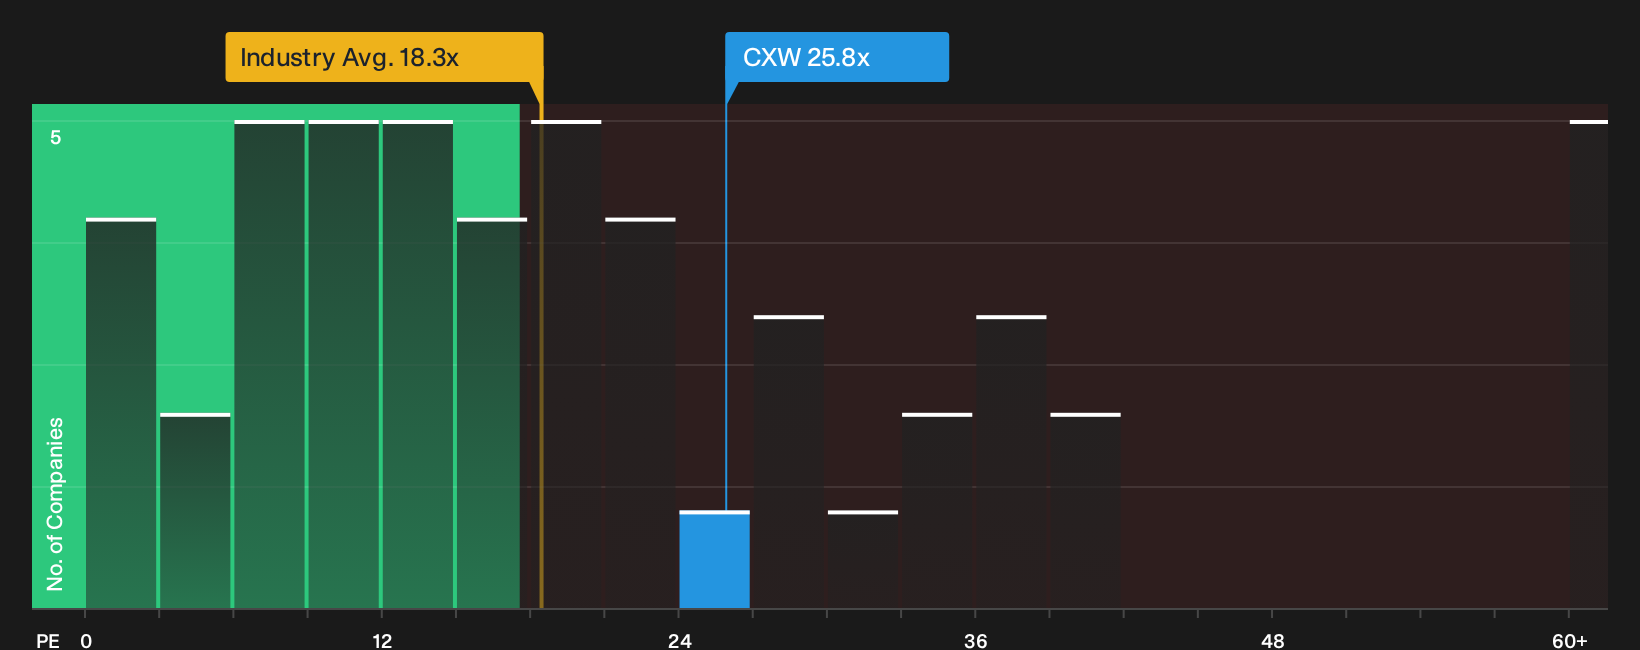
That 20% undervalued narrative looks very different when CoreCivic is viewed through its P/E. The shares trade on 25.8x earnings, compared with a 7.8x fair ratio estimate, 18.4x for peers, and 18.5x for the wider Commercial Services group.
This gap points to clear valuation risk if expectations reset toward that lower fair ratio. The key question is whether the current premium reflects justified conviction or crowded optimism.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in CoreCivic’s story so far. If you want to move quickly, skip the headline narratives and weigh both sides of the data yourself, including the 2 key rewards and 3 important warning signs.
Looking for more CoreCivic sized ideas?
If CoreCivic has you thinking harder about valuation and momentum, use the Simply Wall Street Screener to surface fresh opportunities that fit your own criteria.
- Target resilient potential by scanning for companies with strong fundamentals and sturdy balance sheets through our list of solid balance sheet and fundamentals (26 results).
- Hunt for mispriced quality and see which candidates screen well on cash flows and valuation using the 31 high quality undervalued stocks.
- Build a watchlist of future candidates and track early stage opportunities that pass strict financial filters via the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com