


What Is Drawing Fresh Attention To Paylocity Holding (PCTY)?
AI talent tools land on the Paylocity Marketplace
Paylocity Holding (PCTY) is back in focus after HireQuotient’s AI sourcing agent, EasySource, was officially added to the Paylocity Marketplace less than a month after its launch.
The tool is one of only eight AI offerings available there, with most others centered on background checks. That keeps attention on how Paylocity is curating third party software around its human capital management platform.
Against that backdrop, Paylocity Holding’s share price has been choppy, slipping 6.55% over the past 30 days but climbing 25.52% over the last 90 days. Over the same period, the 1 year total shareholder return has declined 7.18%, and the 5 year total shareholder return is down 47.56%.
Scan beyond Paylocity Holding and see which other HR and AI powered platforms are already catching market attention in the 37 profitable AI stocks that aren't just burning cash.
After a sharp 90 day rebound but a 5 year return that is still deeply in the red, Paylocity Holding sits at an awkward middle ground. Is the real upside still ahead, or was this bounce the main event?
Most Popular Narrative: 16% Undervalued
On the widely followed view, Paylocity Holding’s fair value sits at $172.00 compared with the last close of $144.47. This puts the current share price at a clear discount and turns the spotlight onto how durable the business model really is.
Expansion of Paylocity Holding’s unified HR, finance and IT platform with embedded AI agents such as Ignite AI and the AI assistant, along with planned premium SKUs tied to tools like Grayscale and Aidora, is expected to convert rising AI usage into higher recurring revenue and average revenue per client over time, which may support earnings growth.
See why 12 investors see Paylocity Holding as 16% undervalued.
Result: Fair Value of $172.00 (UNDERVALUED)
Still, the Paylocity Holding narrative can be knocked off course if revenue growth slows toward guidance and AI and premium modules fail to gain expected traction.
Find out about the key risks to this Paylocity Holding narrative.
Another View: Paylocity Holding Through The P/E Lens
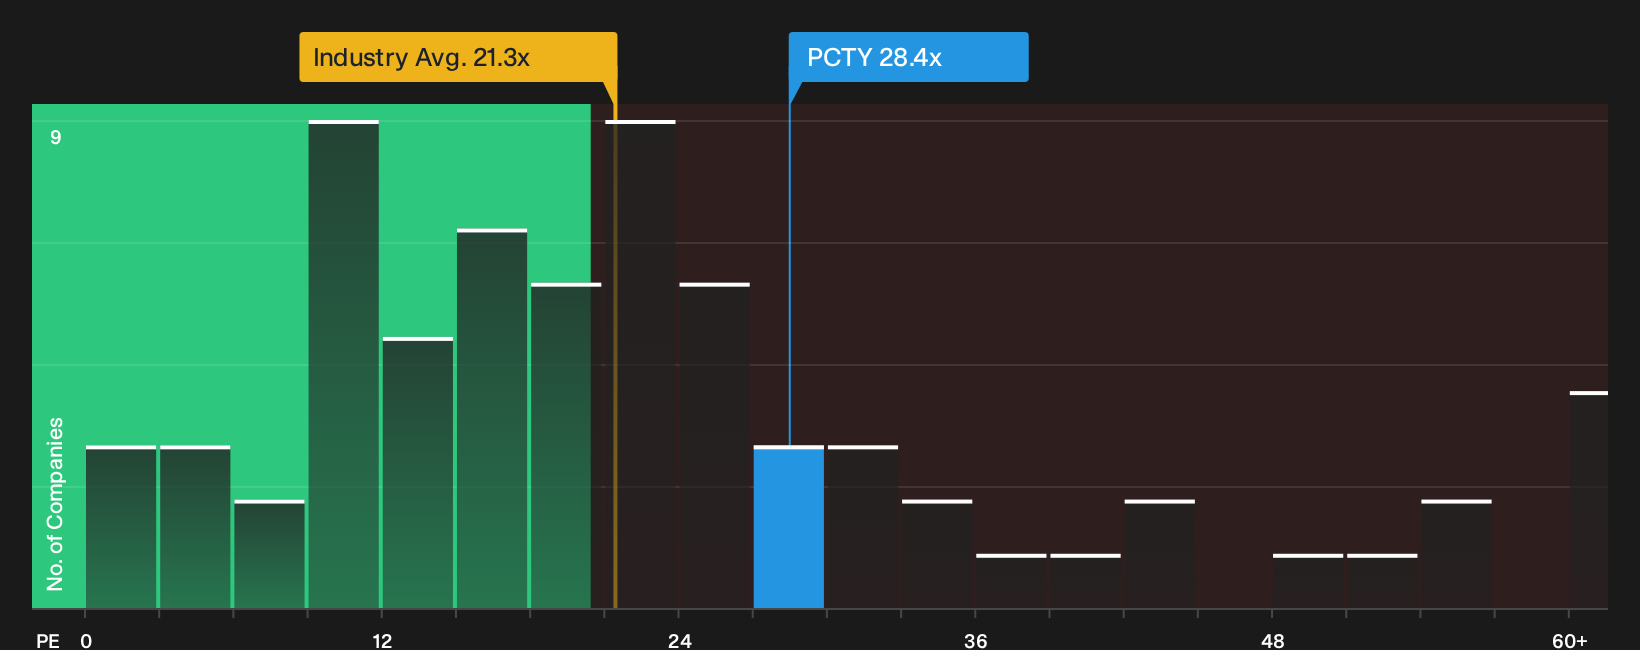
The cash flow story on Paylocity Holding points one way, yet the earnings multiple points another. The shares trade on a P/E of 28.4x, which is well above both the US Professional Services average of 21.7x and an estimated fair ratio of 20.2x. That premium suggests investors are already paying up, so the question is whether the current discount to fair value is a genuine opening or simply less downside rather than clear upside.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The Paylocity Holding story has included mixed developments so far. If you want to move quickly and decide for yourself, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Paylocity Holding?
If Paylocity Holding has your attention, do not stop there. The wider market is full of potential opportunities that could better match your goals and risk comfort.
- Target resilience first by reviewing companies in the 31 resilient stocks with low risk scores that aim to keep drawdowns in check when conditions turn rough.
- Hunt for quality at a discount through the 19 high quality undiscovered gems that pair solid fundamentals with limited current attention.
- Prioritize financial strength by scanning the list of solid balance sheet and fundamentals (26 results) so you do not miss businesses with healthier cushions than Paylocity Holding.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com