


Hyatt Hotels (H) Could Be 19% Undervalued After Portfolio Growth Update
Hyatt Hotels (H) is back in focus after announcing a fresh wave of Essentials Portfolio openings across the United States, alongside appointing Amar Lalvani as its first Chief Creative Officer on September 30, 2026.
Investors have watched Hyatt Hotels give back some recent gains, with the share price down about 17% over the past 90 days and 4% year to date. However, the 1-year total shareholder return of around 8% and 5-year total shareholder return of roughly 93% still point to a stock where long-term momentum has remained stronger than the latest pullback suggests.
Spot similar hotel and travel stocks that could be setting up for the next leg of their story by scanning our hand picked 19 high quality undiscovered gems.Hyatt Hotels appears to be a solid operator rolling out new brands and leadership changes while the share price has stepped back. The key question is whether that combination now translates into a fair value at about $158.90.
Most Popular Narrative: 19% Undervalued
On the latest narrative workup, Hyatt Hotels screens with a fair value of about $196.83 against a last close of $158.90, which puts the current price at a steep discount if those assumptions hold.
The shift toward an asset-light, fee driven model, supported by 9% to 11% expected gross fee growth in 2026 and at least 50% conversion of adjusted EBITDA to free cash flow, indicates a mix shift toward higher margin fee streams that can improve cash generation and earnings quality.
See why 6 investors see Hyatt Hotels as 19% undervalued.
Result: Fair Value of $196.83 (UNDERVALUED)
Still, the Hyatt Hotels story can change quickly if weakness in Middle East fees deepens or Mexican all inclusive RevPAR pressure persists longer than analysts expect.
Find out about the key risks to this Hyatt Hotels narrative.
Another View on Hyatt Hotels Valuation
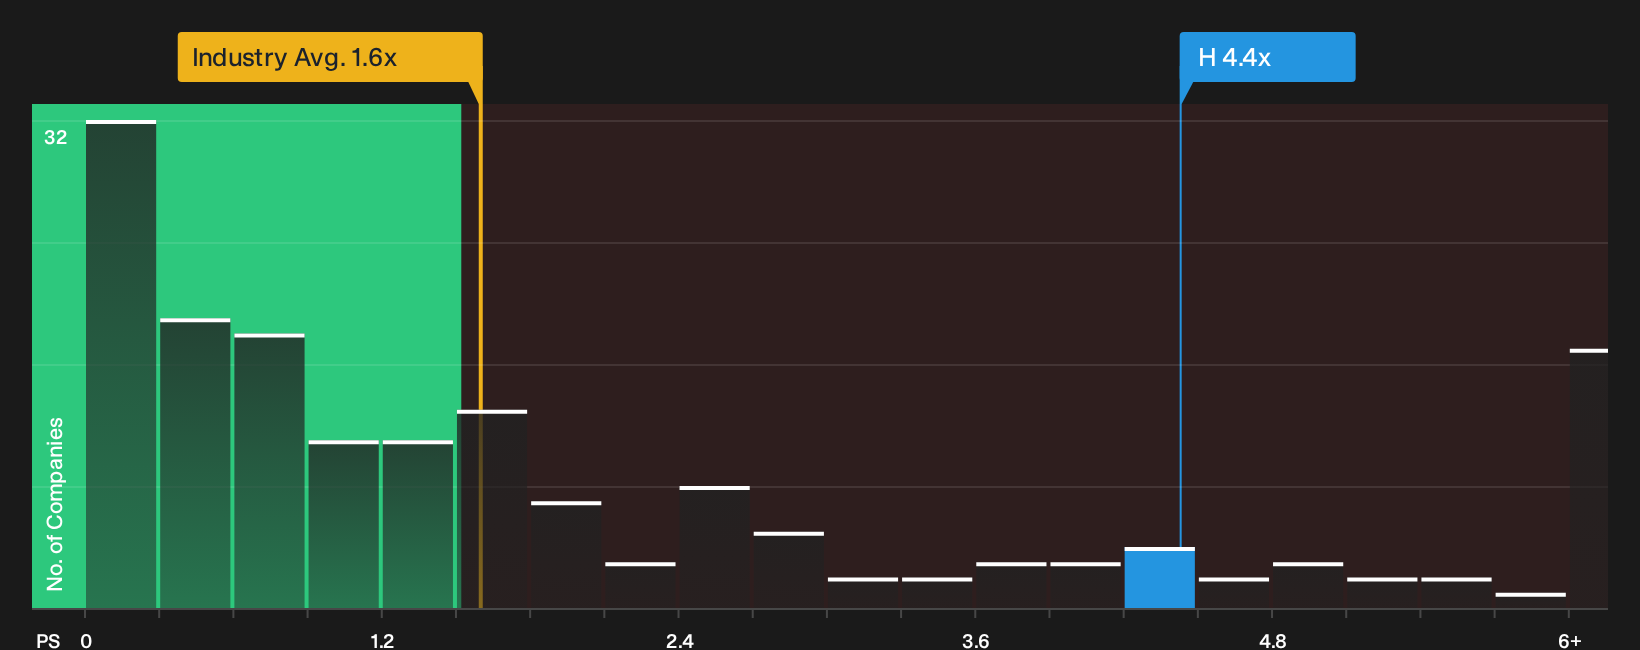
The story looks very different once price is compared to sales. Hyatt Hotels trades on a P/S ratio of about 4.4x, while the US Hospitality industry averages 1.6x and direct peers sit near 2.2x. The Simply Wall St fair ratio of 3.4x suggests the market could shift closer to that level over time, which raises the question of how much valuation risk investors are really willing to carry.
To see how this pricing gap fits alongside the wider earnings and cash flow picture, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
For a simple visual read on how Hyatt Hotels compares against the rest of the sector on this measure, check the latest chart here
Next Steps
With sentiment on Hyatt Hotels clearly split between opportunity and caution, consider moving quickly, reviewing the underlying numbers, and weighing both sides of the story for yourself with 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Hyatt Hotels?
If Hyatt Hotels has your attention, do not stop here. Cast the net wider and you might spot opportunities before the crowd notices them.
- Target potential mispricings by working through a curated set of companies that screen as high quality yet overlooked using the 19 high quality undiscovered gems.
- Build in some downside protection by focusing on businesses that combine strong balance sheets with solid fundamentals through the list of solid balance sheet and fundamentals (26 results).
- Lock in a steadier income stream by filtering for companies offering higher yields and resilient payouts using the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com