


Free Cash Flow Outlook Might Change ATI Stock Narrative
- ATI Inc. recently updated its outlook and now guides to adjusted free cash flow of US$550 to US$600 million for 2026, citing stronger operating performance supported by aerospace and defense demand, pricing, and targeted investments.
- The higher 2026 cash flow guide signals that ATI’s operational tweaks and mix toward higher value aerospace and defense work are feeding more dollars into the business to reinvest or return to shareholders.
- We will now see how ATI’s investment narrative could be affected by this higher 2026 adjusted free cash flow target.
Scan how ATI’s upgraded cash flow guide compares with peers by sizing up other aerospace and defense suppliers on our hand picked 31 resilient stocks with low risk scores list.
ATI Investment Narrative Recap
To own ATI, you need to be comfortable with a business that leans heavily into aerospace and defense demand, higher value alloys, and complex components. The raised 2026 adjusted free cash flow guide to US$550 to US$600 million supports that story by pointing to better cash conversion as current contracts and efficiency projects flow through.
The near term swing factor is whether ATI can keep execution tight while funding heavy capex and managing a high debt load. The biggest risk still looks tied to concentration in large aerospace OEMs and softer industrial and medical markets, which this guidance update does not materially change.
The most relevant recent development related to this cash flow upgrade is ATI’s ongoing investment in debottlenecking nickel and titanium capacity and in process automation. Those projects are already linked to stronger High Performance Materials & Components margins and better incremental profit capture, which helps explain why management raised the 2026 cash flow guide.
For you as a shareholder, that creates a clear scoreboard. Watch whether these capacity and alloy investments keep showing up in higher margins, steadier earnings, and actual free cash coming through after capex and interest. If that operational payoff stalls, the combination of high P/E, leverage, and concentrated aerospace exposure becomes harder to justify.
On these analyst assumptions, ATI's story ties to revenues of US$6.3b and earnings of US$1.0b by 2029, built on forecast revenue growth of 10.1% per year and an earnings step up of roughly US$524m from current earnings of US$475.8m.
Uncover how ATI's fair value indicates a 35% potential upside to its current price before that discount narrows.
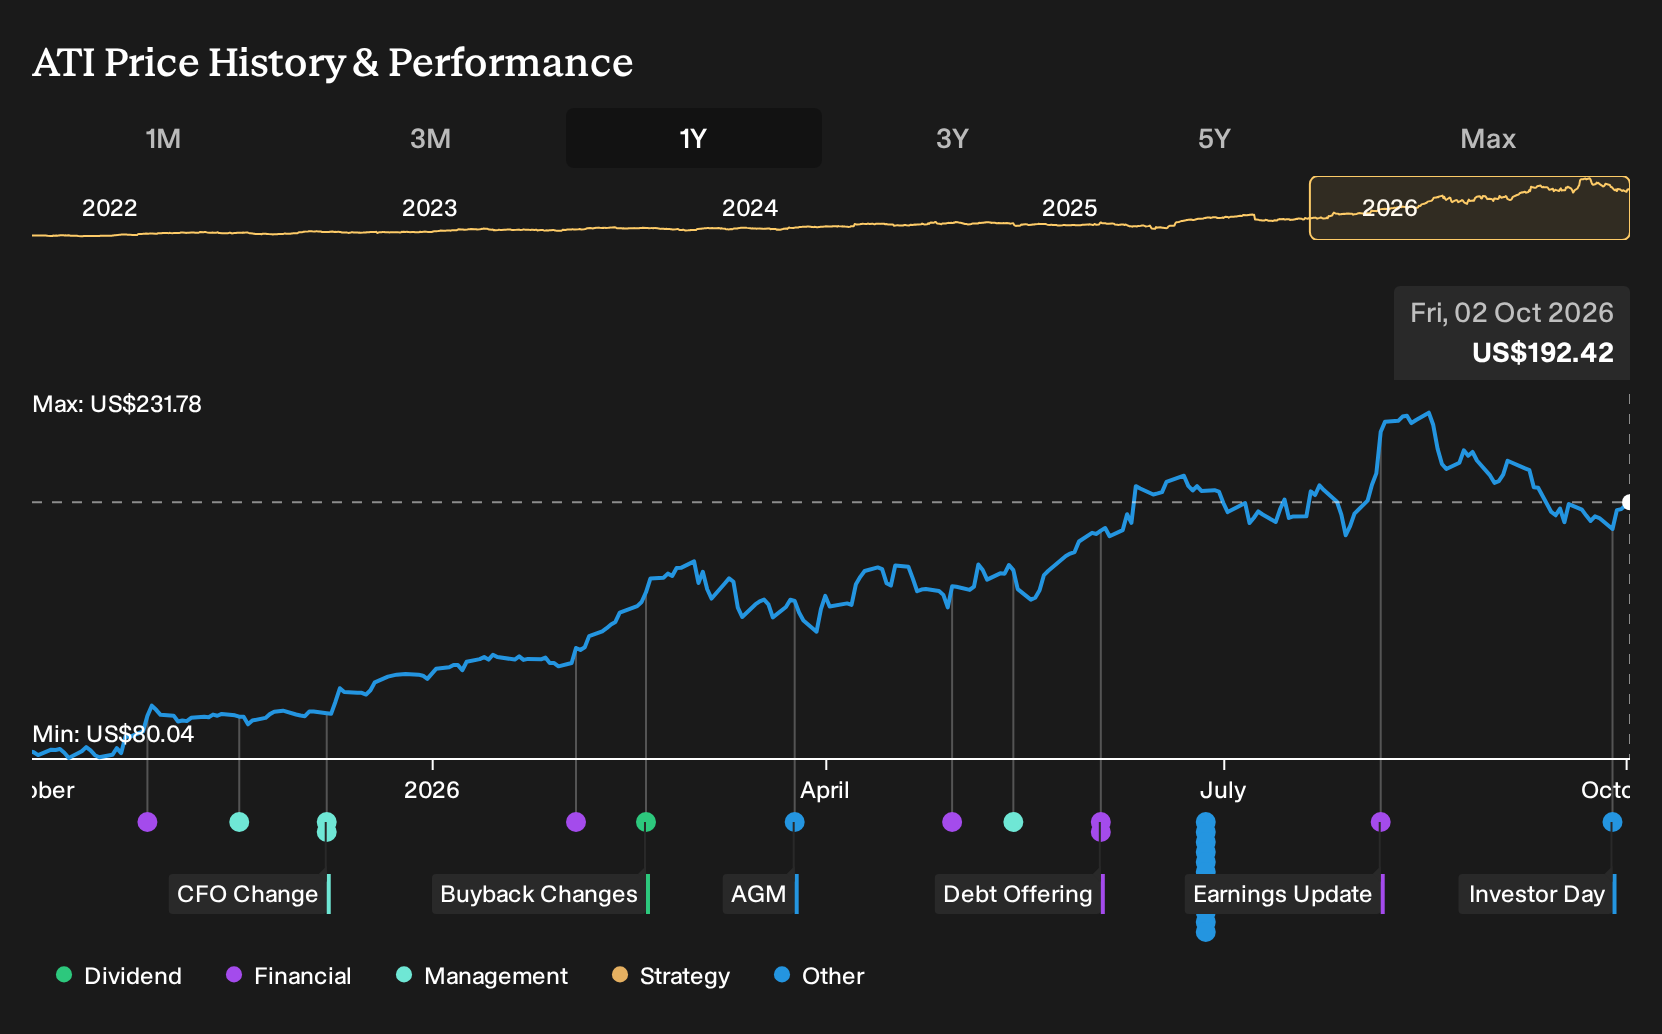
Exploring Other Perspectives
One contrasting angle on ATI focuses on the risk that advanced substitutes slowly chip away at demand for its alloys. The lowest analysts were already penciling in 9.8% annual revenue growth to about US$6.2b and earnings of roughly US$999.7m by 2029. You can treat this upgraded cash flow news as a fresh reason to compare those more cautious assumptions with other viewpoints.
Explore 4 other ATI fair value estimates, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your ATI research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ATI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ATI's overall financial health at a glance.
Looking For More Ideas Beyond ATI?
If ATI has sharpened your interest in cash generative industrials, it can help to widen the search to other businesses with different balance sheet profiles, income streams, or risk levels.
- For investors who care most about stability, start with a list of solid balance sheet and fundamentals (26 results) that can handle shocks without constant refinancing worries.
- If value is your priority, filter for companies trading on attractive fundamentals through a curated 31 high quality undervalued stocks backed by stronger cash flow and balance sheet quality.
- Income focused investors can zero in on reliable payers by scanning a targeted 7 dividend fortresses that screens for higher yields with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com