


Post Holdings (POST) Stock Looks Undervalued At Today’s Earnings Price
Post Holdings has seen a sharp reset in its share price, and the drop over the past year puts fresh focus on what investors are really paying for its earnings today. With the stock now trading at US$72.56, the key issue is whether that level still lines up with the profit engine underneath the business.
- The share price has fallen 32.4% over the past year, which raises the question of whether the recent slide has pushed earnings expectations out of sync with where the stock now trades.
- The group’s value story is closely tied to how reliably it can turn its branded food portfolio into steady profit margins and cash generation, which can shape how much investors are willing to pay for each dollar of earnings.
- Your read on Post Holdings is one view; the desks covering it have another. See what analysts think Post Holdings's shares could be worth.
The stock’s next move may depend on whether Post Holdings’ current earnings justify today’s valuation or suggest that the market is pricing its profit stream too optimistically or too cautiously.
If you want a clear comparison of what investors are paying for earnings across similar opportunities, place Post Holdings next to the 31 high quality undervalued stocks.
Does Post Holdings Look Undervalued on Earnings?
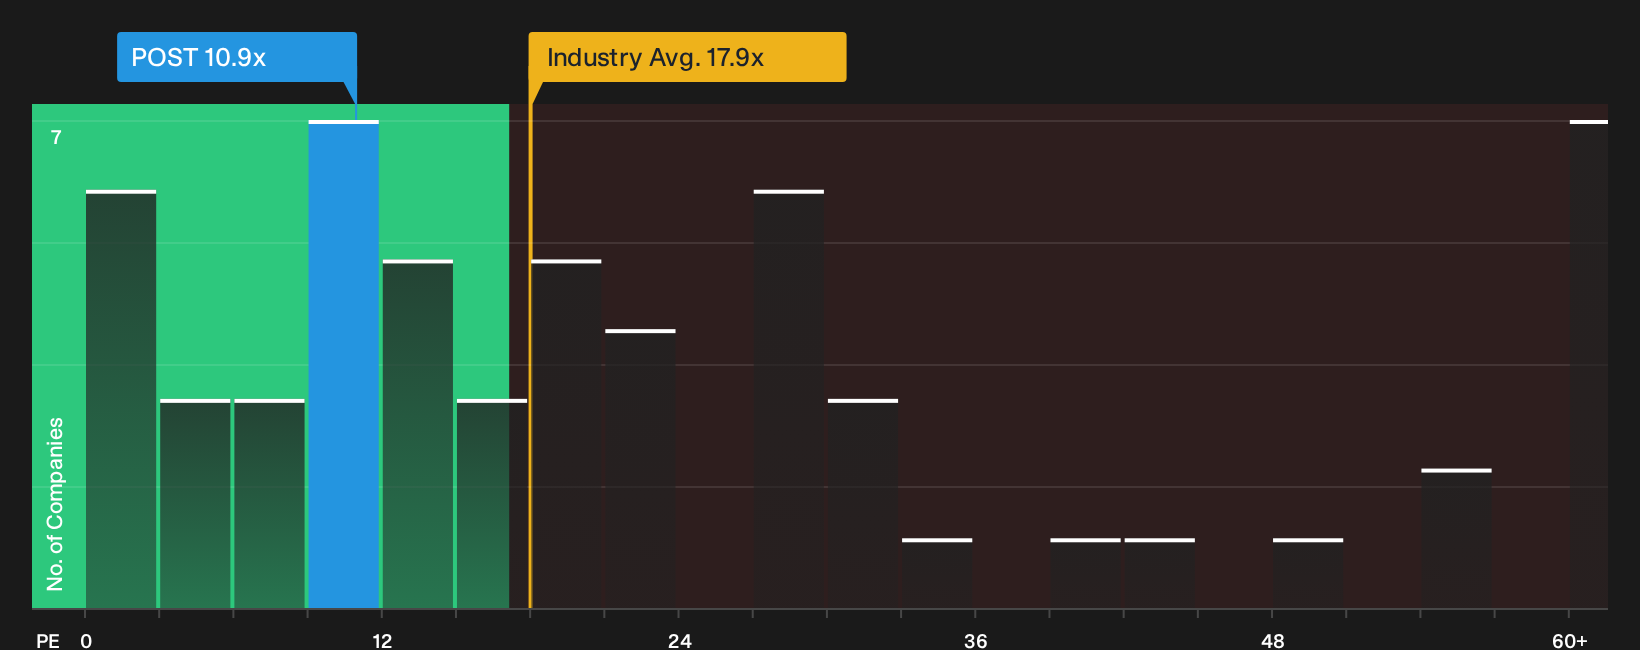
P/E is a useful yardstick for Post Holdings because earnings are a central way investors frame mature branded food businesses. On this measure, the stock changes hands at about 10.9x earnings, which is well below the food industry average of roughly 17.9x and also under the wider peer group near 25.8x.
The fair P/E that would typically be expected for Post Holdings, after accounting for its margins, growth profile, sector and risk, appears higher than where the shares trade today. That gap suggests the current P/E points to the stock being undervalued on this framework, with the market placing a relatively low price on each dollar of profit compared with similar companies with comparable characteristics. Explore the numbers behind Post Holdings's P/E valuation.
The Post Holdings Narrative: What Would Justify Today's Price?
Narratives on Post Holdings pick up from that P/E puzzle and explain which future paths for growth, margins, and earnings would line up with a higher or lower price than you see today. Each one turns Post Holdings' implied fair value into a clear, testable view about how the business might perform, so you can watch over time how those assumptions hold up against new information on the Community page.
One of the top community narratives on Post Holdings: 31% undervalued
"The current valuation implies that Post Holdings is priced as if its higher Foodservice earnings run-rate and ongoing margin work in cereal and pet food will not be fully reflected in the share price…"
Discover why this Narrative puts Post Holdings at 31% undervalued.
One more factor to weigh before relying on Post Holdings' valuation alone
Price tags tell only part of the story for Post Holdings, because the people directing capital and how they are rewarded can heavily shape future outcomes. See who runs Post Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com