


Healthpeak Properties (DOC), What Is Behind The Fresh Attention Today?
Healthpeak Properties (DOC) kicked off October with a fresh dividend decision, declaring a monthly common stock cash payout of $0.10167 per share for the fourth quarter of 2026.
Healthpeak Properties shares have eased in recent weeks, with a 30 day share price return down 7.32% and a 90 day move down 10.96%. However, the year to date share price return of 20.31% and 3 year total shareholder return of 37.00% suggest that longer term momentum has been stronger than the recent pullback implies.
Look beyond Healthpeak Properties and compare this dividend REIT with a curated 7 dividend fortresses that pair regular income with substantial yields.
For Healthpeak Properties, that recent slide could signal investors are rethinking the healthcare real estate story, or it could just reflect sentiment resetting after a strong run. Which explanation does the current valuation seem to back up?
Most Popular Narrative: 15% Undervalued
On the latest numbers, the most followed narrative puts Healthpeak Properties at a fair value of $23.05, compared with a last close of $19.49. This frames the recent price pullback as a potential gap between trading levels and that valuation view.
The accelerating shift of surgical and specialty care from inpatient hospital settings to outpatient centers supported by anticipated regulatory changes (CMS inpatient only default reversal) is set to drive sustained tenant demand and pricing power for Healthpeak's modern, high-acuity outpatient medical buildings, which should translate into increased occupancy rates and same-store NOI growth.
See why 34 investors see Healthpeak Properties as 15% undervalued.
Putting the numbers together, that popular narrative uses an 8.1% discount rate and arrives at a $23.05 fair value for Healthpeak Properties, alongside a stated 15.5% discount to that estimate at current prices. The share price also sits below the $23.05 analyst consensus target referenced in the same narrative. Those analysts describe this as implying the stock is roughly fairly priced on their assumptions. Result: Fair Value of $23.05 (UNDERVALUED)
Still, if credit conditions worsen for smaller biotech tenants or capital markets stay tight for longer, the bullish Healthpeak Properties story could lose momentum.
Find out about the key risks to this Healthpeak Properties narrative.
Another Take On Healthpeak Properties Valuation
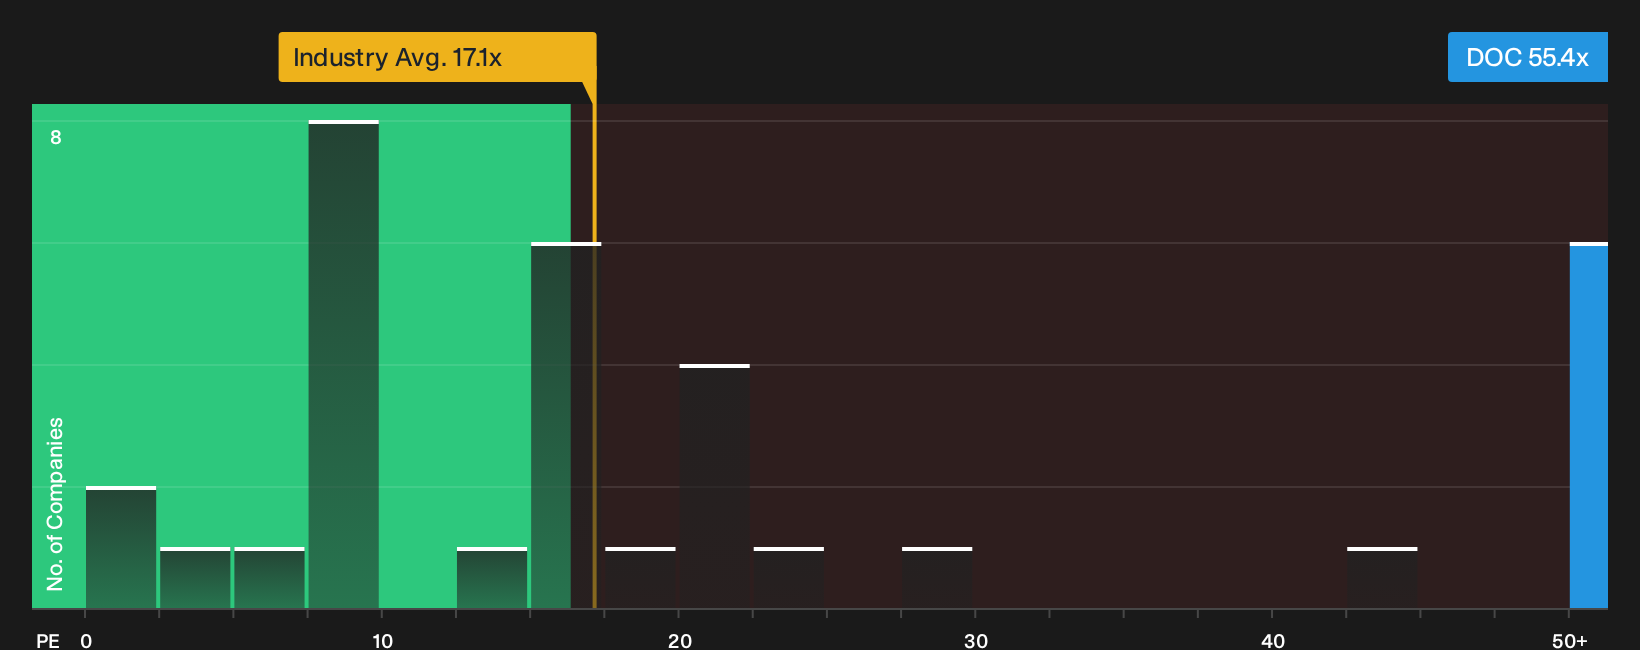
The earlier analyst narrative points to a fair value of $23.05 for Healthpeak Properties based on future earnings assumptions and price targets. A different lens tells a rougher story. At a P/E of 55.4x, the stock trades well above its own fair ratio of 21.9x and the global Health Care REITs average of 17.1x, even though it is below peers at 62.7x. That gap can point to either rerating risk if sentiment cools or support if investors continue to pay a premium for perceived quality. Which side of that trade-off appears more compelling to you right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Healthpeak Properties can pull you in both directions, so move quickly to test the data and weigh the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Healthpeak Properties?
If you stop with Healthpeak Properties, you risk missing other opportunities that better match your risk, income, or growth goals on Simply Wall Street.
- Target reliable income streams by scanning dividend-focused opportunities through the 7 dividend fortresses tailored for investors who want regular cash returns.
- Hunt for potential value gaps by checking companies in the 31 high quality undervalued stocks that combine strong fundamentals with discounted valuations.
- Spot tomorrow's potential standouts early by filtering for high quality smaller players in the 19 high quality undiscovered gems before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com