


Suncor Energy And 2 Canadian Undervalued Stocks
Eurozone inflation recently reached a 3 year high as fuel and energy costs bit harder into household budgets. That kind of backdrop often pushes investors toward solid cash generators, especially when those businesses trade below what careful valuation work suggests they are worth. This article looks at a group of Canadian stocks that fit that bill and highlights three that stand out on discounted cash flow metrics.
The stocks covered below are just a starting sample, and the full screen surfaced 5 more companies with equally compelling cash flow stories and valuation setups that are not included in this article.
If you want to go straight to the source and identify, analyze, and shortlist your own opportunities, head into the Undervalued Stocks Based On Cash Flows screener.
Suncor Energy (TSX:SU)
Suncor Energy is a large integrated producer. Its Oil Sands operations supply bitumen and synthetic crude that feed its refineries and retail fuel network, creating the kind of recurring cash generation this screener theme is built to highlight.
Suncor Energy runs a broad energy platform anchored in Oil Sands production. That segment generates about CA$26.9b of revenue, alongside CA$36.8b from Refining and Marketing and a CA$2.5b contribution from Exploration and Production, supporting a business valued at roughly CA$115b by the market.
"Plans to outline a 15 year bitumen supply and development program, including options such as Lewis and additional Firebag phases, indicate a scenario where sustaining and potential growth projects may compete with shareholder returns for capital if costs rise."
The real test for Suncor Energy will come if a single pressure on future cash generation shifts from a helpful tailwind to an uncomfortable squeeze.
If that squeeze ever bites, you will want the full narrative for Suncor Energy that explains how Suncor Energy could aim to keep returns moving instead of letting them stall.
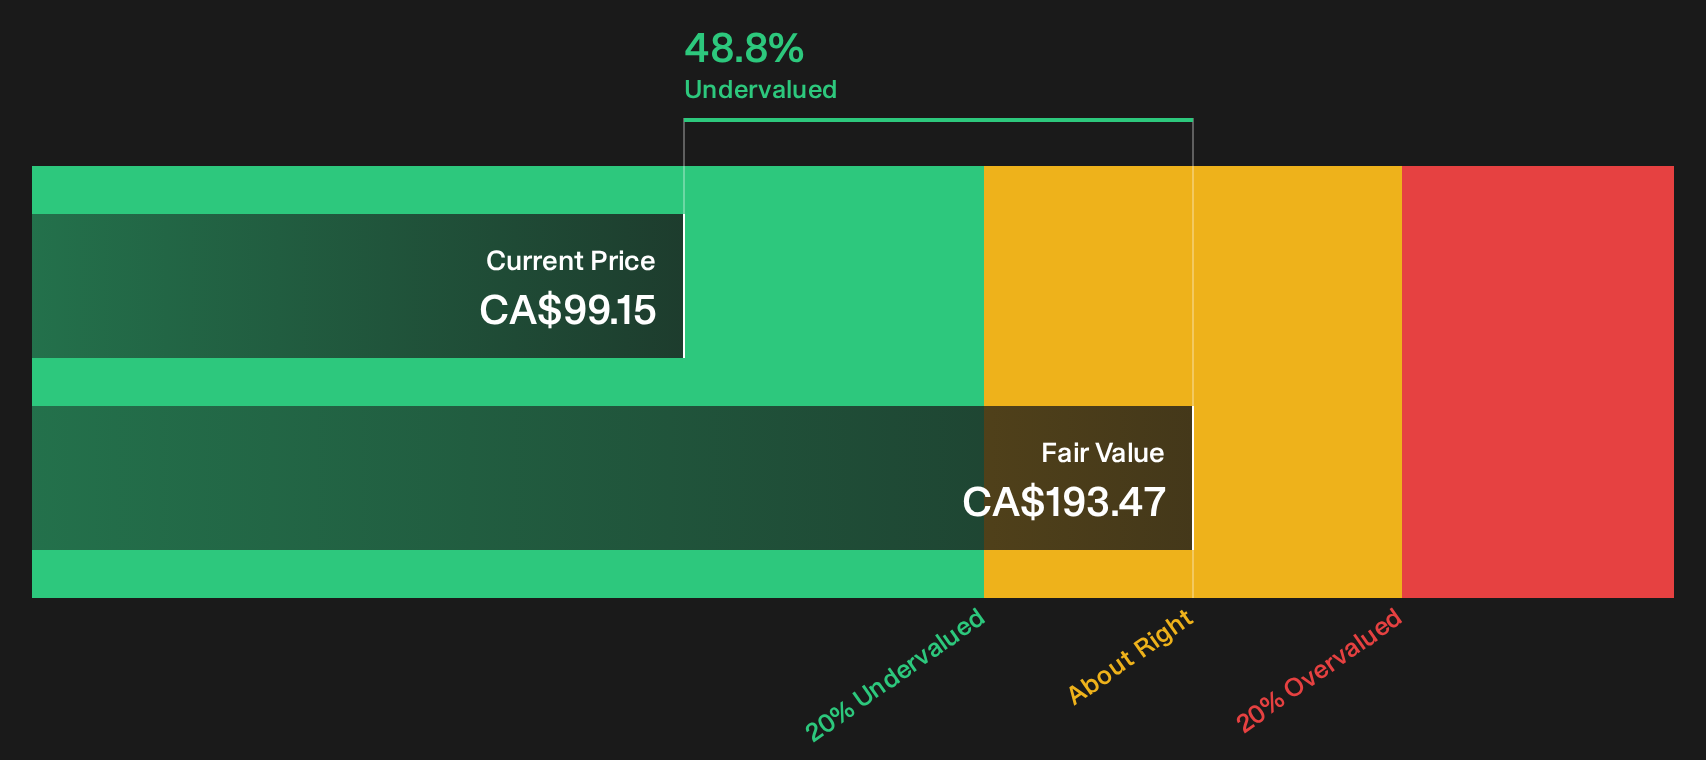
Chemtrade Logistics Income Fund (TSX:CHE.UN)
Chemtrade Logistics Income Fund supplies essential industrial and water-treatment chemicals, with its Sulphur and Water Chemicals arm providing the recurring cash flows that anchor its place in this undervalued cash-flow screen. Most revenue comes from Electrochemicals at about CA$739m, and the fund is valued near CA$1.6b.
Chemtrade Logistics Income Fund fits this cash-flow theme because its water and sulphur products are sold under recurring, long-term arrangements, which can make unit price swings look more dramatic than the underlying contracts that support them.
"Chemtrade's expanding focus on water treatment solutions, reinforced by the Polytec and Thatcher acquisitions, is often cited as a way for the company to align with rising demand from municipalities and food processing industries, with some observers highlighting potential implications for revenue and earnings stability as water scarcity and regulatory pressures intensify globally."
The main area of focus for Chemtrade Logistics Income Fund now lies in how one pressure on its funding mix may influence future cash returns if conditions change.
That funding pressure is exactly where the story gets interesting, and the full narrative for Chemtrade Logistics Income Fund shows how Chemtrade Logistics Income Fund could turn it into accelerating, contract backed cash strength.
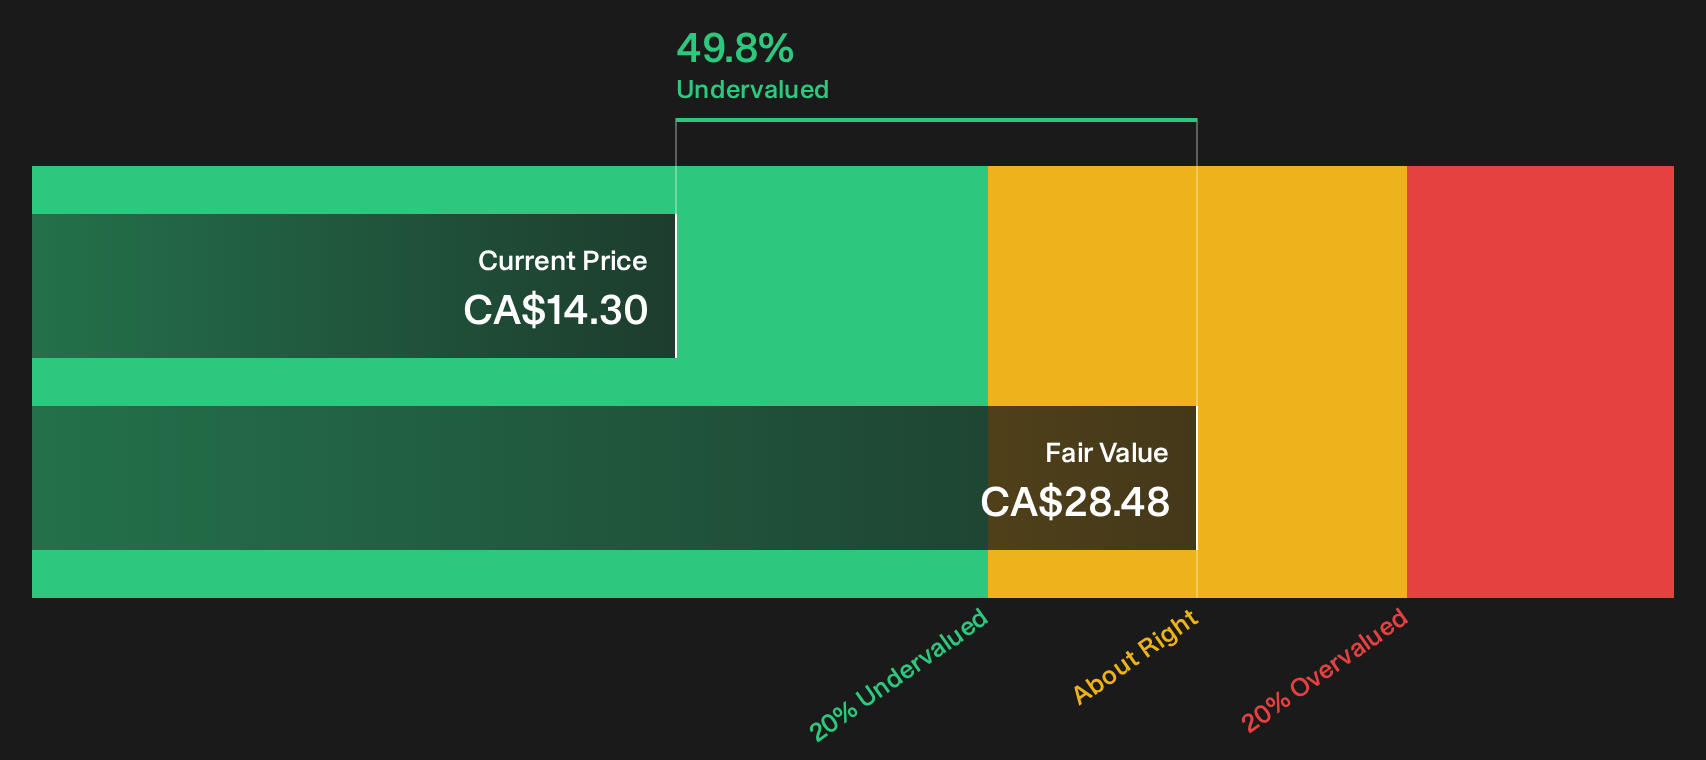
Canadian Natural Resources (TSX:CNQ)
Canadian Natural Resources is a large oil and gas producer tied tightly to the cash flow story in this screener, with its upstream crude and natural gas operations giving valuation models plenty of recurring output to work with.
Canadian Natural Resources produces and sells crude oil, natural gas and NGLs across Western Canada, the North Sea and Offshore Africa, with about CA$21.3b from North American exploration and production, CA$20.8b from Oil Sands Mining and Upgrading, and CA$1.0b from Midstream and Refining, supporting a roughly CA$140.3b market value.
"Recent accretive acquisitions have expanded production and reserves with minimal increase to the 2025 capital budget, positioning Canadian Natural for immediate cash flow growth and increased future revenues as these assets are developed."
The real swing factor for Canadian Natural Resources is what happens if one pressure on future margins shifts from a quiet tailwind to a stubborn drag.
If that margin drag is what you are watching, the full narrative for Canadian Natural Resources explains how Canadian Natural Resources could keep cash generation accelerating instead of stalling.
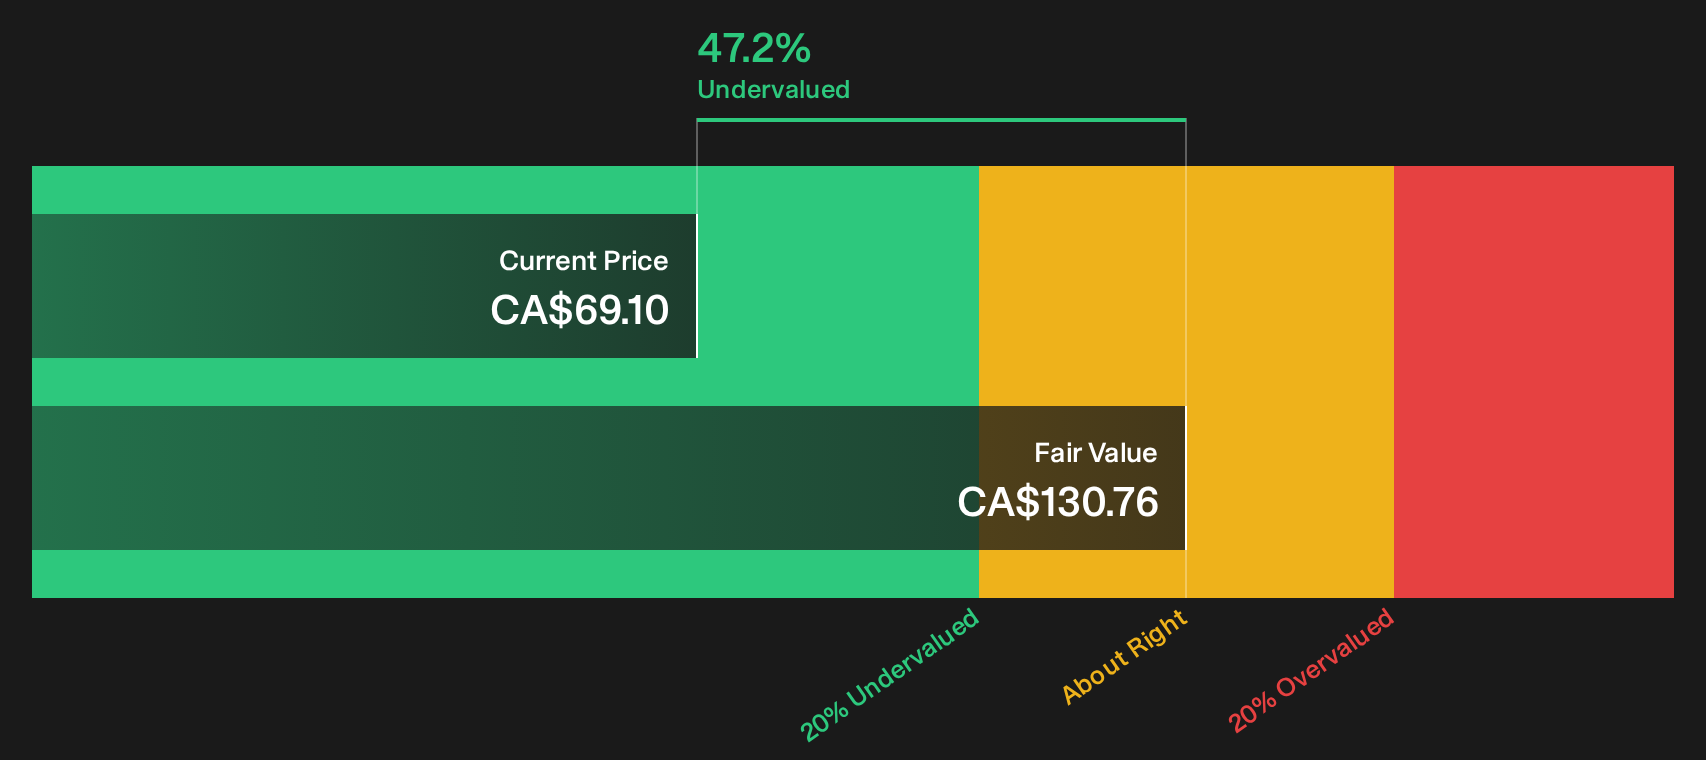
Seeking Fresh Alternatives Before Others?
Fresh ideas tend to move first. Breakout stories can gain momentum while prices are still under the radar for now. Consider your approach to entry points carefully.
- Review cash generative businesses built for resilience by scanning the curated list of solid balance sheet and fundamentals (7 results) rather than reacting after valuations become stretched.
- Focus on income momentum by examining the carefully filtered 1 dividend fortresses instead of waiting until yields change and leading payers become more widely followed.
- Evaluate potential infrastructure opportunities by reviewing the hand picked 40 power grid technology and infrastructure stocks while these investments are still trading quietly, rather than after they appear in major headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com