


What Ventia Services Group Stock's WA Contract Extension Means For Shareholders
- Ventia Services Group announced that the Government of Western Australia extended its Court Security and Custodial Services contract, expected to add about A$110 million of revenue from March 2027 through June 2028.
- The extension reinforces Ventia Services Group's role in long-duration government outsourcing and highlights how contract renewals can influence revenue visibility and operational planning across its broader portfolio.
- This article examines how Ventia Services Group's investment narrative is shaped by this A$110 million Western Australia contract extension.
Scan how Ventia Services Group's contract-based revenue model compares with other government-focused operators by checking our curated list of list of solid balance sheet and fundamentals (12 results).
Ventia Services Group Investment Narrative Recap
To own Ventia Services Group, you need to be comfortable with a contractor that leans heavily on long term government work for stability, then tries to lift earnings through efficiency and contract selection. The Western Australia Court Security and Custodial Services extension fits that story, but is modest against a A$5.9b top line and record A$20.6b work in hand.
The more immediate swing factor remains how Ventia Services Group manages margins and labour and inflation pressures as contracts mature or get retendered. Dependence on public sector spending is still the main risk. This A$110m extension slightly improves revenue visibility but does not change that core exposure.
The contract renewal sits alongside earlier wins in telecommunications and energy infrastructure such as the nbn, Telstra and Transgrid related work that fed into the A$20.6b work in hand. For you, the common thread is execution on large, multi year agreements with complex service requirements and often tight pricing.
Those prior awards matter when you think about catalysts. They show where Ventia Services Group is concentrating, away from commodity style contracts and into areas where digital tools and network expertise can support returns. Set against risks like high debt and potential cost creep, progress on these operational programs is likely to matter more than any single A$110m extension.
Ventia Services Group's current analyst narrative points to revenue of A$7.2b and earnings of A$314.5m by 2029, based on an assumed 5.2% yearly revenue growth rate and an earnings uplift of about A$42.3m from A$272.2m today.
Uncover why Ventia Services Group's fair value is in line with its current price.
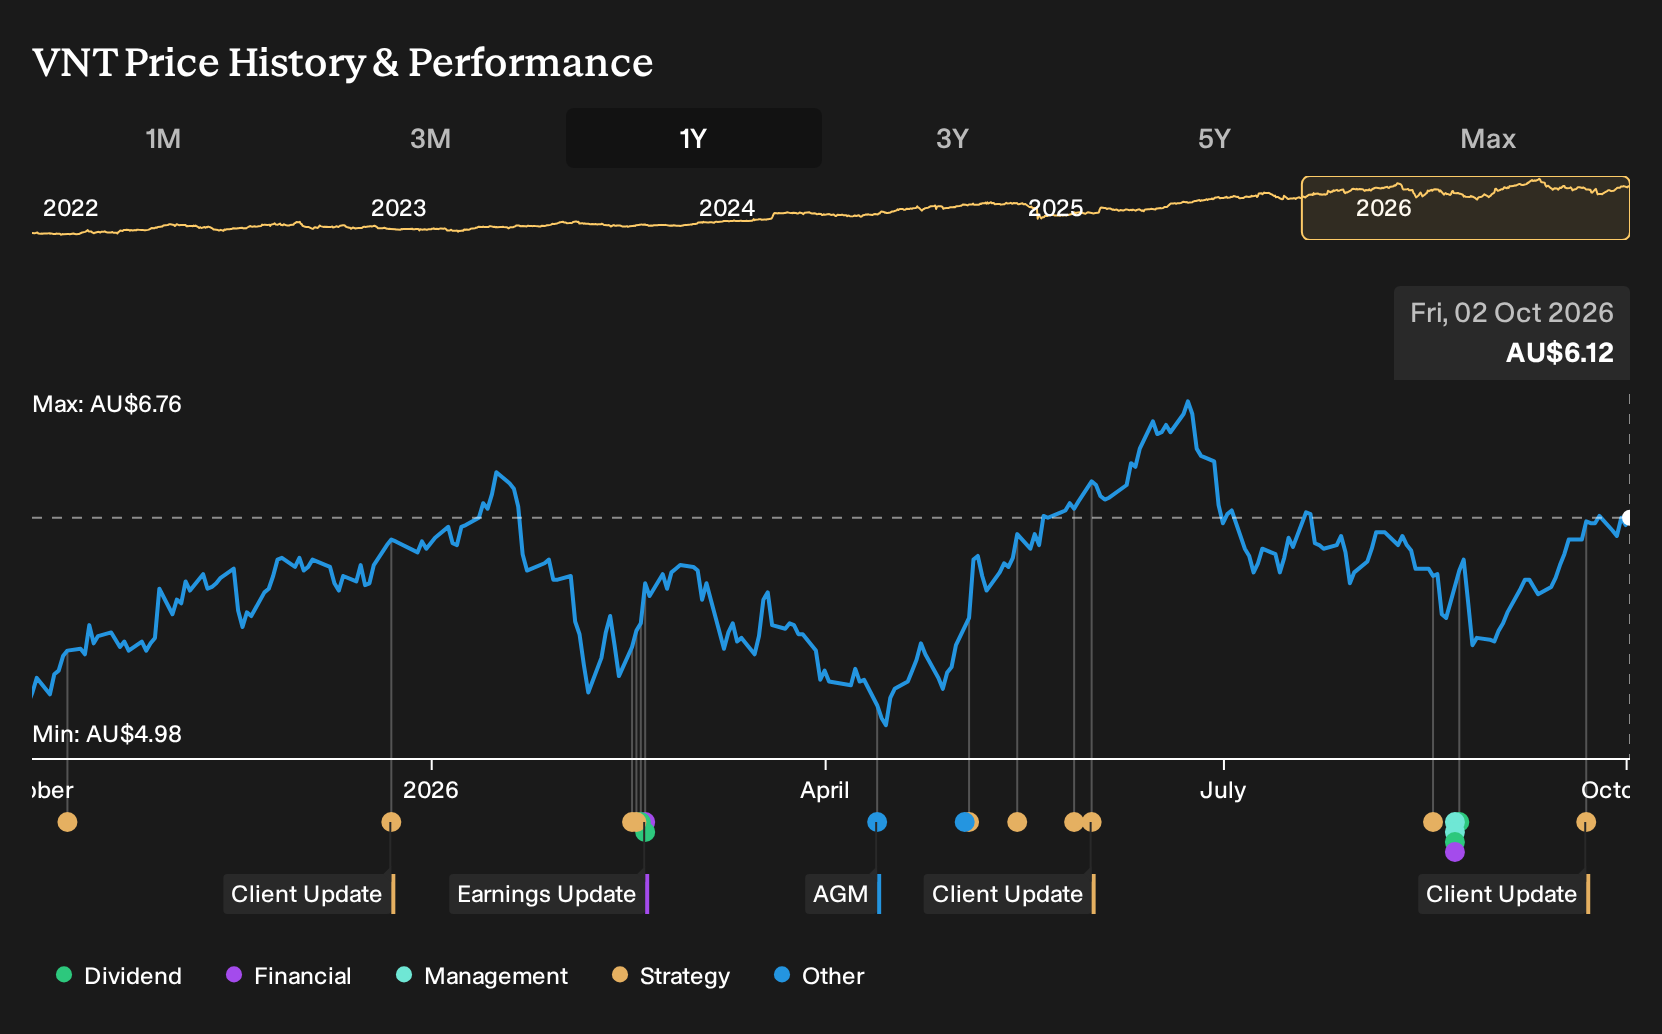
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly A$6.17 to A$10.09 per Ventia Services Group share, which is a wide gap for such a small sample. That spread sits against contract risks tied to government budgets and retendering, so you are seeing sharply different opinions. Explore them.
Explore another Ventia Services Group fair value estimate, including one that suggests potential upside of up to 65% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ventia Services Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ventia Services Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ventia Services Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ventia Services Group?
If you want to balance your view on Ventia Services Group with fresh opportunities, the Simply Wall St screener is an efficient way to surface stocks that fit very different playbooks, from value to income to resilience.
- For investors who want quality on sale, filter for companies that combine strong fundamentals with attractive pricing using the 5 high quality undervalued stocks.
- If dependable income matters to you, focus on businesses that pair higher yields with financial resilience by scanning the 3 dividend fortresses.
- To tilt your portfolio toward sturdier balance sheets and steadier risk profiles, sort through our 7 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com