


Should Carbon Capture Plans Require Action From Suncor Stock Investors?
- Canadian Natural Resources, Suncor Energy, Cenovus Energy, Imperial Oil and ConocoPhillips Canada previously agreed to advance the Pathways CCS project. The project targets capture of about 6 million tonnes of CO2 annually by 2035 and 16 million tonnes by 2045 under a trilateral MOU with Canada and Alberta that remains conditional.
- The linkage of potential oil sands expansion to large scale carbon capture spending highlights how Suncor Energy’s long term cost base and emissions exposure could increasingly depend on government support and final project economics.
- We will now look at how Suncor Energy’s investment narrative could be shaped by its role in the Pathways carbon capture project.
Look beyond Suncor Energy and this CCS alliance by evaluating other oil and gas producers with balance sheets that can accommodate significant decarbonisation spending using our curated list of solid balance sheet and fundamentals (7 results).
Suncor Energy Investment Narrative Recap
Suncor Energy appeals to investors who believe its integrated model, from oil sands to refining and marketing, can keep generating strong cash flows even if headline earnings soften. The near term story still hinges on operational reliability, cost control and how well refining margins offset any weaker crude price environment.
The Pathways CCS news does not change the key short term catalyst, which is execution on production efficiency and disciplined capital spending. It does, however, sharpen the biggest risk already on the table, that high emission oil sands exposure could face rising carbon costs and tighter regulation that pressure unit economics.
The Pathways Carbon Capture and Storage project commitment is the announcement that matters most here. It ties Suncor Energy’s longer term capital needs more tightly to decarbonisation spending at the same time analysts already expect revenue and earnings to decline over the next three years.
There is execution risk. Cost overruns, unclear subsidy frameworks or tougher carbon pricing could all weigh on future returns from oil sands barrels. For shareholders, the practical question is how much CCS spending the balance sheet can absorb while still funding maintenance capex, debt service and any future dividends or buybacks.
Suncor Energy's current analyst narrative points to revenues of CA$53.7b and earnings of CA$7.8b by 2029, based on an assumed yearly revenue decline of 1.7% and an earnings decrease of CA$1.1b from CA$8.9b today.
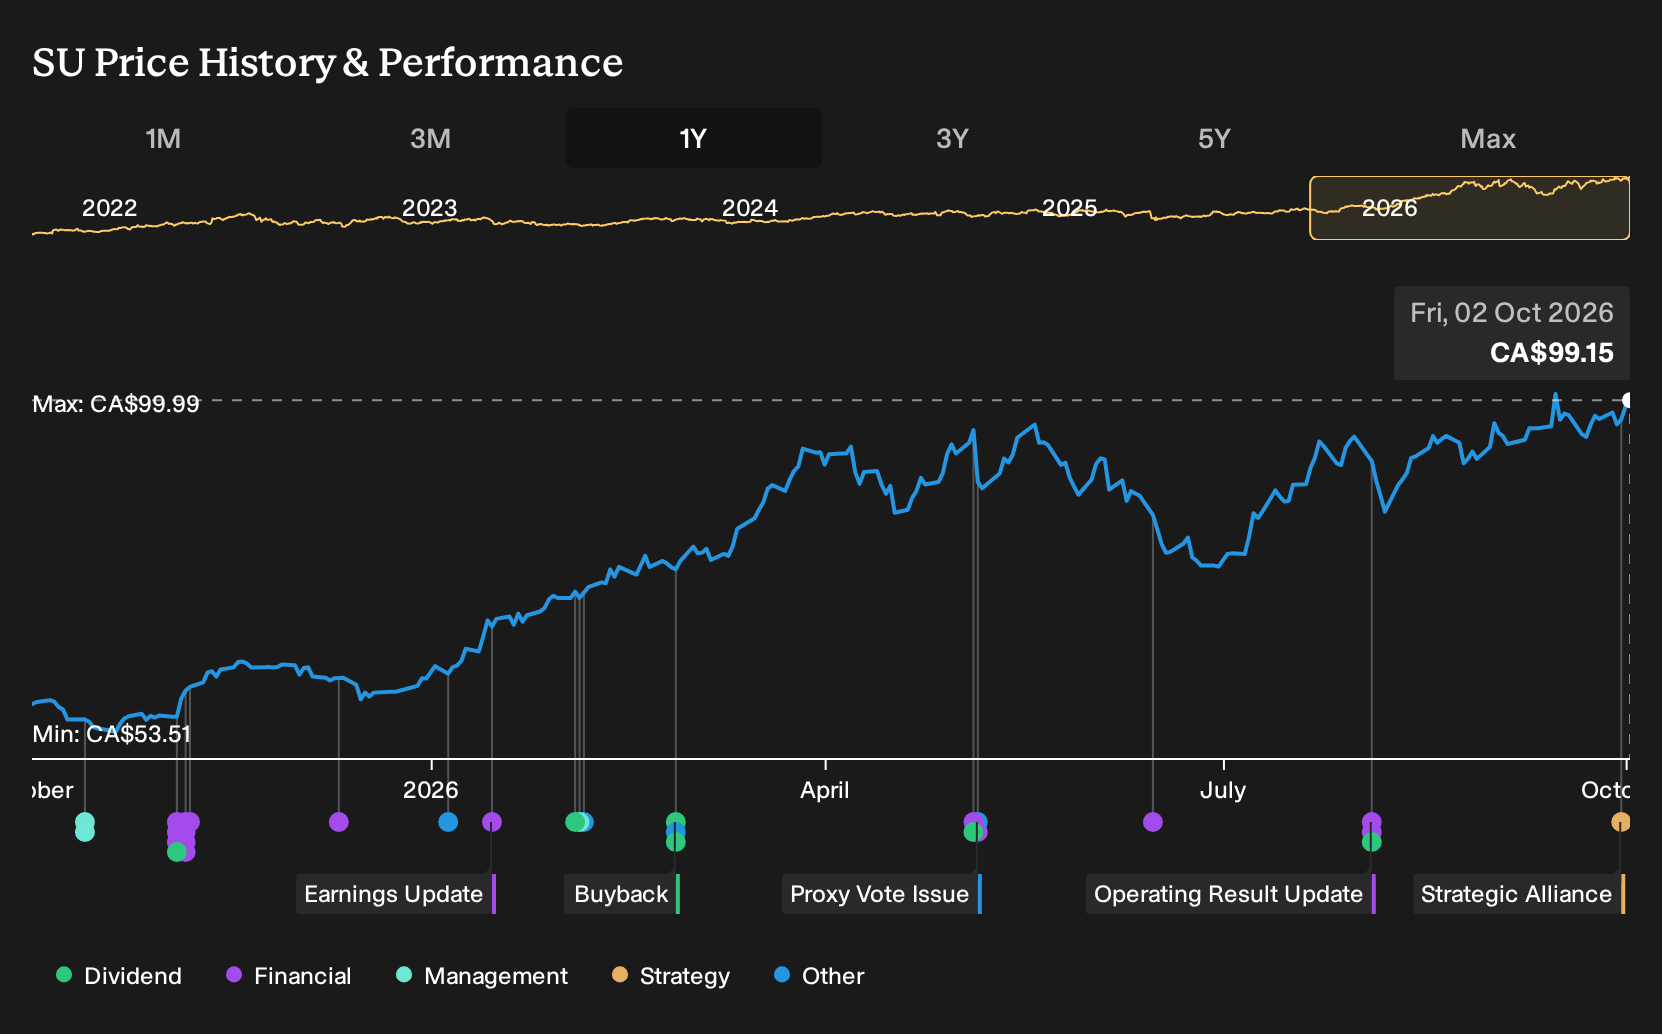
Uncover how Suncor Energy's fair value indicates an 8% potential upside to its current price before buyers close that discount.
Exploring Other Perspectives
You can read the Pathways CCS commitment as a fresh catalyst or as one more constraint. The most pessimistic Suncor Energy analysts were already modelling steeper revenue pressure, with revenue expectations of about CA$49.4b and earnings near CA$5.3b by 2029. Their storyline is clearly tougher. Both narratives may evolve as the CCS terms firm up.
Explore 4 other Suncor Energy fair value estimates, including one that suggests as much as 7% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Suncor Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Suncor Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Suncor Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Suncor Energy?
If you want to pressure test your view on Suncor Energy and widen your opportunity set at the same time, use the Simply Wall St Screener to compare businesses with different risk, income and valuation profiles.
- For investors hunting for potential mispricing, scan a curated set of 6 high quality undervalued stocks that combine quality fundamentals with what may be appealing entry points.
- If capital preservation is front of mind, focus on a 8 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- To cast the net wider and avoid crowded trades, look through a collection of 9 high quality undiscovered gems that have solid metrics yet attract less attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com