


3 Canadian Penny Stocks With P E Under 17
Global bond yields have surged to multidecade highs, and investors are hunting for pockets of resilience away from the most crowded trades. That flight to perceived safety has sharpened interest in financially conservative Canadian penny stocks that pair low share prices with cleaner balance sheets. This article walks through three such opportunities from a health focused small cap universe and explains why each could appeal to patient buyers willing to do the homework.
The handful of stocks profiled below are only a small sample of what financially fit penny stocks can look like, and the full screen surfaced 337 more companies with balance sheets and stories that are not covered here.
If you want to move straight from ideas to hands on filtering and analysis, head into the Financially Fit Penny Stocks screener to identify the highest conviction setups for your watchlist.
Cronos Group (TSX:CRON)
Overview: Cronos Group is a cannabinoid-focused cannabis producer that grows, processes, and sells branded cannabis products across Canada and international markets.
Operations: Cronos Group generates about $179 million from cultivating, manufacturing, and marketing cannabis products, mainly in Canada ($105 million) and Israel ($52 million).
Market Cap: CA$1.68b
Cronos Group fits the Financially Fit Penny Stocks theme because its core cannabis brands convert cultivation capacity into real, recurring consumer sales. This provides exposure to a business model anchored in actual product demand rather than blue-sky optionality.
"Expanded cultivation capacity at GrowCo coming online in Fall 2025 should allow the company to address persistent supply constraints and meet robust consumer demand in Canada and key international markets."
Consider what could happen to Cronos Group’s margin profile if a single cost pressure or pricing shift starts to affect that higher value mix.
That margin question is exactly what sits at the heart of the full narrative for Cronos Group, which outlines how Cronos Group could see pricing power, product mix and capital allocation all begin to decouple.

Omai Gold Mines (TSXV:OMG)
Overview: Omai Gold Mines is a Toronto based junior miner focused on acquiring, exploring, and developing its 100% owned Omai gold project in Guyana.
Market Cap: CA$1.45b
Omai Gold Mines ties into the Financially Fit Penny Stocks theme through its single, clearly defined Omai license, a 100% owned gold project with fresh drill results and a detailed economic study. However, the sub $5 share price comes with ongoing losses, a short cash runway, and one unresolved funding pressure that could reshape how investors think about future dilution and value per share.
That funding overhang is exactly why many investors are turning to the 1 key reward and 5 important warning signs (3 are major!) to see whether potential dilution is masking a more attractive Omai Gold Mines story.

McChip Resources (TSXV:MCS)
Overview: McChip Resources is a Toronto based natural resources investor with exposure to petroleum interests and a Saskatchewan potash project.
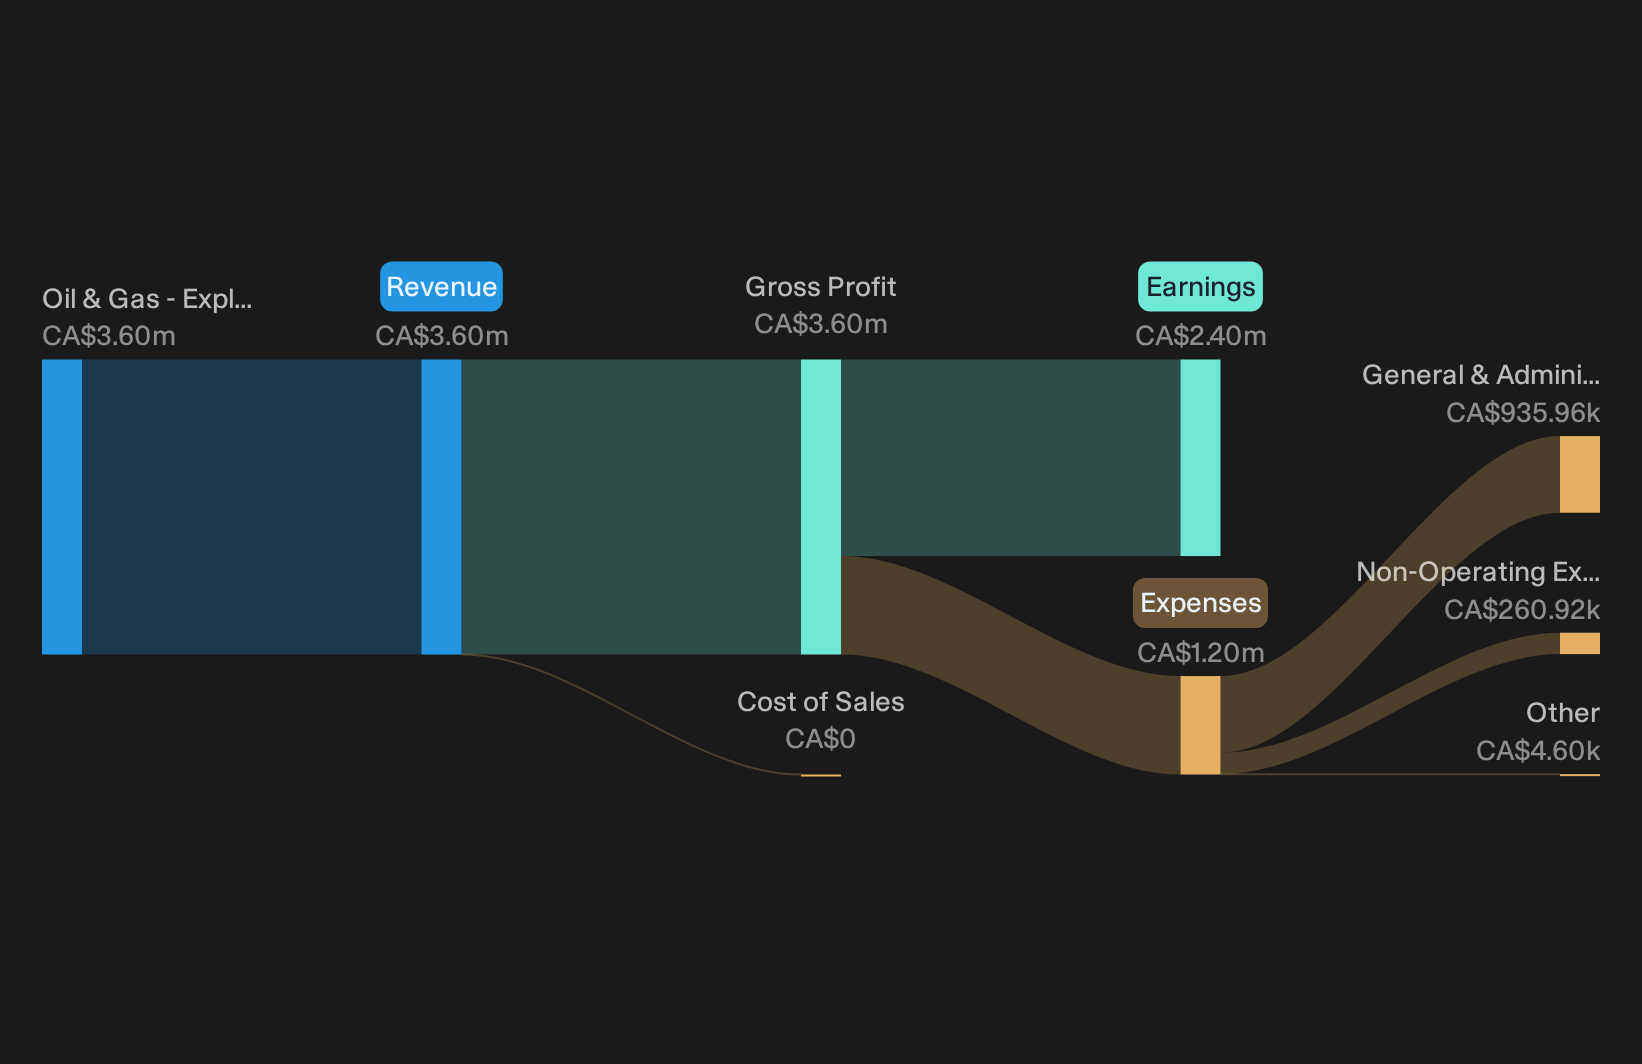
Operations: McChip Resources generates about CA$4 million from oil and gas exploration and production activities in Canada.
Market Cap: CA$4.3 million
For a Financially Fit Penny Stocks theme, McChip Resources offers real asset backing through its oil and gas income and potash exposure, paired with a very low P/E of 1.8x and recent earnings momentum. However, the real test comes if pressure on cash flow and dividend coverage tightens as that resource portfolio matures.
If you want to see how that pressure on cash flow and dividend coverage could reshape the McChip Resources story, start with the analysis report for McChip Resources to get the full picture.
Seeking Fresh Alternatives Before They Fly
Fresh opportunities often move first. Breakout stories gain momentum, then the easy entry points vanish as the crowd catches up. Scan under the radar for now and consider acting before attention increases.
- Spot resilient payers before yields potentially get compressed by income chasers by using the curated 1 dividend fortresses built to highlight consistency over hype.
- Track quantum hardware and software players before sentiment affects valuations by scanning the focused 25 quantum computing stocks while information still moves slowly.
- Target potential breakout trends in copper demand and production with the hand picked 16 top copper producer stocks while price dislocations may still be forming.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com