


Sun Life Financial (TSX:SLF) Launches New U.S. Benefits Offering, Is The Stock Fully Valued?
Sun Life Financial (TSX:SLF) has rolled out a combined Disability with Health Navigator offering in its U.S. business, tying income protection to year round care guidance for employees across employer health plans.
Trading at CA$111.87 on 1 October 2026, Sun Life Financial has paired this U.S. product launch with a strong year to date share price return of 29.6%, while a 38.3% one year total shareholder return and 102.0% five year total shareholder return indicate momentum that long term holders have already experienced.
Scan beyond Sun Life Financial and compare this move in employer health benefits with a curated list of solid balance sheet and fundamentals (7 results) that may offer similar resilience in insurance and financial services.
Sun Life Financial now trades only slightly below the average analyst target, while an internal fair value estimate sits much lower. Which reference point should you treat as the anchor for valuation work from here?
Most Popular Narrative: 90% Undervalued
On the most followed narrative, Sun Life Financial screens as materially undervalued, with a fair value of about CA$112.93 against the CA$111.87 last close. However, that gap narrows sharply when set beside a much higher internal cash flow estimate.
Expansion and resilience of Sun Life's asset management businesses, including SLC Management's alternative and private asset capabilities, are increasing fee-based earnings and reducing reliance on spread income. This is positioning earnings for greater stability and long-term growth. Successful cost efficiency programs and automation initiatives evidenced by realized savings and disciplined expense controls are driving down expense ratios and supporting sustainable net margin improvements over time.
See why 68 investors see Sun Life Financial as 1% undervalued.
Result: Fair Value of CA$112.93 (UNDERVALUED)
Still, the story can change quickly if U.S. Dental pricing pressure persists or if asset management outflows continue to erode fee income at Sun Life Financial.
Find out about the key risks to this Sun Life Financial narrative.
Another View: What Sun Life Financial’s P/E Is Signalling
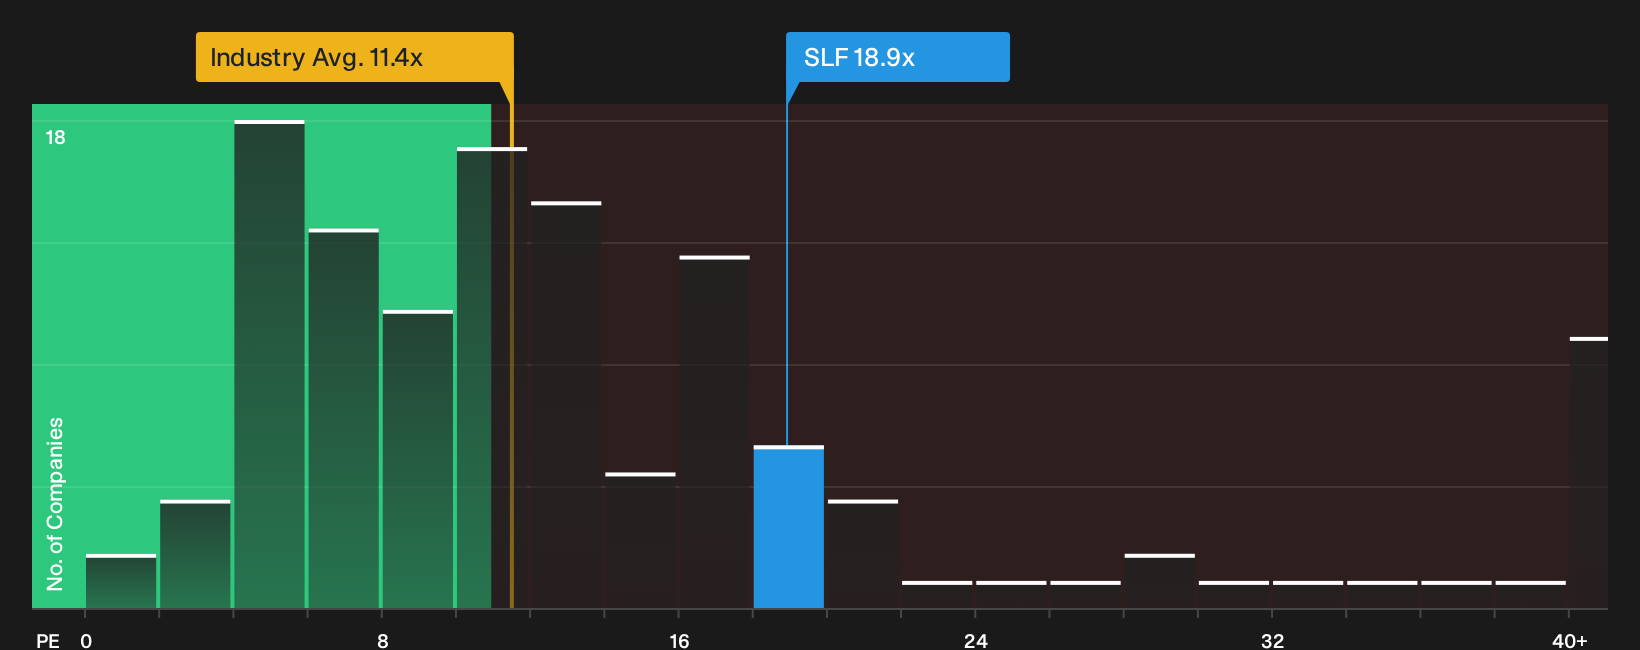
There is a very different message once you switch from cash flow models to simple earnings multiples. Sun Life Financial trades on a P/E of 18.9x, compared with a fair ratio of 14.8x, the North American insurance average of 11.4x and a peer average of 18.2x. That richer multiple against all three benchmarks points to less room for error if earnings or sentiment cool, so how comfortable are you paying up when another yardstick already calls the shares undervalued?
To see how that earnings multiple could shift if expectations change, it helps to step through the full valuation breakdown in our model. This includes the fair ratio that the market could move towards over time, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Sun Life Financial can feel messy, so move fast, review the full data set carefully, and ground your own stance in the 3 key rewards and 1 important warning sign.
Looking for more Sun Life Financial style ideas?
If Sun Life Financial has you thinking harder about quality, do not stop here. The right watchlist often starts with a few smart comparisons.
- Target steadier cash flows by scanning a 8 resilient stocks with low risk scores that filters for businesses with more resilient profiles and fewer red flags.
- Hunt for value opportunities next and review a 6 high quality undervalued stocks that focuses on companies with solid fundamentals trading below internal estimates.
- Round out your watchlist with income potential by checking a 1 dividend fortresses built around higher yield payouts backed by stronger balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com