


Can Altria Group (MO) Trade At A Premium On Earnings?
Altria Group has delivered very strong long term gains, yet the question many investors are circling now is whether the current share price is still supported by its earnings power. After such a long run, you need to know if you are paying a reasonable multiple for the profits the business is generating today.
- Over the past 5 years, the stock has returned about 111.6%, which raises the obvious question of whether earnings growth and durability are enough to support that kind of compounding.
- The business continues to lean heavily on mature tobacco cash flows, which can support valuation if those earnings remain resilient and capital allocation stays focused on shareholder returns rather than large new spending needs.
- The analysts covering Altria Group have run their own numbers. See what analysts think Altria Group's shares could be worth.
The issue now is whether Altria Group's current share price is justified by the earnings that underpin it.
If you are weighing Altria Group on its earnings and payout profile, it can help to compare it with other income ideas built around established cash generators using the 7 dividend fortresses
Is Altria Group a Bargain on Earnings?
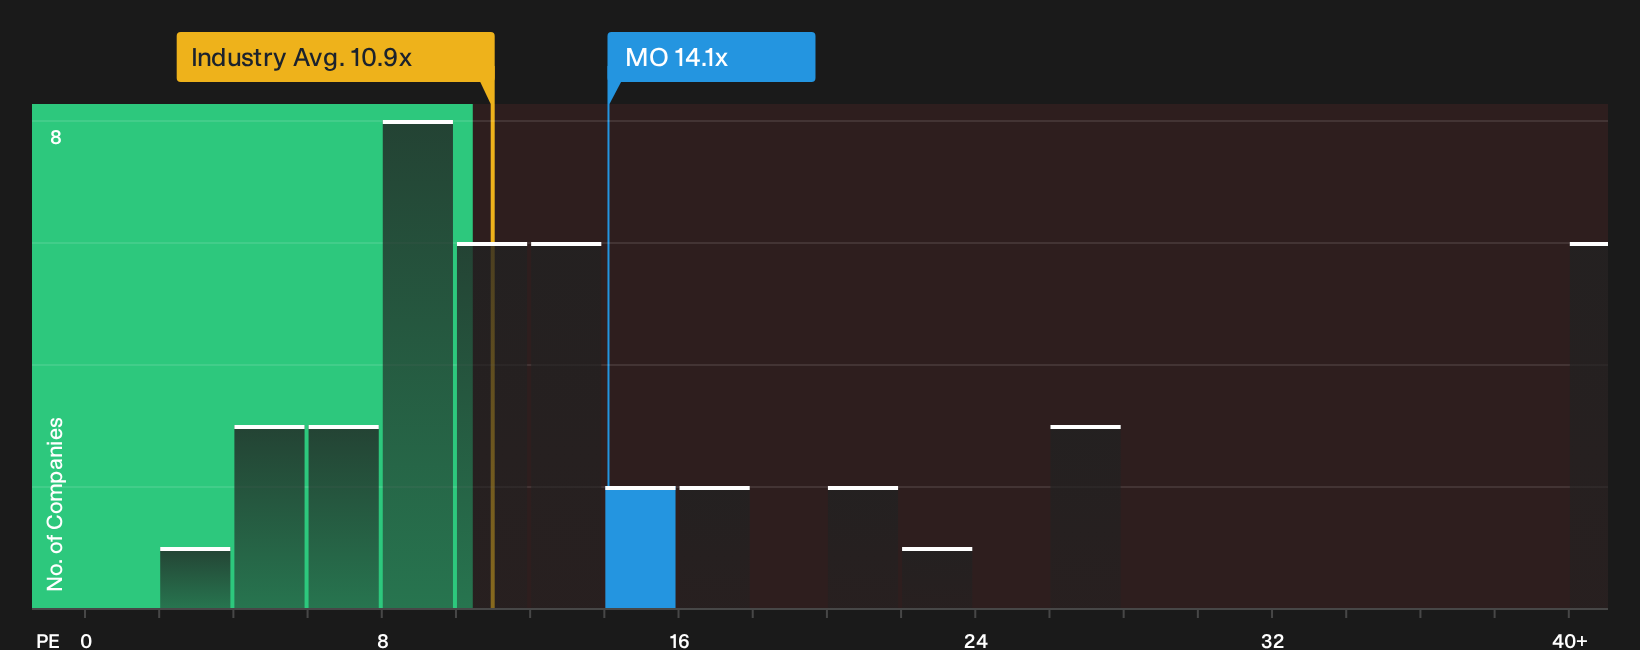
The P/E ratio is a useful fit for Altria Group because earnings remain the main anchor for how investors frame its value. On this measure, the stock currently trades on about 14.1x earnings. That is higher than the tobacco industry average of roughly 10.9x, so you are paying a richer multiple than the typical sector peer for each dollar of profit.
Compared with a broader peer group, where the average P/E is around 29.8x, Altria Group appears cheaper and does not carry the same headline valuation as faster rated consumer stocks. The in house fair value model, which adjusts the multiple for the company’s margins, risk profile and size, points to a higher ratio than the one on the screen today, so the shares appear undervalued against that benchmark. The gap suggests the market is asking you to factor in a cautious outlook before paying up for the cash flows on offer. Explore the numbers behind Altria Group's P/E valuation.
The Altria Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Altria Group leaves off and explain which assumptions on future growth, margins and earnings would need to hold for the current valuation to appear either too low or too demanding. Each scenario connects Altria Group's fair value to a particular combination of catalysts and risks, allowing you to track over time which storyline is closest to what the business is actually delivering.
The Altria Group community splits between those who see steady earnings and cash returns as enough and those who worry that smoke free execution and legal risk leave less room for error.
Bull case: roughly fairly valued
"Expansion of Altria Group's on! and on! PLUS nicotine pouch platform, with the category now close to 60% of oral tobacco volume…"
Discover why this Narrative puts Altria Group at roughly fairly valued.
Bear case: 16% overvalued
"Although Altria Group is expanding on! PLUS distribution and securing additional FDA marketing approvals for nicotine pouches, the oral tobacco products segment adjusted OCI fell 8% in Q2 2026…"
Explore why this Narrative puts Altria Group at 16% overvalued.
One more Altria Group check before you act
Before you lean too heavily on today’s multiples and payout history, it helps to see where professional forecasts expect Altria Group’s earnings and cash generation to land a few years from now. Explore where analysts expect Altria Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com