


What Aecon Group (TSX:ARE)'s Pickering Nuclear Contracts Mean For Shareholders
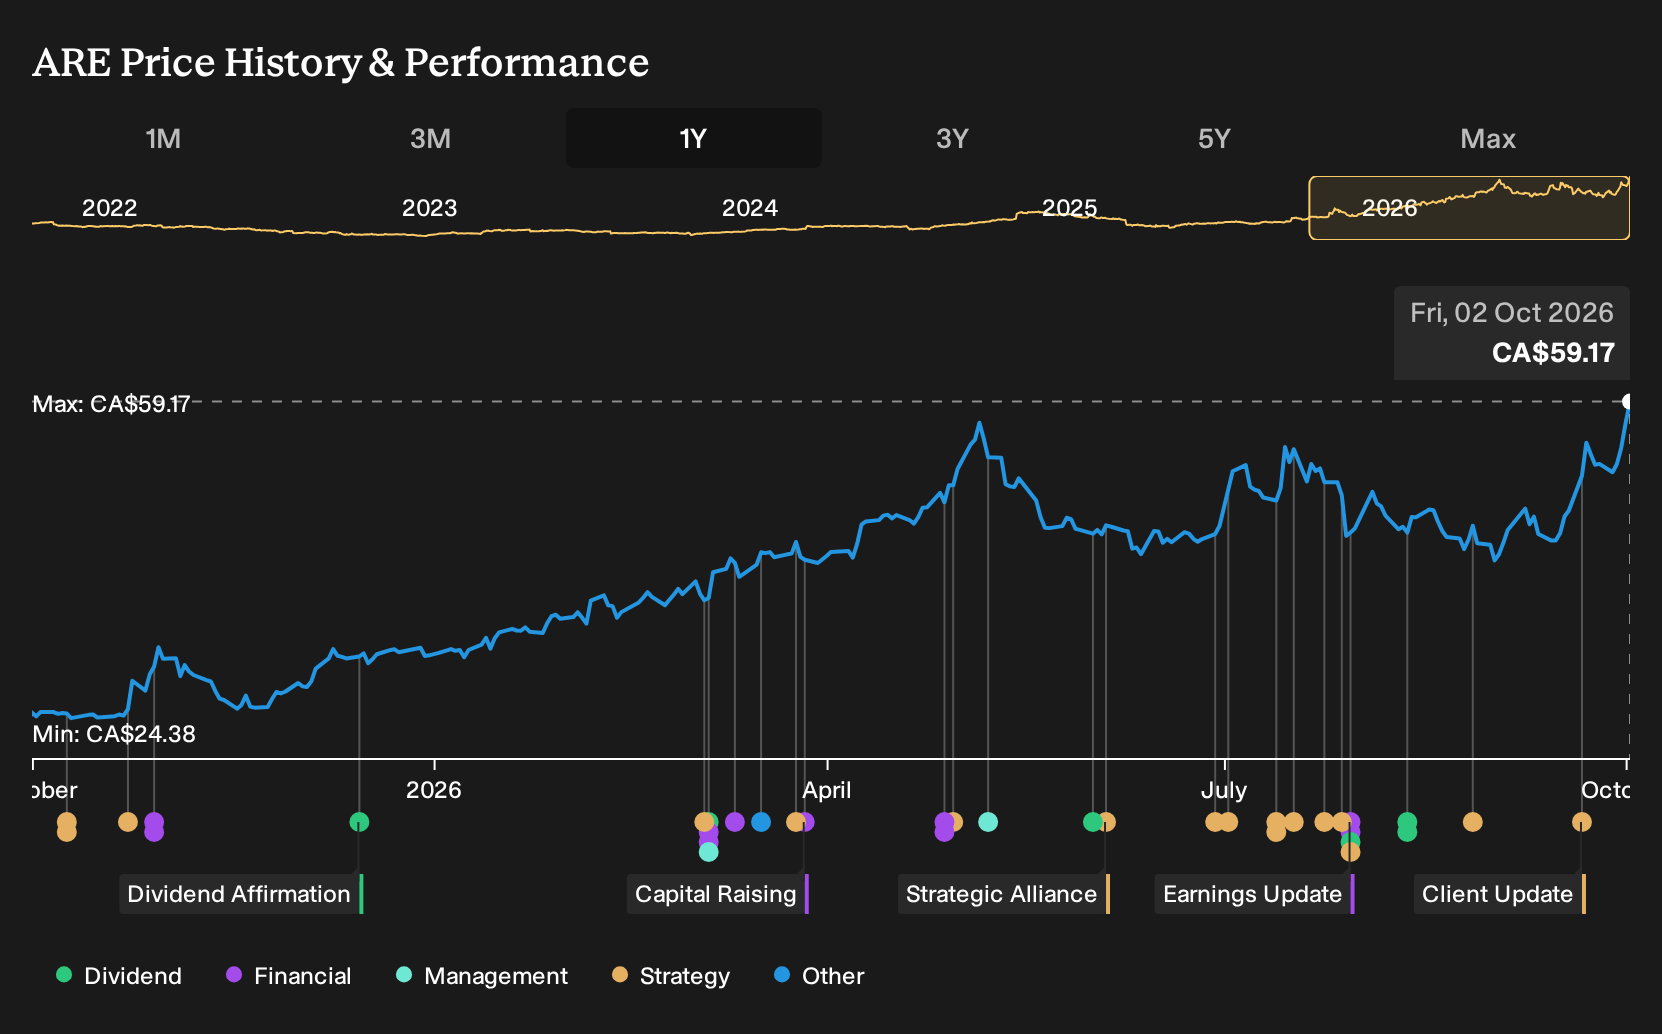
- Aecon Group reported that its joint venture with AtkinsRéalis and its consortium with Siemens Energy secured Ontario Power Generation contracts for the Pickering Nuclear Generating Station refurbishment. Aecon’s share of the C$3 billion in awards totals C$1.75 billion, which is expected to be added to its Construction segment backlog in Q3 2026.
- The Pickering work concentrates Aecon Group’s resources in a long-duration nuclear refurbishment program. This deepens its exposure to large clean energy infrastructure while committing the construction franchise to complex, regulated projects that can test execution discipline, labour planning and risk sharing over several years.
- We will now look at how Aecon Group's investment narrative could be influenced by this C$1.75 billion Pickering refurbishment backlog addition.
Scan beyond Aecon Group and see how other listed contractors are positioned for long-duration energy projects with the curated 19 nuclear energy infrastructure stocks.
Aecon Group Investment Narrative Recap
To own Aecon Group, you need to believe in a long runway of Canadian and North American infrastructure work, especially in energy transition, transportation and utilities, with enough pricing discipline to gradually rebuild margins. The Pickering refurbishment awards support that long-view thesis by extending visibility on complex nuclear work, but they do not resolve near term execution questions on their own.
Right now, the key near term swing factor is whether construction EBITDA margins, which management has already flagged as under pressure, can stabilize as collaborative contracts ramp. The biggest risk is that labour constraints, policy delays or contract structures keep squeezing profitability even as the backlog grows, limiting the benefit of headline contract wins like Pickering.
The Pickering Nuclear Generating Station refurbishment announcement is the clearest link to Aecon Group’s catalyst list. It directly plugs into the energy transition theme, adds C$1.75b to the Construction backlog in Q3 2026 and anchors multi year nuclear work that aligns with the firm’s focus on collaborative contracts and long duration infrastructure programs.
That scale cuts both ways for investors watching catalysts and risks. It deepens exposure to regulated, public sector energy projects, which can support revenue visibility but leave Aecon sensitive to policy shifts, labour availability and tight margin structures. Execution on this project set will likely shape how quickly analysts gain confidence in future earnings improvement and margin stability.
Aecon Group's analyst narrative points to CA$7.0b in revenue and CA$214.5m in earnings by 2029, based on expectations of 7.5% yearly revenue growth and an earnings increase of about CA$179m from current earnings of CA$35.2m.
Uncover why Aecon Group's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For Aecon Group, the most optimistic analysts leaned hard into the record C$10.7b backlog as a potential earnings engine. They were already pitching C$7.1b of revenue and C$183.4m of earnings by 2029, on a rich 36.1x P/E. Those forecasts came before the Pickering contracts, so your view may shift as this new work is incorporated into models.
Explore 3 other Aecon Group fair value estimates, including one that suggests it could be worth as much as CA$62.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Aecon Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Aecon Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aecon Group's overall financial health at a glance.
Looking for more investment ideas beyond Aecon Group?
Once you have a view on Aecon Group, it can help to widen the lens and compare it with other potential opportunities that match different risk and income profiles.
- For investors who care most about valuation support and business quality, take a look at companies flagged in the 6 high quality undervalued stocks that may offer stronger fundamentals relative to their prices.
- If capital preservation is front of mind, consider businesses highlighted in the 8 resilient stocks with low risk scores to see which stocks carry lower risk scores based on their financial and operating profile.
- For those hunting for resilient balance sheets and cleaner fundamentals, scan through the list of solid balance sheet and fundamentals (7 results) to compare how different companies stack up on debt, cash and core metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com