


ConocoPhillips (COP) Stock May Be Undervalued As Climate Case Focus Grows
ConocoPhillips has delivered a strong multi year run for shareholders. However, the latest pullback and fresh legal spotlight on oil producers raises a simple question for you as an investor: Is the current US$126.75 share price still in line with what the business is earning, or has the market pushed the stock beyond what its profit stream can reasonably support?
- Over the past 5 years the stock has returned 102.0%, so a lot of future earning power may already be reflected in the market value.
- Fresh attention on climate litigation, including the Supreme Court climate deception case that references ConocoPhillips through overlapping defendants, can influence how investors think about long term earnings resilience and potential legal or compliance costs.
- The analysts covering ConocoPhillips have run their own numbers. See what analysts think ConocoPhillips's shares could be worth.
The issue now is whether ConocoPhillips' recent price, after a 31.1% gain year to date and a 38.9% return over the past year, is adequately backed by its earnings when set against the Fair Ratio benchmark.
If you are comparing ConocoPhillips with other oil and energy opportunities while this climate litigation story unfolds, it may be useful to review it alongside 31 resilient stocks with low risk scores.
Is ConocoPhillips a Bargain on Earnings?
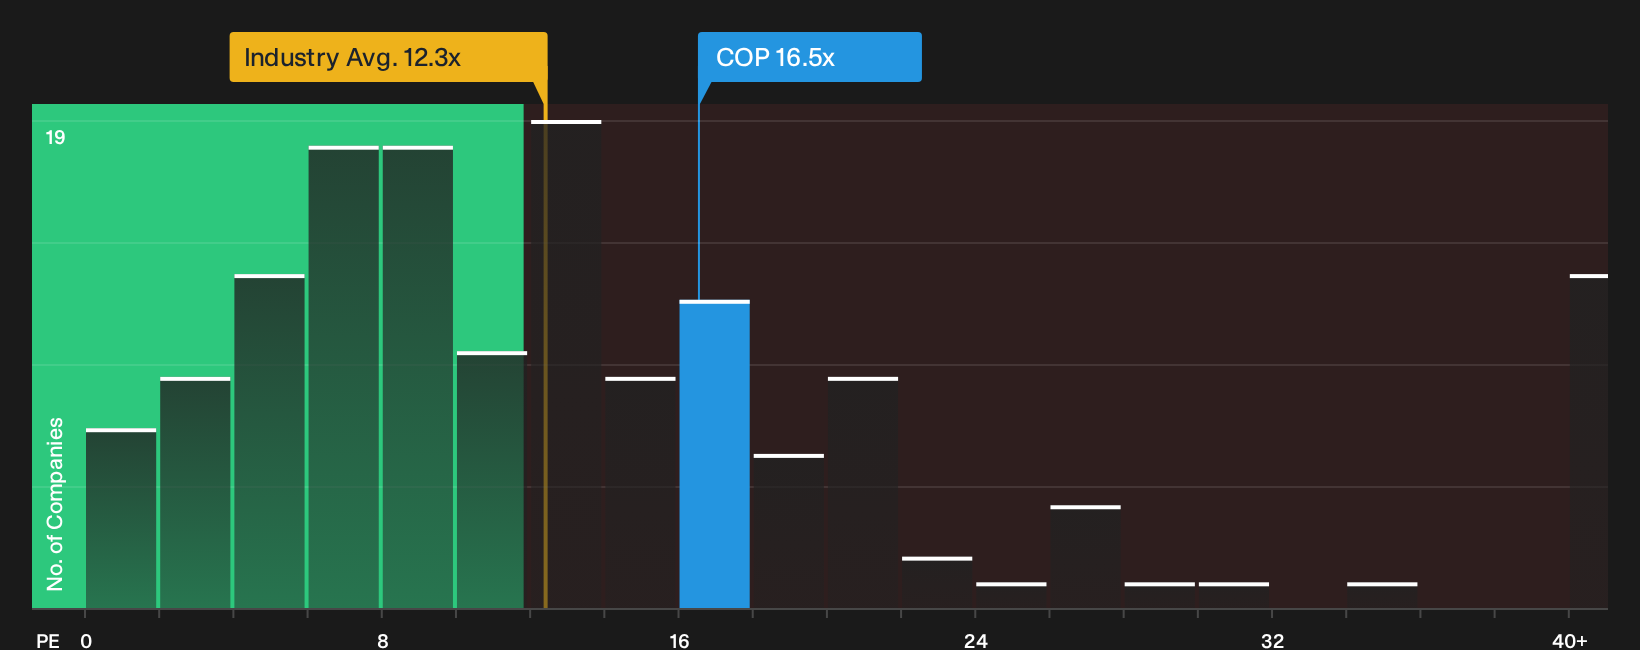
The P/E ratio is a useful shorthand for ConocoPhillips because earnings remain a primary driver of how investors value large, established producers. ConocoPhillips trades on a P/E of 16.5x, which is above the broader oil and gas industry average of 12.3x but below the peer group average of 18.2x. That places the stock in a middle ground where the market is asking for some earnings quality premium over the sector, without stretching to the valuations seen across closer peers.
Because the Fair Ratio model points to a higher P/E than today’s 16.5x, the current tag sits at a discount to what that framework would imply given ConocoPhillips’ size, profitability profile and risk mix. Despite the fresh Supreme Court attention on climate litigation involving overlapping oil producers, the multiple still prices ConocoPhillips at a lower earnings valuation than that tailored Fair Ratio benchmark would suggest. This gap is what the detailed valuation work behind the Fair Ratio is trying to flag for you. Explore the numbers behind ConocoPhillips's P/E valuation.
The ConocoPhillips Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the ConocoPhillips valuation puzzle leaves off by explaining what kind of future growth, margins, and earnings path would need to occur for the shares to be worth materially more or less than today’s price. Each narrative connects a fair value estimate to a clear storyline about ConocoPhillips' potential catalysts and pressure points, enabling you to track which scenario appears to be gaining traction over time on the Community page.
Community views on ConocoPhillips are split between those who see more upside from LNG and lower breakevens and those who think the stock already reflects a lot of that potential.
Bull case: 13% undervalued
"Global LNG market tightness, combined with ConocoPhillips securing 12 MTPA of LNG offtake and expecting first LNG from projects such as Port Arthur from 2027, points to a growing contribution from LNG marketing that could support higher revenue and cash flow than currently reflected in the stock..."
Discover why this Narrative puts ConocoPhillips at 13% undervalued.
Bear case: roughly fairly valued
"The plan to drive a $7b free cash flow inflection by 2029, including around $1b of incremental free cash flow per year from 2026 to 2028 and a further $4b from Willow, concentrates expectations on a narrow set of large projects..."
Explore why this Narrative puts ConocoPhillips at roughly fairly valued.
One last check for ConocoPhillips before you stop at the share price
Price multiples and scenarios tell part of the story, but the way professional analysts sketch out ConocoPhillips a few years from now offers a separate reference point that can either reinforce or challenge your own view. Explore where analysts expect ConocoPhillips to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com