


Atlassian (TEAM), What Is Behind The Fresh Attention?
Atlassian (TEAM) was removed from the FTSE All-World Index (USD) on 19 September 2026, a technical event that can force index-tracking funds to adjust positions without indicating any change in business fundamentals.
Recent trading shows that Atlassian’s share price has cooled in the very short term, with a 1-day share price return of a 1.06% decline. This follows a strong 90-day share price gain of 124.11% and a 1-year total shareholder return of 24.85%. However, the 5-year total shareholder return of a 51.91% decline signals that longer term holders have faced a much tougher journey.
Scan beyond Atlassian’s index removal and recent rally by comparing it with a curated 30 high quality undervalued stocks that share stronger balance sheets and cash flows.
Bulls point to Atlassian’s double digit revenue and billings growth, while bears circle the recent index exit and long term share price pain. Which side does the current valuation reward?
Most Popular Narrative: 6% Undervalued
Atlassian’s most followed valuation narrative pegs fair value at $199.23, a touch above the last close at $187.89, which puts the current price up against assumptions about how far cloud and AI execution can stretch earnings power.
Accelerating adoption of AI-powered features and investments in integrating AI deeply into Atlassian's core cloud platform are expanding differentiated use cases, leading to higher user engagement, greater value per customer, and increased opportunities for premium upsells, which in turn supports future revenue growth and margin expansion.
See why 119 investors see Atlassian as 6% undervalued.
Result: Fair Value of $199.23 (UNDERVALUED)
Still, Atlassian’s story can change quickly if complex cloud migrations stall or if heavy AI and product spending fails to translate into the earnings that underpin this narrative.
Find out about the key risks to this Atlassian narrative.
Another View On Atlassian’s Valuation
The first narrative relies on analyst targets and future earnings power for Atlassian. A different lens comes from the SWS DCF model, which values future cash flows and puts fair value at $172.02, below the current share price of $189.91, so the stock screens as overvalued on that framework.
The two approaches point in opposite directions, with the analyst-led view flagging a 6% discount to $199.23 and the cash flow model showing a premium to its estimate instead. As an investor, which anchor feels more useful: the sentiment and earnings multiple in the target, or the discipline of a cash flow driven number?
Look into how the SWS DCF model arrives at its fair value.
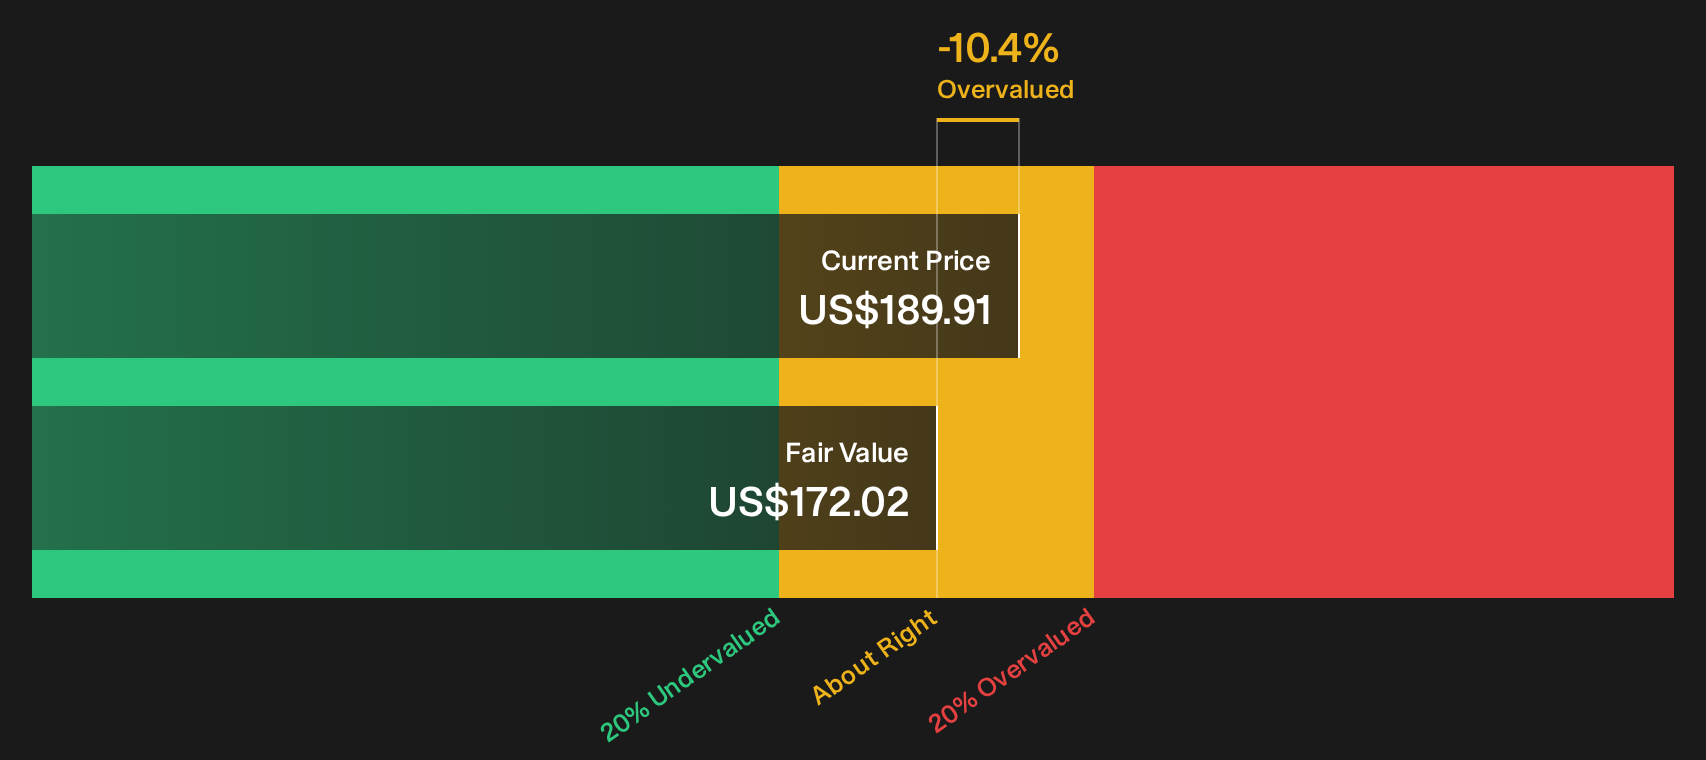
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Atlassian for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Atlassian can be confusing, so move quickly from headline noise to hard numbers and decide where you stand using 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Atlassian?
If Atlassian has sharpened your thinking, do not stop here. Widen your watchlist now and give yourself more quality options for the next decision.
- Target potential mispricing by scanning a curated pool of fundamentally strong companies through the 30 high quality undervalued stocks.
- Identify more dependable income candidates by focusing on companies in the 7 dividend fortresses.
- Reduce portfolio stress by concentrating on resilient businesses using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com