


Is Callaway Golf (CALY) Undervalued As Its Rebrand Resets The Valuation Debate?
Callaway Golf (CALY) recently reintroduced its legacy brand identity after operating as Topgolf Callaway Brands. This change is prompting investors to reassess how the golf equipment and apparel specialist’s mix of segments and geographies supports the current share price.
Recent trading tells a mixed story for Callaway Golf. The share price is down about 8% over the past month and about 21% over the last quarter, yet the year to date share price return sits at 23.29% and the 1 year total shareholder return is 45.67%. This points to longer term momentum that contrasts with the more cautious tone of recent weeks as investors digest the rebrand and reassess both growth potential and risk around the new structure.
Spot patterns in Callaway Golf’s recent swings and compare them with a hand picked group of resilient consumer names using the 31 resilient stocks with low risk scores.Callaway Golf has rebounded sharply over 1 and 3 years, yet the recent pullback and the fresh brand reset leave a simple tension: Is the bigger upside still ahead, or has most of it already passed?
Most Popular Narrative: 30% Undervalued
At a last close of $14.45, the most followed Callaway Golf narrative anchors on a fair value of $20.50, which points to a sizeable gap that the market has not closed yet. That view leans heavily on how the refocused golf equipment and apparel business is expected to translate recent execution into future earnings power.
Analysts expect earnings to reach $205.1 million (and earnings per share of $0.78) by about August 2029, up from $80.6 million today. In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 20.2x on those 2029 earnings, down from 42.3x today.
See why 16 investors see Callaway Golf as 30% undervalued.
Result: Fair Value of $20.50 (UNDERVALUED)
Still, Callaway Golf’s story can change quickly if discount-driven traffic at Topgolf undercuts profitability or if tariffs and softer international demand keep pressuring margins.
Find out about the key risks to this Callaway Golf narrative.
Another View On Callaway Golf’s Valuation
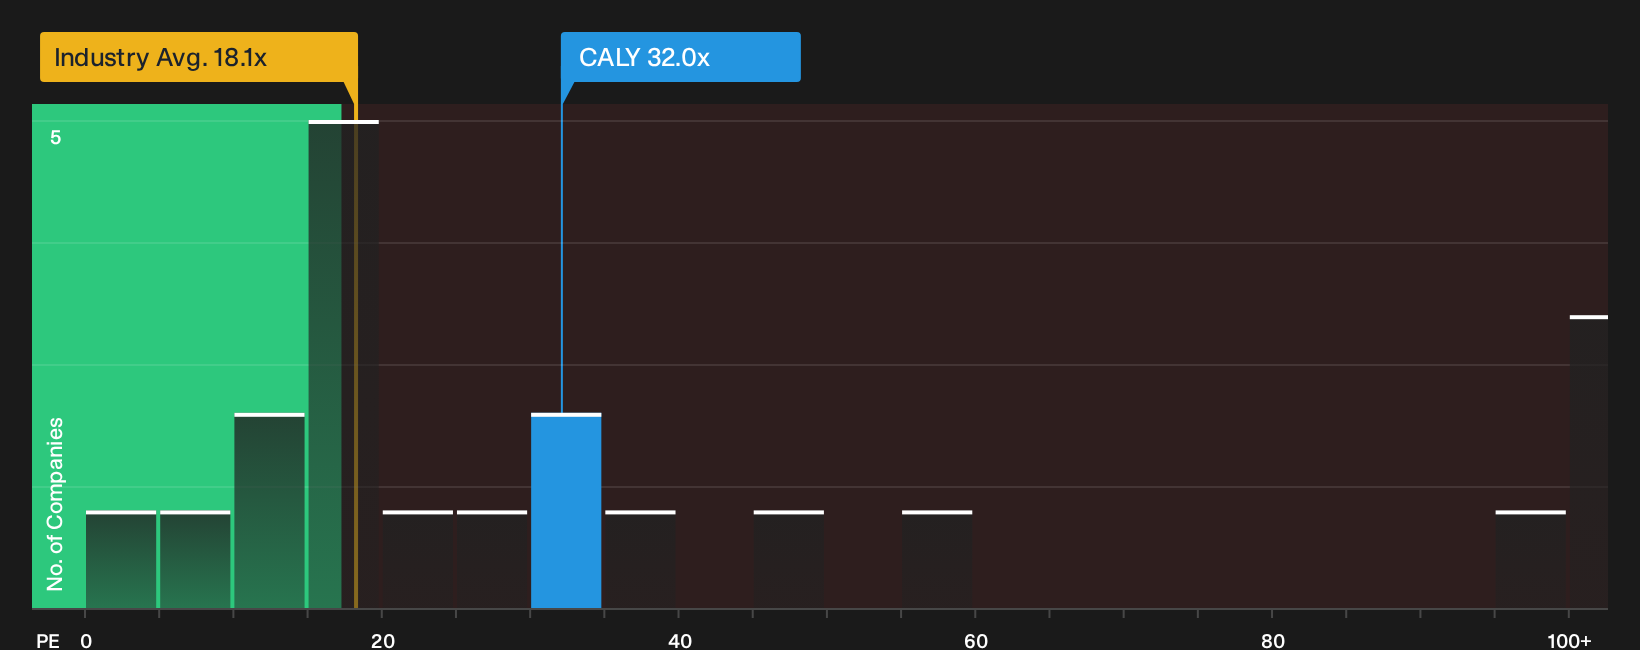
The first narrative around Callaway Golf leans heavily on earnings forecasts and a fair value of $20.50. A second lens tells a rougher story. On a P/E of about 32x, the shares trade above the peer average of 20.8x and above a fair ratio of 29.3x.
That gap points to valuation risk. The stock carries a richer multiple than both direct peers and the level the fair ratio suggests the market could gravitate toward over time. The question for you is simple. Does the growth narrative justify paying up now, or does it leave less room for error?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Callaway Golf only matter if you act on them. Take a closer look at both sides of the story with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Callaway Golf?
If Callaway Golf has you thinking harder about price, quality, and risk, use that momentum and widen your watchlist with a few targeted screeners.
- Target potential bargains by reviewing companies that pass strict quality checks and still trade at what looks like a discount using the 31 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with robust finances through the list of solid balance sheet and fundamentals (25 results).
- Hunt for under-the-radar opportunities before the crowd catches on by scanning the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com