


Arm Holdings (ARM) Gains AI Security Relevance, Is 32% Undervalued?
Arm Holdings (NasdaqGS:ARM) moved into the AI security spotlight after Nvidia selected Arm based Grace CPUs for its Sentry system, prompting fresh attention on how this design reach might influence investor expectations.
Recent trading tells a story of fast shifting expectations around Arm Holdings. The share price climbed about 24.5% over the past month but slipped roughly 7.3% over the last 90 days, while the year-to-date share price return of about 154.8% and 3-year total shareholder return of around 4.6x point to longer term momentum that recent pullbacks have only partially cooled.
Scan beyond Arm Holdings and find out which peers could be setting up the next phase of AI infrastructure demand with our hand picked 90 AI infrastructure stocks.
Bulls point to Arm Holdings' AI reach, revenue of about US$5.2b, and solid profitability. Bears focus on the sharp share price run and rich expectations. Which side does the current valuation lean toward?
Most Popular Narrative: 32% Undervalued
According to the most followed Arm Holdings narrative by HedgeY, the fair value of $430 sits well above the last close of $292.34, which puts the current market price in clear focus.
The catch is valuation. Arm is now being valued less like a normal semiconductor company and more like a future monopoly-like infrastructure layer for AI compute. The stock recently traded above $400 after a huge run, though it pulled back with the broader semiconductor selloff on July 13, when Arm fell 7.6% alongside other chip leaders.
See why 43 investors see Arm Holdings as 32% undervalued.
That framework implies Arm Holdings is trading at roughly a 32% discount to HedgeY's $430 fair value estimate, even after a year-to-date share price gain of about 154.8% and a 1-year total return of around 92.1%.
The same narrative leans heavily on Arm's long-term ambitions. These include management's targets for about $25b of annual revenue and roughly $9 of EPS, as well as an AGI CPU plan that aims for about $15b of yearly chip sales. For this view to hold, those goals need to stay credible enough for investors to keep paying a premium for Arm's AI architecture role despite current P/B metrics that screens describe as expensive relative to both the US semiconductor group and direct peers.
Arm Holdings already reports revenue of about $5.2b and net income of $1.0b, with net profit margins of 20.2% that are higher than last year and earnings growth over the past year of 49.4%, which is ahead of both its 5-year average of 24.8% per year and the wider semiconductor industry growth of 35.7%. Forecasts in the statements data flag expected revenue growth of 29.3% a year and earnings growth of 38.4% a year, both running faster than the broader US market, while return on equity is currently 12.1% and projected to rise to 28% in three years.
At the same time, the SWS DCF model output of $91.91 per share, which is well below the $292.34 market price, sits in clear contrast to the narrative fair value of $430. This shows how sensitive any valuation is to long-run assumptions about Arm's AI opportunity, margins, and discount rate. Analysts' average price target of $288.71 is also slightly below the current quote, which the statements data flags as a target that trails the market price rather than leading it.
There are quality markers that help explain why some investors still lean toward the higher narrative fair value. These include high quality earnings, profit growth that has accelerated, and earnings that are expected to grow significantly over the next three years, while management and the board are both described as experienced. On the risk side, Arm Holdings carries a value score of 0, trades above the internal future cash flow estimate, relies entirely on higher risk funding sources rather than customer deposits, and has CEO compensation and a recent pay increase that sit well above the US market average for similar sized businesses.
Result: Fair Value of $430 (UNDERVALUED)
Still, Arm Holdings faces clear pressure points, including potential FTC antitrust action and possible strain with key customers if AGI CPU ambitions clash with its long-standing neutrality.
Find out about the key risks to this Arm Holdings narrative.
Another View on Arm Holdings Valuation
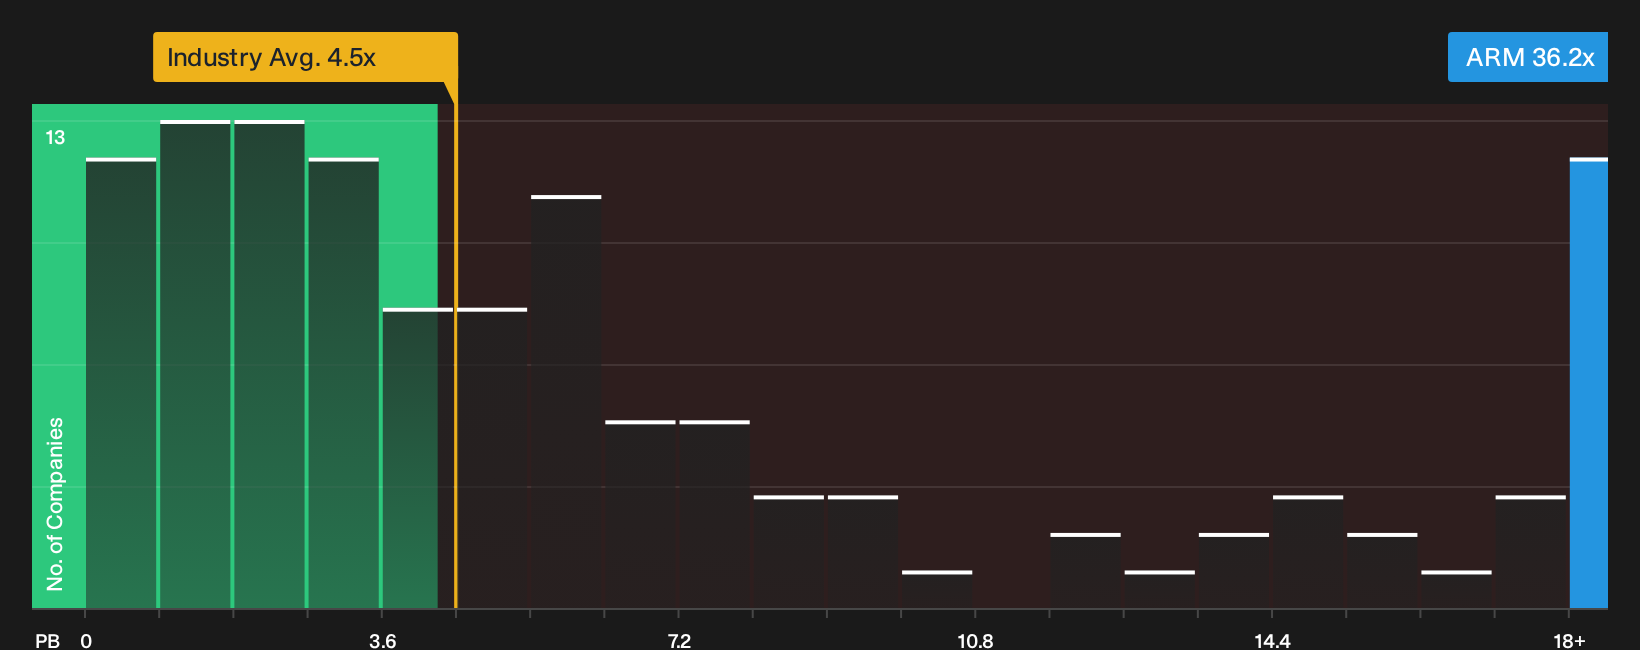
The first narrative leans on Arm Holdings reaching about $25b of revenue and roughly $9 of EPS. The preferred multiple data tell a different story. Arm trades at a P/B of 36.2x versus 4.5x for the US semiconductor sector and 10x for peers, which points to a rich valuation rather than a discount.
That kind of gap means a lot of future success is already reflected in the share price. The key question is whether you see this as justified confidence or valuation risk if the long term plan slips even slightly.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Arm Holdings after all this, or leaning one way already but want to stress test that instinct quickly and on your own terms? Start by reviewing the 2 key rewards and 1 important warning sign.
Looking for more Arm Holdings investment ideas?
If Arm Holdings has your attention, do not stop here. Fresh opportunities sit one screener away, and waiting too long can mean watching others move first.
- Target resilient potential by scanning a 31 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles.
- Spot potential value by reviewing a 28 high quality undervalued stocks that highlights companies with strong fundamentals priced below what many investors might expect.
- Find future contenders by checking a 19 high quality undiscovered gems that surfaces quality stocks still flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com