


Woodward (WWD) Reshapes Manufacturing Footprint As Valuation Upside Stays In Focus
Woodward (WWD) has begun a major manufacturing reshuffle, shifting flight control actuation work from its Santa Clarita site to a new aerospace campus in Spartanburg, South Carolina.
The restructuring news comes after a mixed stretch for Woodward’s shares. The 1-day share price return of 2.31% and 7-day gain of 3.16% contrast with a 90-day share price decline of 19.58%, while the 1-year total shareholder return of 32.65% and 3-year total shareholder return above 170% indicate strong longer term momentum.
Capitalize on Woodward's manufacturing shake-up by scanning a curated group of industrial and aerospace peers through our 19 high quality undiscovered gems for potential under-the-radar opportunities.Bulls see Woodward sharpening a focused aerospace platform around Spartanburg, while bears worry about execution risk and a rich share price. Which story does the current valuation actually support?
Most Popular Narrative: 23% Undervalued
The most followed valuation story on Woodward pegs fair value at $437.08 versus a last close of $336.19, which puts the current share price at a clear discount according to that framework. That gap only really makes sense if you think the manufacturing revamp, aftermarket mix, and capital returns can support the earnings path laid out in the thesis.
Woodward's content on LEAP and GTF engines, together with aftermarket services where repair and spare LRU revenue is already comparable to legacy narrow body levels and repair volumes are expected to cross over between late fiscal 2026 and 2027, points to further growth in commercial aerospace revenue and earnings as newer fleets mature into heavier service cycles.
See why 11 investors see Woodward as 23% undervalued.
Result: Fair Value of $437.08 (UNDERVALUED)
Still, Woodward’s heavy manufacturing build out and higher working capital needs could restrain free cash flow and weaken support for the current valuation story.
Find out about the key risks to this Woodward narrative.
Another View: Woodward Through The P/E Lens
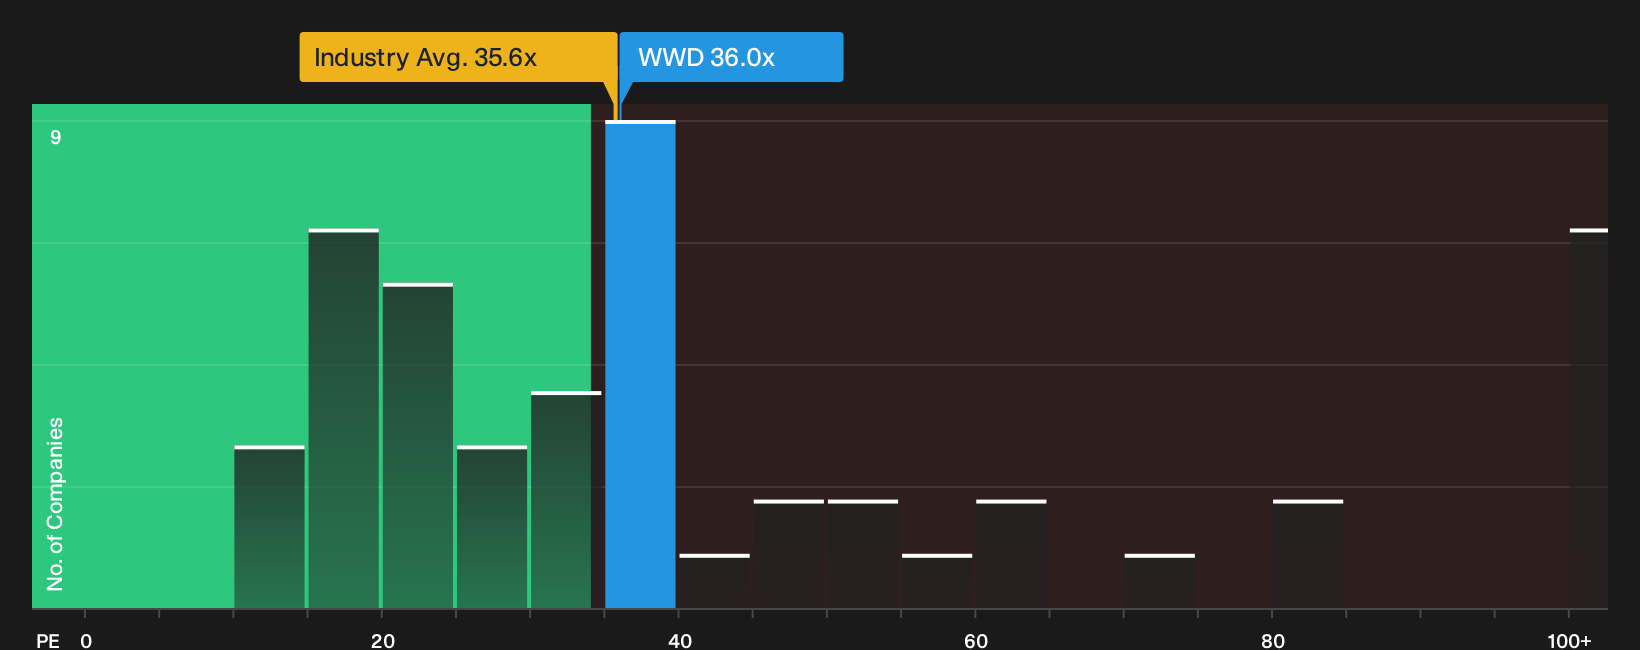
Woodward looks cheap on one metric and stretched on another. The stock trades on a P/E of 36x, slightly above the US Aerospace & Defense average of 35.3x, yet well below a peer average of 71.9x and above a fair ratio of 26.2x that the market could move toward. Is that gap a safety margin or a pricing risk if expectations cool?
To see how the earnings multiple compares with the underlying business, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether the optimism in this Woodward story matches your own instincts? Move fast, review the upside case in detail, and weigh the 4 key rewards.
Looking For More Investment Ideas Beyond Woodward?
If Woodward has sharpened your focus on quality, broaden your watchlist with a few carefully filtered ideas that could reshape how you think about your portfolio.
- Target resilient balance sheets and fundamentals that aim to weather tougher cycles by scanning our list of solid balance sheet and fundamentals (25 results).
- Spot potential mispricings where quality and valuation intersect by reviewing the 28 high quality undervalued stocks.
- Hunt for overlooked potential before the crowd catches on by working through the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com