


QBE Insurance Group (ASX:QBE) Shares Look 33% Overvalued As It Names New Regional CEO
QBE Insurance Group (ASX:QBE) has moved its leadership pieces again, appointing long-time executive Jonathan Groves as Chief Executive Officer for Australia Pacific, effective 1 November 2026, subject to regulatory approvals.
For investors watching QBE Insurance Group, the leadership change lands at a time when the share price is A$23.81 and short term momentum is positive, with a 7 day share price return of 3.84% and a 30 day share price return of 4.61%. However, the 90 day share price return has fallen 4.11%. Longer term performance is reflected in a 1 year total shareholder return of 20.49% and a 5 year total shareholder return of 136.36%, suggesting recent trading is building on an already strong multi year run.
Scan how QBE Insurance Group compares with other insurers showing strong price action and fundamentals using our curated list of solid balance sheet and fundamentals (12 results) as a starting point.
Fresh leadership in Australia Pacific, a strong multi year share run, and a recent dip over 90 days put QBE Insurance Group at an interesting crossroads. Is it worth stepping in now, or waiting for a cheaper entry?
Most Popular Narrative: 33% Overvalued
On Simply Wall St's most followed narrative, QBE Insurance Group screens as materially overvalued, with a Fair Value of A$17.89 against the last close at A$23.81, even after factoring in a 7.18% discount rate to future cash flows and earnings.
Dependence on supportive commercial P&C pricing conditions and facility based distribution for QBE Re and portfolio solutions means any broad softening in rate adequacy or facility economics could limit the ability to recycle capital at attractive returns. This could put pressure on revenue growth and profitability targets.
See why 2 investors see QBE Insurance Group as 33% overvalued.
Result: Fair Value of A$17.89 (OVERVALUED)
Still, if QBE Insurance Group sustains near 20% ROE with expense ratios trending lower, stronger earnings resilience could challenge the view of current overvaluation.
Find out about the key risks to this QBE Insurance Group narrative.
Another Angle On QBE Insurance Group's Valuation
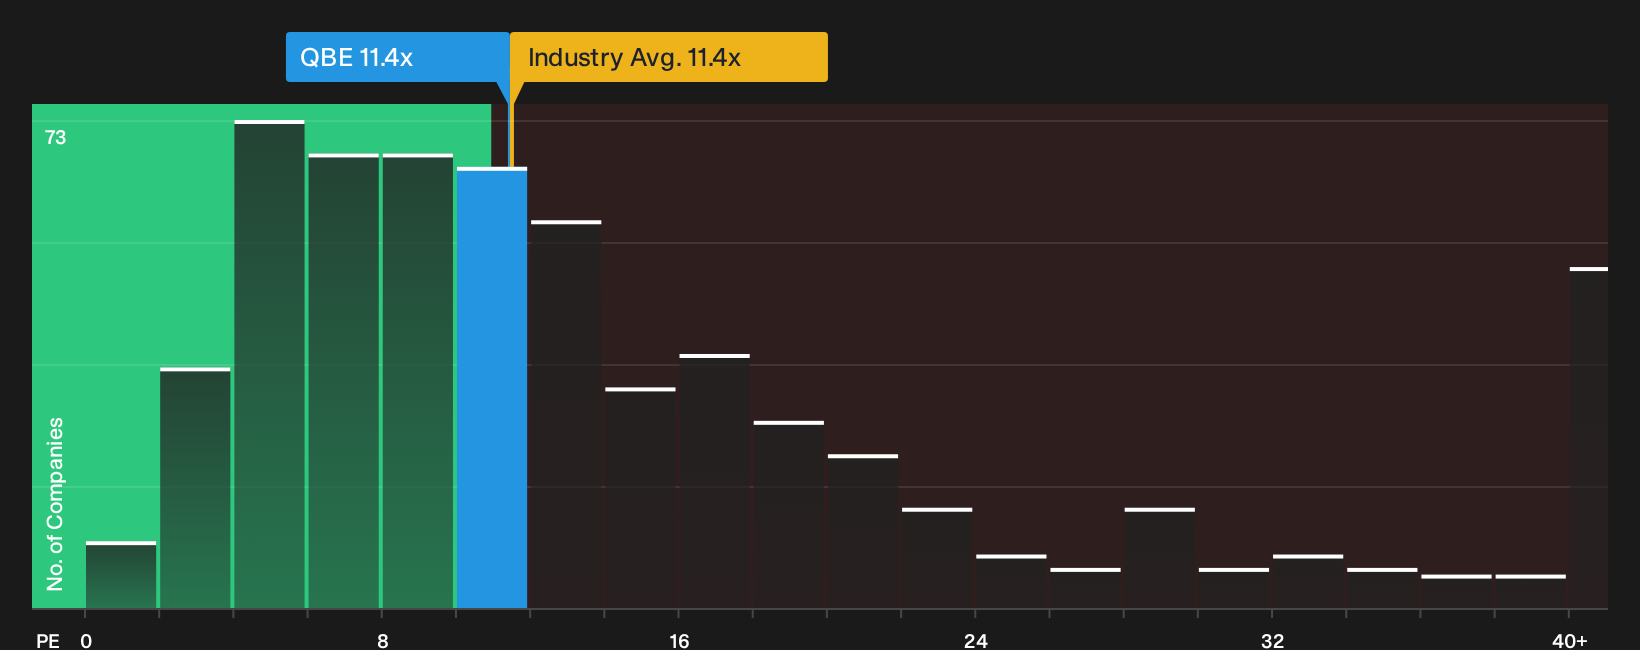
The first narrative paints QBE Insurance Group as overvalued at A$23.81 versus a A$17.89 fair value built from bearish earnings forecasts. Yet on a simple P/E lens, the stock trades at 11.4x, in line with the global insurance average of 11.4x, and well below a fair ratio of 19.2x. If the market ever drifts closer to that fair ratio, today’s pricing could look less stretched. The question is which reference point you place more weight on.
For a closer look at what the P/E gap versus peers and the fair ratio implies in practice for valuation risk or opportunity, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like QBE Insurance Group's can tempt you to lean too hard in one direction. Move quickly, review the full picture, and weigh both the upside potential and the downside flags in the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond QBE Insurance Group?
If QBE Insurance Group has your attention, do not stop there. Broaden your opportunity set and pressure test your thinking with a few targeted screens.
- Target potential value opportunities before they move by scanning our curated 5 high quality undervalued stocks.
- Prioritise resilience and sleep-at-night holdings using a focused list of 7 resilient stocks with low risk scores.
- Hunt for overlooked quality and fresh ideas by tracking 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com