


Keyrus (ENXTPA:ALKEY) Stock Faces Profit Squeeze As Losses Deepen
Keyrus enters this earnings season with the stock under pressure, down roughly 9% over three months, and still closing at €7.74. The headline is not the top line; the story is the profit squeeze. H1 2026 revenue held at about €170.8m, yet the company slipped into a small loss and the trailing twelve months now show net income in the red at about €8.5m. Short term sentiment reacts to that pain. Over the longer term, investors need to weigh those shrinking profits against a low P/S multiple and a balance sheet carrying strained cash flow coverage of debt.
Concerned that Keyrus combines a low P/S tag with shrinking profits and weak cash flow support for its debt? Compare that setup with our list of solid balance sheet and fundamentals stocks (206 results).
H1 2026 Earnings Summary
- Revenue (H1 2026 vs. H1 2025): €170.8m vs. €170.2m (broadly flat top line)
- Net Income/Loss (H1 2026 vs. H1 2025): loss of €0.02m vs. profit of €11.7m (swing into loss)
- Basic EPS (H2 2025 vs. H1 2025, latest available): loss of €0.54 per share vs. earnings of €0.73 per share (moved from profit to loss over the most recent halves reported)
- Trailing Twelve Month Net Income (H1 2026 TTM vs. H1 2025 TTM): loss of €8.5m vs. profit of €14.8m (turned from profit into a material loss over 12 months)
Prefer clean charts over marathon sessions with spreadsheets and raw earnings tables? See the full financial picture of Keyrus, including a visual breakdown of its valuation and recent profit swing, inside our company report for Keyrus.
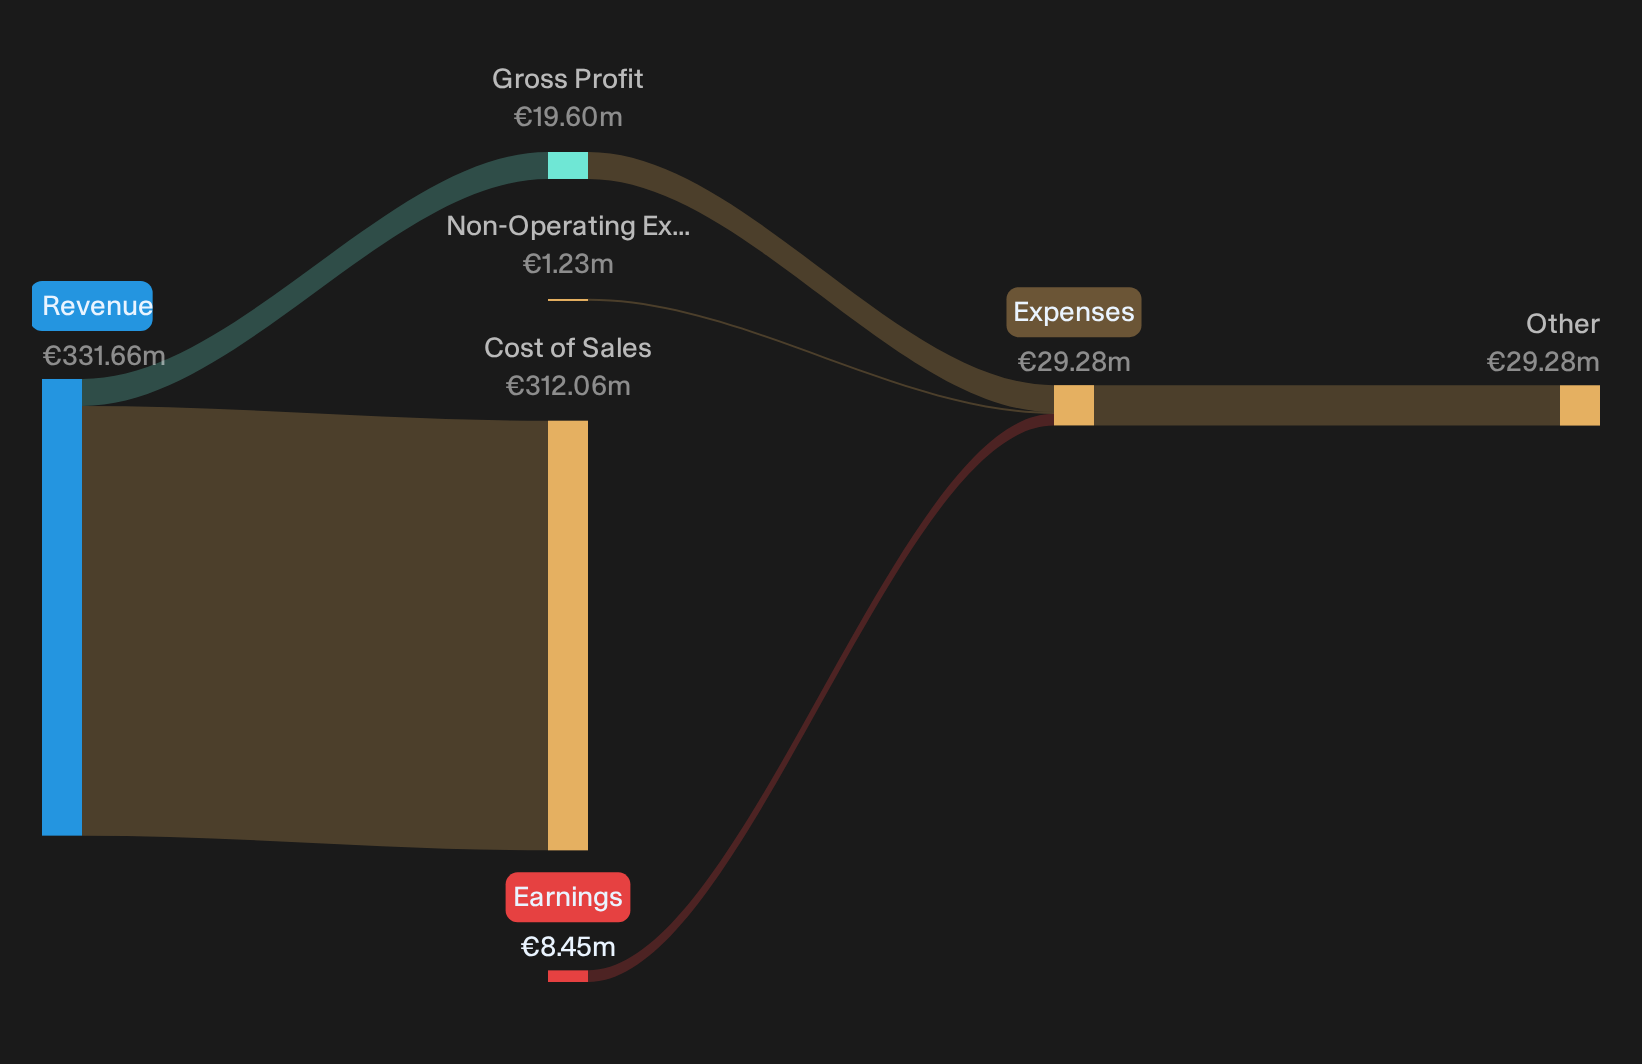
Keyrus bull case meets profit reality
For anyone leaning bullish on Keyrus as a specialist in data and AI work, the latest figures cut both ways. Revenue near €170.8m and broadly stable year on year suggests clients have not walked away from the consulting proposition. That supports the idea of a relevant offering. The problem is that this activity no longer converts into profit, with a tiny loss in H1 2026 and a €8.5m trailing loss. Any optimistic view now hinges on whether management can restore earnings without sacrificing that steady top line.
Bearish concerns backed by shrinking earnings
The darker narrative around Keyrus finds clearer support in these numbers. There is a swing from an €11.7m H1 2025 profit to a marginal loss in H1 2026 while trailing twelve month earnings also move into the red. That is a meaningful compression in profitability for a services group that relies on utilisation and pricing discipline. With three month, one month and one week returns all declining, equity holders already price in some of this strain. The latest earnings do more to validate those worries than to calm them.
Expose whether Keyrus’ shrinking earnings and weak debt coverage are isolated issues or part of deeper structural problems. Review our risk analysis for Keyrus which shows 2 important warning signsTake Control Of Your Next Move
If Keyrus’ profit squeeze and weak cash flow support for its debt have your attention, register for free with Simply Wall St and add it to a Watchlist to track the share price against fair value and watch for a more attractive entry point. After you decide to build a position, keep your decisions focused with a Portfolio Command Center that highlights only the most important developments for your holdings. For longer term investors, a vibrant Community helps you see how other shareholders are interpreting the same numbers and events. By spotting potential catalysts and emerging risks early, you give yourself a better chance of staying ahead of the broader market conversation.
Seeking Alternatives Before Momentum Flies Past?
Fresh breakout stories rarely stay quiet for long. Momentum shifts fast, and once the crowd piles in, the best entry points can move quickly. Scan the next wave early and consider potential opportunities ahead of time.
- Identify ideas that appear more resilient when conditions change by reviewing our curated 228 resilient stocks with low risk scores before others start paying attention.
- Explore stronger income potential while yields still look appealing by checking a filtered set of 169 dividend fortresses that currently remain under the radar.
- Follow the AI build out while capital is still rotating by scanning a focused basket of 90 AI infrastructure stocks before valuations change further.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com