


Kroger (KR) Stock Looks About Right With Earnings In Focus
Kroger has delivered strong five year gains for shareholders, yet recent share price softness and slower same store sales growth leave a clear question for you as an investor. Is the current US$59.48 share price still adequately grounded in the supermarket group's earnings power, or has sentiment moved ahead of what the business is generating today?
- The stock has returned 67.8% over the past 5 years, which puts meaningful long term gains on the line if the earnings story and the current valuation grow apart.
- New initiatives such as the Kroger Rewards Elite Mastercard and a broader AI program may support expectations for future profitability if they improve customer loyalty, spending and operational efficiency.
- There is a second opinion on Kroger worth weighing. See what analysts think Kroger's shares could be worth.
The issue now is whether Kroger's current earnings, and the outlook implied by them, are strong enough to justify where the shares trade today.
If you are weighing Kroger's recent AI and payments moves against its slower same store sales, it can help to see how other retailers with tech exposure are priced by scanning 38 AI small caps.
Where Does Kroger Sit on Earnings?
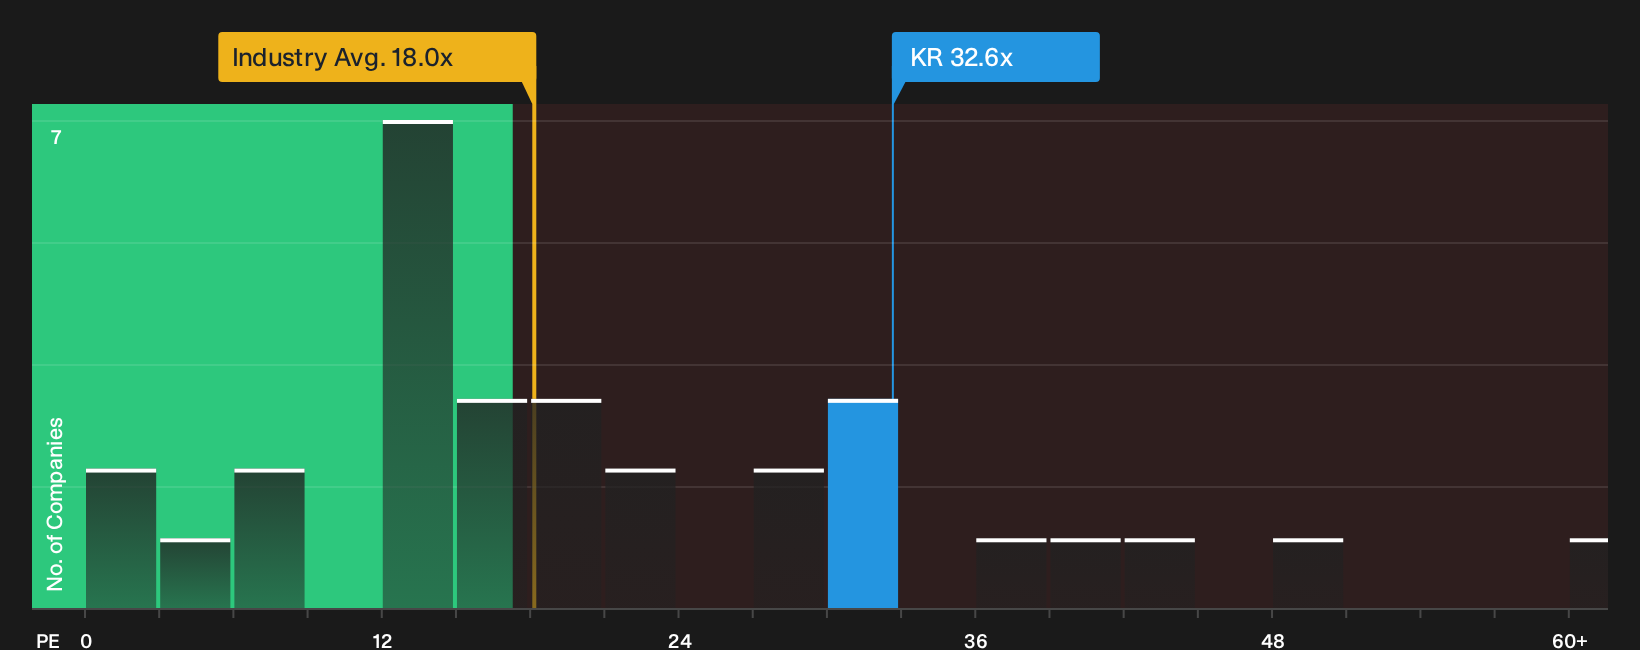
The P/E ratio suits Kroger because earnings still sit at the center of how investors judge a mature supermarket group. At a current P/E of 32.6x, Kroger trades below the 37.4x peer average in Consumer Retailing, yet well above the broader industry P/E of 18.0x. That mix suggests the shares carry a clear premium to the typical retailer, while still pricing in less optimism than some tech leaning or higher growth peers.
The fair P/E level implied by the tailored model sits close to where Kroger trades today, so the stock screens about right rather than plainly cheap or expensive on earnings alone. Because the new AI and payments push, including the Kroger Rewards Elite Mastercard, gives the story a more tech enabled angle, the current multiple already reflects some expectation that these programs support future profitability. The question for you is whether slower comparable store sales leave enough earnings momentum to keep justifying a P/E in the low 30s, or whether you would want a clearer margin or growth payoff before paying this kind of earnings multiple. Explore the numbers behind Kroger's P/E valuation.
The Kroger Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Kroger pick up where the valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to play out for the stock to be worth materially more or less than today’s price. Each one treats Kroger's implied fair value as a thesis you can watch over time rather than a single frozen estimate, all gathered on the Community page.
Community views on Kroger are split between those who see more upside in the current plan and those who think expectations already look full.
Bull case: 13% undervalued
"Aggressive cost optimization efforts, including further supply chain automation and adoption of AI and data analytics for shrink reduction, are expected to enhance operational efficiency…"
Discover why this Narrative puts Kroger at 13% undervalued.
Bear case: roughly fairly valued
"Although Kroger is seeing strong growth in e-commerce and has reached profitability in this channel, continued higher transportation and fuel costs could limit how much of this progress flows through to net margins and earnings…"
Explore why this Narrative puts Kroger at roughly fairly valued.
An open question on Kroger that pure valuation work cannot answer
Price multiples tell only part of the Kroger story, because the checks behind this analysis have also flagged firm specific concerns that investors may want to weigh carefully before leaning on the current share price. Take a closer look at 4 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com