


Boeing (BA) Stock Looks In Line With Earnings Despite Navy Fighter Win
Boeing has been under pressure in 2026, with the stock weaker and investors weighing a string of contract wins against ongoing operational questions. That mix puts the spotlight squarely on one issue for you as a shareholder or potential buyer: whether the current share price near US$192 is well supported by the aircraft maker's earnings power.
- The share price has fallen 15.6% year to date, which raises the question of whether the market is marking earnings expectations down too far or simply aligning more closely with what the business is currently generating.
- Fresh long term deals, from the U.S. Navy's F/A XX fighter program to large commercial orders with airlines such as Turkish Airlines and Ethiopian Airlines, can influence how you think about future profit margins and the timing of cash flows that underpin any earnings based valuation.
- Your read on Boeing is one view; the desks covering it have another. See what analysts think Boeing's shares could be worth.
The stock's next move may depend on whether Boeing's earnings, and what investors are willing to pay for them, genuinely support the current share price after this year's decline.
If you want to compare Boeing's earnings with other opportunities, scan a wider field of 28 high quality undervalued stocks.
Does Boeing Look Fairly Valued on Earnings?
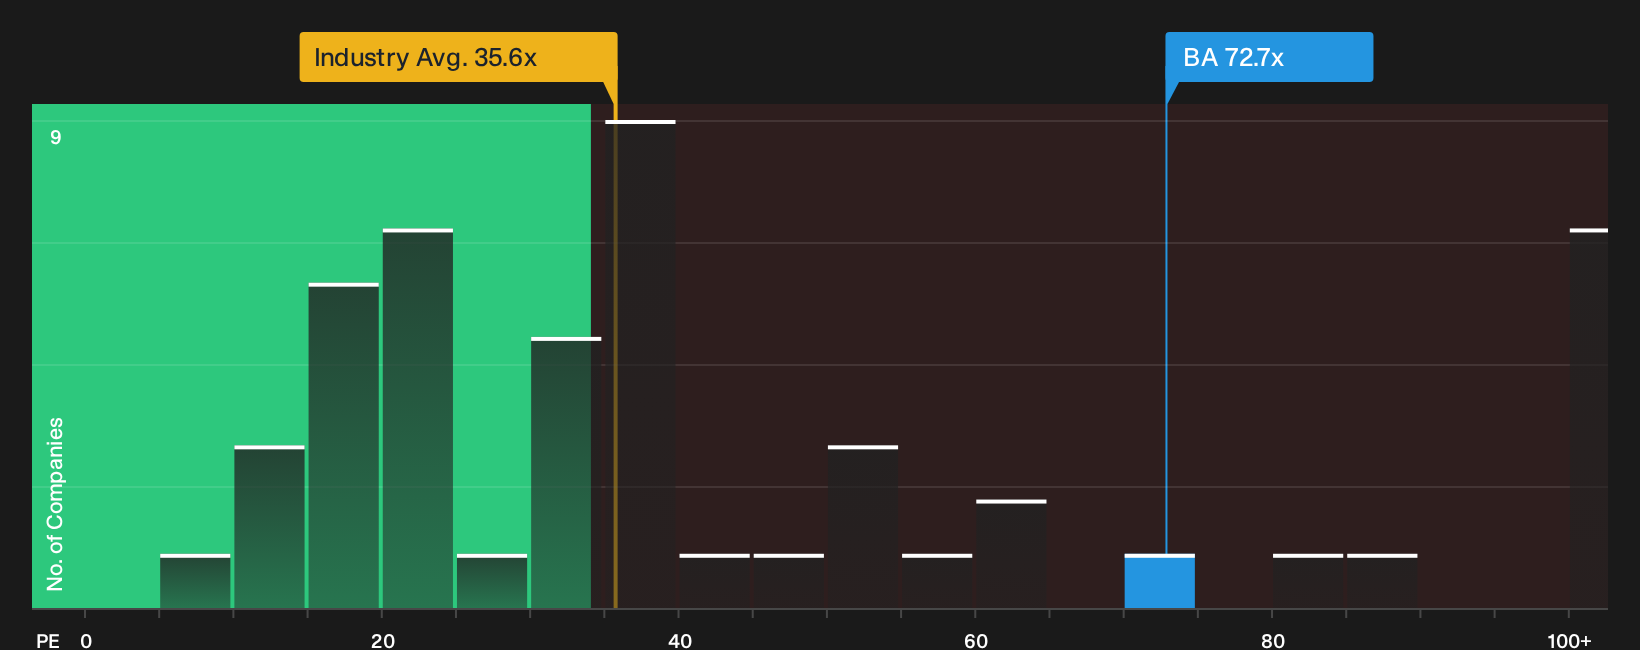
The P/E ratio is a suitable measure for Boeing because earnings are the core yardstick most investors use for large industrial groups with long order books. At a P/E of about 72.7x, the stock trades at roughly double the Aerospace & Defense industry average of 35.6x and also well above the peer set on roughly 29.9x. Compared with a tailored fair multiple that blends Boeing's growth profile, margin structure, size and risk, the current P/E appears to be in a reasonable range rather than signaling a clear bargain or bubble.
Because the F/A XX fighter award and large commercial orders with Turkish Airlines and Ethiopian Airlines add visible workstreams, the market is assigning a full earnings multiple that already incorporates those contracts to a meaningful degree. For your decision, the key issue is whether Boeing's future profit quality and execution justify paying this kind of premium P/E versus the rest of the sector and similar stocks. Explore the numbers behind Boeing's P/E valuation.
The Boeing Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Boeing's valuation puzzle leaves off by spelling out the earnings, margin and growth paths that would need to play out for the stock to be worth far more or meaningfully less than today on the Community page. Rather than a single P/E or model output, each narrative sets out the assumptions sitting underneath its view of fair value so you can track those against Boeing's reported results over time.
Community investors looking at Boeing see the same order book and debt load, but they draw very different conclusions about what that mix is worth.
Bull case: 36% undervalued
"Boeing's vast $522 billion commercial backlog, with 5,900 aircraft sold firm into the next decade, positions the company to disproportionately benefit from the expected doubling of global air travel demand by 2040..."
Discover why this Narrative puts Boeing at 36% undervalued.
Bear case: 20% overvalued
"Boeing's operations made money in the quarter, every dollar of the loss, and more, came from servicing debt..."
Explore why this Narrative puts Boeing at 20% overvalued.
The Boeing share price is only one piece of your decision
Boeing's valuation tells only part of the story, because internal checks have flagged specific areas of concern that some investors may want to weigh carefully before committing fresh capital. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com