


Will Award Wins Change Graham Holdings (GHC) Narrative
- Graham Holdings subsidiary Code3 recently received the 2026 Amazon Ads Partner Award for Programmatic Optimization and swept all three Meta Agency Awards it was nominated for, recognizing its work with Nordic Naturals, Feastables and Christian Dior Couture.
- This cluster of marketing awards puts fresh attention on Code3 as a contributor to Graham Holdings' digital advertising capabilities across commerce, media and creative services.
- Attention now turns to how Graham Holdings' investment narrative could be influenced by Code3's industry recognition for programmatic and social campaign performance.
Scan how Graham Holdings compares with other digital advertising and media driven businesses by reviewing the curated 19 high quality undiscovered gems that are already attracting attention for their fundamentals.
What Is Graham Holdings' Investment Narrative?
To own Graham Holdings, you need to be comfortable with a sprawling, old school conglomerate that leans on disciplined management more than any single growth story. The core belief is that solid operators can compound value over time across education, media, healthcare, manufacturing and a grab bag of smaller services, even if headline growth is relatively modest. Code3’s recent Amazon and Meta awards fit that belief. They highlight that at least one of the newer digital marketing assets can win work and mindshare, but they are small against roughly US$5.1b of revenue.
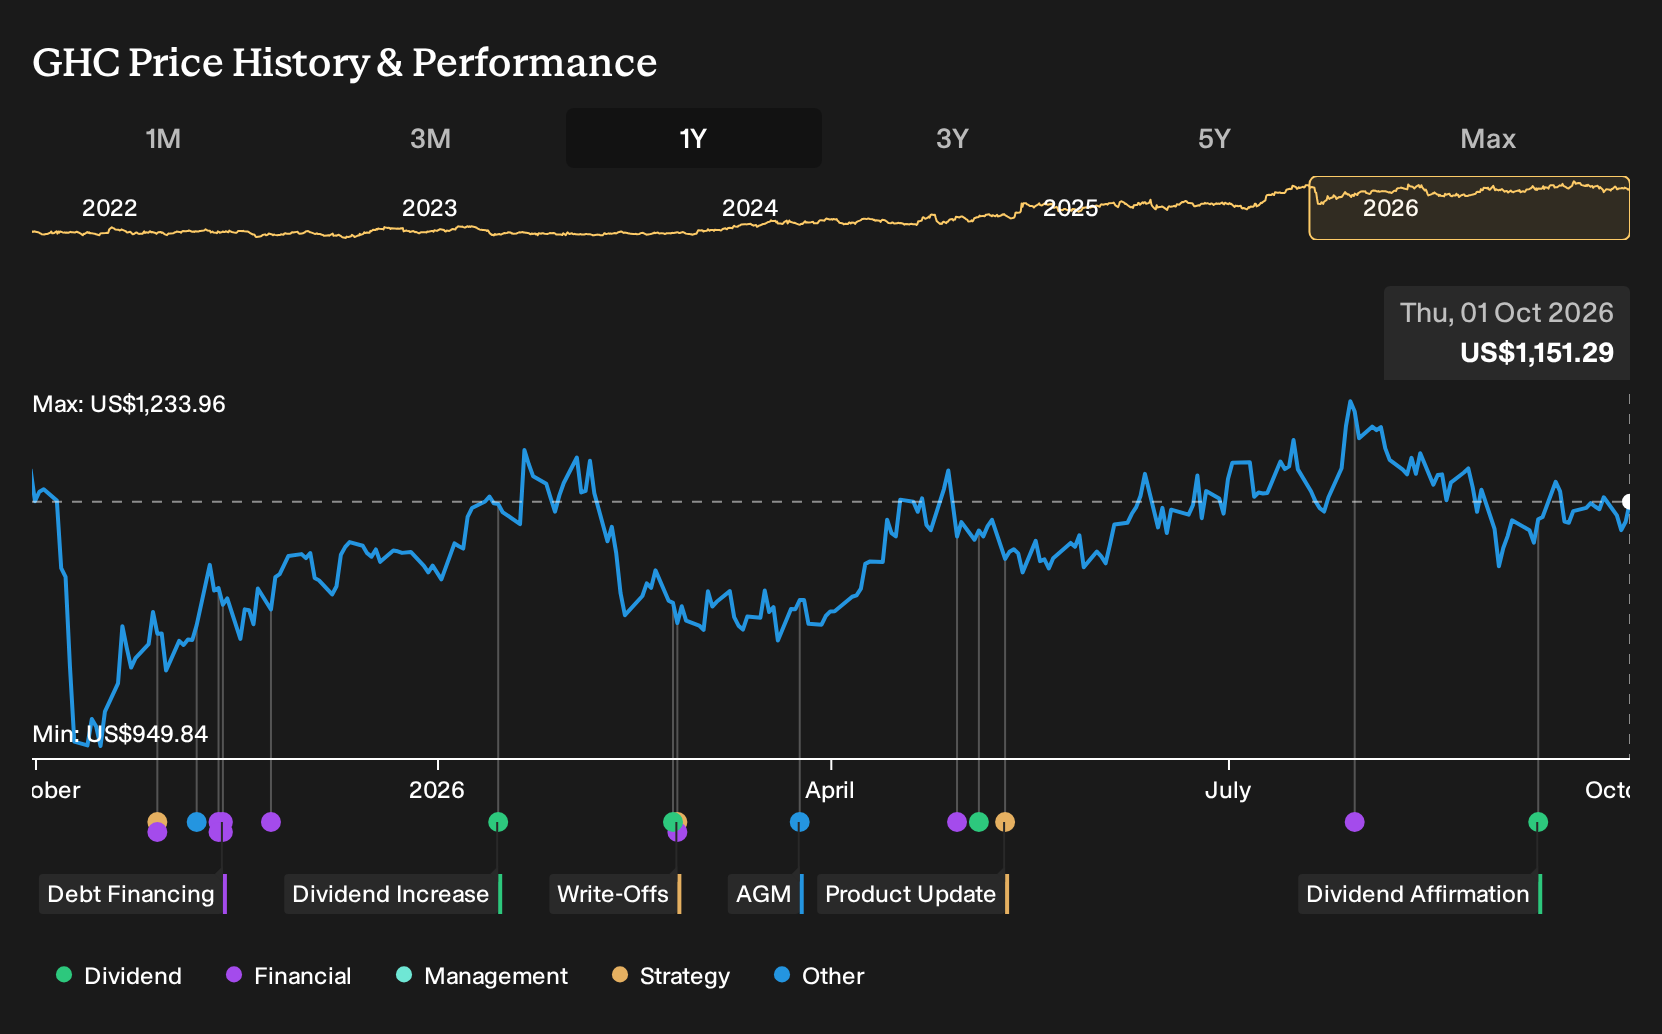
In the near term, the more important levers are execution in capital heavy segments like automotive, manufacturing and healthcare, plus pricing power in Kaplan and broadcasting. Net profit margins slipped from 14% to 10.7% and earnings fell 20.3% over the past year, while results also include a US$166.4m one off gain. That mix makes reported numbers harder to read. On the other side of the ledger, GHC trades at about 9x earnings and is flagged as good value, with the share price up about 4.9% over 30 days but flat over one year. Awards at Code3 may help the narrative around digital capabilities, although they do not change the fundamental risk that...
There's only one way to know the right time to buy, sell or hold Graham Holdings. Head to Simply Wall St's company report for the latest analysis of Graham Holdings's Fair Value.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community range from about US$990 to roughly US$2,324,780.94, which is an extremely wide spread for Graham Holdings. Those private investors clearly do not agree. Use that gap as a prompt to test your own view, especially in light of Code3’s recent award momentum.
Explore 2 other Graham Holdings fair value estimates, including one that suggests a potential increase of up to 201828% from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Graham Holdings research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Graham Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Graham Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Graham Holdings?
Once you have a view on Graham Holdings, it can help to compare that thesis with a wider mix of businesses screened on consistent fundamentals.
- For investors who want income at the center of their approach, scan companies filtered for yield and payout strength using the 7 dividend fortresses.
- If capital preservation is your first priority, focus on balance sheets and risk scores with the 31 resilient stocks with low risk scores.
- When you are hunting for underfollowed opportunities with solid fundamentals, broaden your watchlist through the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com