


Moody's (MCO) Has A Fresh Update, But What Is Drawing Attention Now?
Moody's stock and a new push into private credit analytics
Moody's (MCO) just rolled out a new Moody's Analytics EDF-X Private Credit Model with Allvue Systems, targeting early detection of borrower stress in the growing private credit market.
The launch focuses on spotting soft warning signs like covenant waivers and payment-in-kind structures before they turn into missed payments or defaults, giving lenders and investors another lens on portfolio risk.
Recent trading has been rough for Moody's, with the share price down 9.6% over the past month and 10.4% year to date to US$447.36, even though the 3 year total shareholder return of 46.0% still points to a much stronger longer run. Short term weakness, including a 1 day share price decline of 1.5% and 1 week drop of 4.3%, suggests momentum has faded as investors reassess risk around credit markets and wait on the upcoming third quarter 2026 earnings release. At the same time, longer horizon total shareholder returns of 28.6% over 5 years frame the new private credit model as one more development in an already evolving risk analytics story.
Spot opportunities alongside Moody's by scanning a curated 31 resilient stocks with low risk scores that focuses on resilient balance sheets and more controlled risk profiles in credit-sensitive areas.Moody's has rolled out new tools in private credit just as the share price has slipped, raising a simple question. Is the recent drop more about changing views on the business, or a swing in sentiment that has moved too far ahead of the valuation work?
Most Popular Narrative: 5.5% Undervalued
Moody's last closed at $447.36, while the most followed narrative pegs fair value at $473.36. This points to a modest valuation gap that hinges on how durable investors think the business is over the long haul.
Ultimately, Moody’s represents a rare combination of financial infrastructure dominance and software-like economics. It is a business designed to become more valuable as global debt markets expand, regulations grow more complex, and financial institutions require deeper risk analytics. For long-term investors, the thesis is less about predicting the next quarter and more about owning a near-irreplaceable piece of the global capital system.
See why 5 investors see Moody's as 5% undervalued.
Result: Fair Value of $473.36 (UNDERVALUED)
Still, two pressure points could upset the Moody's narrative: a deeper or prolonged slump in global debt issuance, and any regulatory shift that weakens the rating duopoly.
Find out about the key risks to this Moody's narrative.
Another View: Moody's Valuation Looks Rich On Earnings
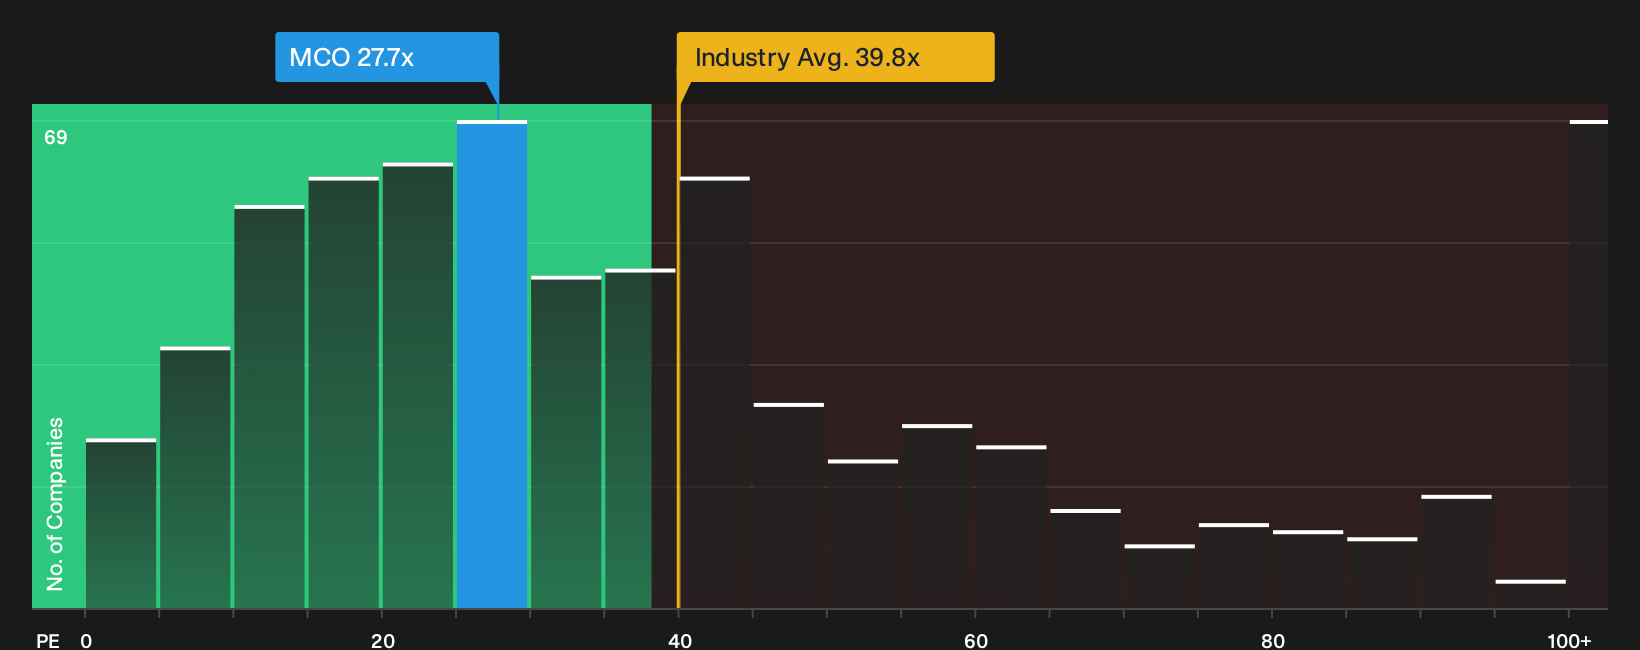
The fairness story around Moody's shifts when you move away from fair value narratives and look directly at the P/E. The stock trades on 27.7x earnings, above the peer average of 23.2x and significantly higher than an estimated fair ratio of 15.5x. That difference indicates a higher bar for future execution, so how comfortable are you paying this level of valuation for this quality of business?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Moody's valuation story and risk profile are clear. Move quickly, test the numbers yourself, and weigh the 4 key rewards and 1 important warning sign.
Looking for more Moody's style investment ideas?
If Moody's has sharpened your focus on quality and risk, do not stop here. Broaden your watchlist now and keep your options working for you.
- Target resilient cash generators by scanning a 28 high quality undervalued stocks that highlights businesses combining solid fundamentals with prices that trail their underlying strength.
- Strengthen your income stream and compare Moody's against a 7 dividend fortresses built around higher yielding payouts with an emphasis on staying power.
- Prioritize financial durability with a list of solid balance sheet and fundamentals (25 results) that filters for companies carrying sturdier balance sheets and more controlled leverage profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com