


Tractor Supply (TSCO) Could Be 11% Undervalued Following Its New Idaho Distribution Center
Tractor Supply (TSCO) just cut the ribbon on an 865,000 square foot distribution center in Nampa, Idaho, a US$200m logistics build that adds automated and AI enabled capacity across nine states.
The logistics build lands at a tricky moment for investors. Tractor Supply’s share price has fallen 37.6% year to date to US$31.73, and the 1 year total shareholder return is down 42.2%. A 30 day share price decline of 8.6% points to fading momentum despite the Nampa expansion and recent Petsense Adoptathon news.
Compare Tractor Supply’s logistics-heavy story with other retailers that are quietly building similar foundations in our hand picked list of list of solid balance sheet and fundamentals (25 results).
Tractor Supply now pairs fresh logistics spend with a share price that has already reset hard. Does that shift the next chapter toward opportunity, or signal that the risk still leans heavier than the potential reward as valuation comes into focus?
Most Popular Narrative: 10.6% Undervalued
On the most followed view, Tractor Supply screens as modestly undervalued, with a fair value of $35.48 set against the last close at $31.73. This puts the current pullback in a different light for anyone weighing the new Nampa spend against future cash flows.
The new automated distribution center in Nampa, Idaho, which is expected to support more than 200 stores over time and is targeted to add about 20 basis points to gross margin in late 2026, could provide ongoing net margin benefits as supply chain efficiencies scale.
See why 43 investors see Tractor Supply as 11% undervalued.
Result: Fair Value of $35.48 (UNDERVALUED)
Still, Tractor Supply faces real pressure if comparable sales weakness deepens, or if tariff refunds and vendor support fade faster than freight and fuel costs ease.
Find out about the key risks to this Tractor Supply narrative.
Another View: Tractor Supply Through The P/E Lens
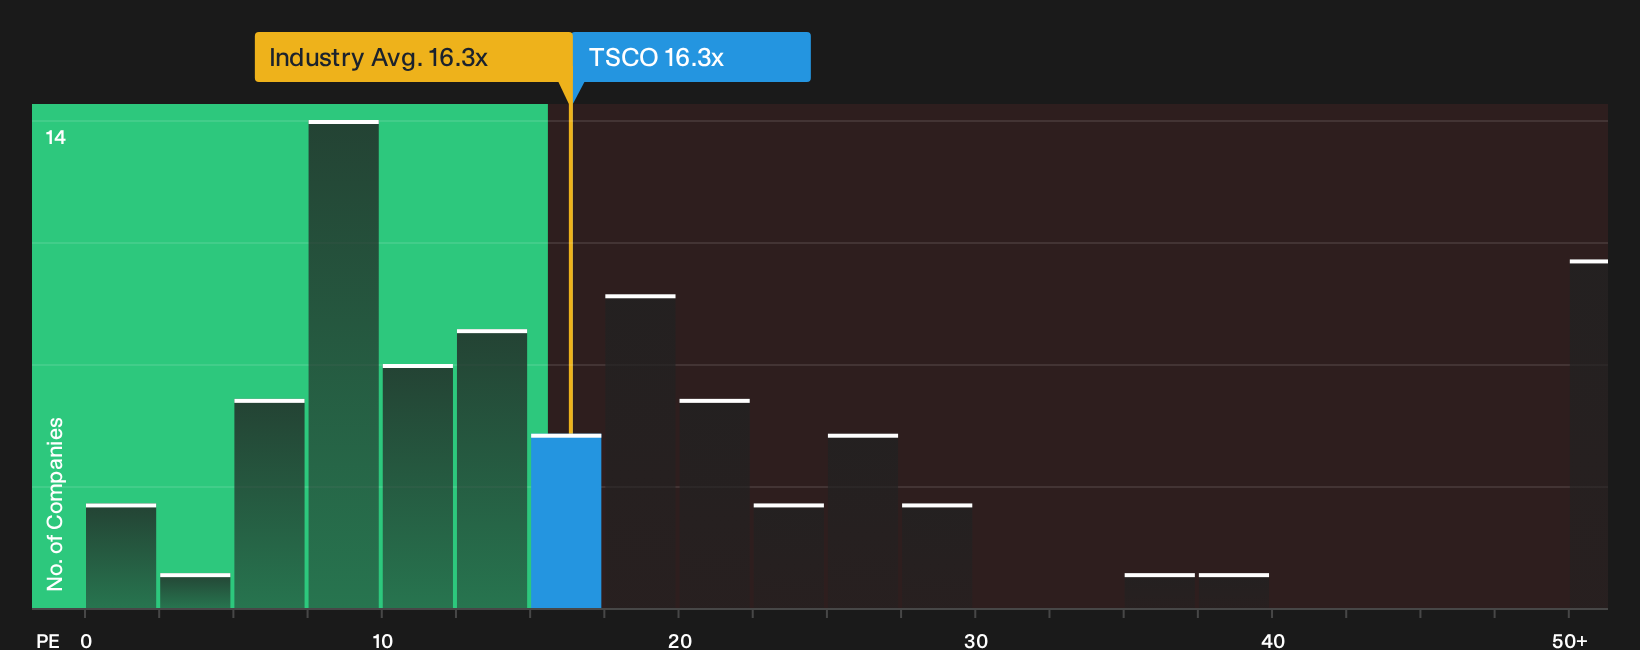
The SWS DCF model points to Tractor Supply trading below an estimated future cash flow value of $40.08, yet the picture from earnings multiples looks less generous. The stock sits on a 16.3x P/E, roughly in line with the US Specialty Retail average at 16.3x, but above an estimated fair ratio of 15.2x. That mix of DCF upside and a slightly rich P/E raises a simple question for you: Which signal matters more for your own risk tolerance?
To see how this earnings based view stacks up against a full cash flow build, and what assumptions sit underneath it, See what the numbers say about this price — find out in our valuation breakdown.
Here is how Tractor Supply’s valuation compares with peers on this lens visually:
Next Steps
If this combination of pressure and potential around Tractor Supply seems finely balanced, consider acting promptly and weighing the trade off yourself by drilling into the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Tractor Supply?
If Tractor Supply is on your radar, this is the moment to line up a few alternatives so you are not relying on a single story.
Use the Simply Wall St Screener to surface fresh ideas with different risk and income profiles while this valuation question is front of mind.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount by checking companies in the 28 high quality undervalued stocks.
- Prioritise income potential and cash returns by reviewing the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com