


Societe Generale Stock In Focus As 50% Payout Policy Adds Buybacks
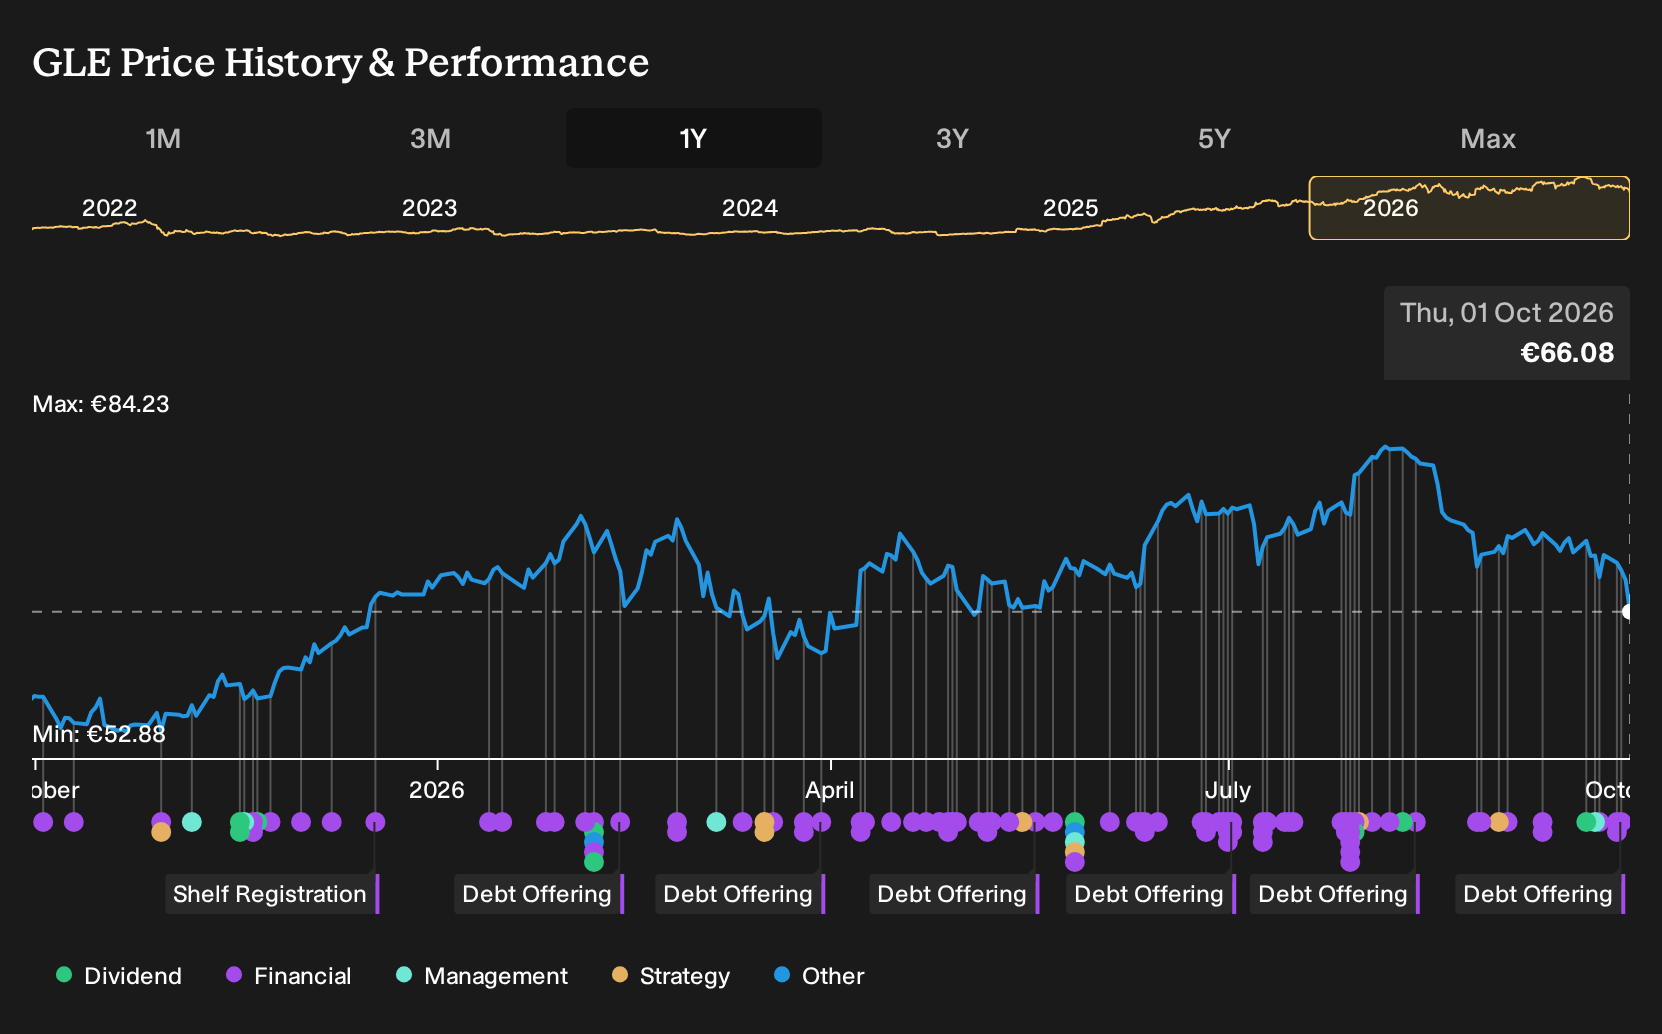
- Société Générale Société anonyme recently completed several fixed income offerings, including US$1.5b in fixed to floating rate notes and multiple euro senior notes. It also set out a multi-year policy to distribute 50% of reported net income through a mix of cash dividends and share buy-backs.
- The combination of fresh wholesale funding and a clearly articulated capital return framework signals how Société Générale is balancing balance sheet flexibility with shareholder distributions, while its retail and digital banking plans evolve.
- We will now explore how Société Générale's new 50% payout and buy-back framework could reshape the bank's broader investment narrative.
Scan a curated set of banks and financials that use wholesale funding and capital return programs similar to Société Générale Société anonyme by reviewing the list of solid balance sheet and fundamentals (207 results).
Société Générale Société anonyme Investment Narrative Recap
To own Société Générale Société anonyme, you need to be comfortable with a European lender that leans heavily on net interest income, while pushing hard on digital banking through BoursoBank and on cost efficiency. The recent fixed income deals look more like balance sheet housekeeping than a change in direction. As a result, the near term story still revolves around execution on cost, digital and fee income.
The most immediate swing factor remains the interest rate backdrop in Europe, which shapes margins across retail and wholesale units. On the risk side, you are still exposed to a relatively high bad loan ratio, a meaningful use of wholesale funding and a concentrated footprint in France if asset quality weakens.
Among the recent announcements, the new 50% payout policy with a mix of cash dividends and buy backs, plus a framework to return excess capital above a 13% CET1 ratio, matters most for this funding activity. It sets expectations around how fresh wholesale funding, retained earnings and potential disposals feed through to shareholder distributions.
For you as an investor, that distribution plan turns execution on earnings, asset quality and funding costs into very visible catalysts. Any pressure on bad loans, funding spreads or profitability could affect the room to keep that payout mix intact, which is why the interaction between these bond issues, capital generation and risk management deserves close tracking over the next few years.
Société Générale Société anonyme's current analyst framework points to €30.2 billion in revenue and €7.7 billion in earnings by 2029, based on a forecast 5.1% yearly increase in revenue and an earnings step up of €2 billion from the €5.7 billion reported today.
Uncover why Société Générale Société anonyme's fair value indicates a 36% potential upside to its current price, a discount that could close quickly.
Exploring Other Perspectives
One alternate view zooms in on digital disruption rather than funding. In that more optimistic story, analysts were expecting Société Générale Société anonyme to reach about €32.0 billion of revenue and €8.7 billion of earnings by 2029. Those forecasts came before this latest bond issuance, so you should expect that narrative to evolve as new data arrives.
Explore 3 other Société Générale Société anonyme fair value estimates, including one that suggests as much as 123% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Société Générale Société anonyme research is our analysis highlighting 5 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Société Générale Société anonyme. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Société Générale Société anonyme's overall financial health at a glance.
Looking For More Ideas Beyond Société Générale Société anonyme?
If you want to pressure test your thesis on Société Générale Société anonyme, it can help to line it up against other banks and financials with different balance sheet strengths, payout profiles and risk levels. The Simply Wall St Screener gives you a quick way to scan wider markets and spot alternatives that fit your own return and volatility preferences.
- If capital preservation sits near the top of your checklist, you can start with companies that screen as more resilient on risk metrics through the 226 resilient stocks with low risk scores.
- If you prefer a steadier stream of income, you can focus on businesses with higher yields and supporting fundamentals by reviewing the 168 dividend fortresses.
- If you are hunting for mispriced opportunities, you can widen the search to stocks that combine quality fundamentals with modest valuations using the 191 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com