


Cellebrite DI (CLBT) On ARR Guidance Cuts And CEO Exit Faces A Valuation Reset
Cellebrite DI (NasdaqGS:CLBT) is back in focus after Q2 2026 results fell short on Annual Recurring Revenue, full year ARR guidance was reduced, and CEO Tom Hogan was abruptly replaced, prompting legal scrutiny and a sharp share reaction.
The latest volatility fits into a tougher stretch for Cellebrite DI, with the share price falling 28.8% over the past 90 days and declining 37.6% year to date. However, the 3-year total shareholder return of 47.0% still reflects a very different earlier phase of the story.
Balance short term shock in Cellebrite DI with a fresh look at digitally focused investigators and security software peers, using our hand picked 19 high quality undiscovered gems as a starting list.
The drop in Cellebrite DI after the ARR miss and CEO exit has sharply reset expectations. The question now is whether the valuation already reflects this reset or if most of the upside was captured earlier.
Most Popular Narrative: 27% Undervalued
Cellebrite DI last closed at $11.14, while the most followed valuation narrative points to a fair value near $15.36, so the debate now is whether the recent ARR reset and CEO change fully explain that gap.
The continued transition to a recurring, subscription-based revenue model, with over 90% of revenues now from subscriptions and growing SaaS/cloud penetration, improves revenue visibility, predictability, and operating leverage. This is already translating into higher EBITDA and free cash flow margins and is likely underappreciated in current valuations.
See why 20 investors see Cellebrite DI as 27% undervalued.
Result: Fair Value of $15.36 (UNDERVALUED)
Still, the narrative around Cellebrite DI can break if reliance on US federal contracts keeps ARR under pressure, or if rising privacy rules curb future demand.
Find out about the key risks to this Cellebrite DI narrative.
Another View: Cellebrite DI Looks Expensive On P/E
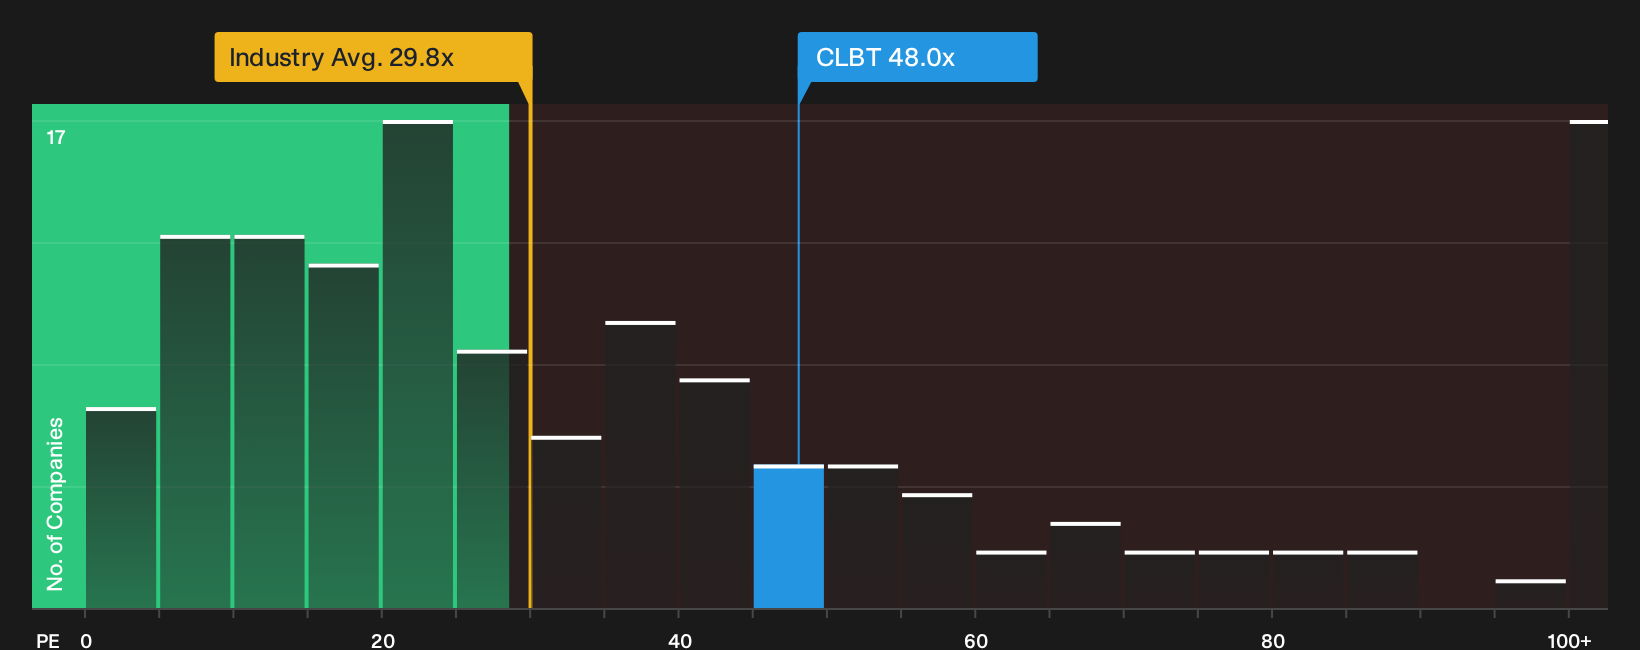
The DCF-based fair value for Cellebrite DI points to undervaluation, but the P/E picture is much less forgiving. The stock trades on about 48x earnings, compared with 29.8x for the US Software industry, a peer average near 47.8x, and a fair ratio estimate of 33.8x.
That gap means you are paying a premium multiple today. The market could decide to move the P/E closer to the 33.8x fair ratio or even toward the wider sector. This would put more pressure on returns if the growth narrative softens again.
See what the numbers say about this price in more detail by reading See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Cellebrite DI is clearly mixed right now, so move fast, review the underlying figures yourself, then weigh up the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cellebrite DI?
If you want more context around Cellebrite DI, broaden your watchlist with fresh ideas from the Simply Wall Street Screener so you do not miss other opportunities.
- Spot potential mispricings early by reviewing a curated selection of 28 high quality undervalued stocks that pair stronger fundamentals with more appealing entry points.
- Steady your portfolio by checking out a 31 resilient stocks with low risk scores that aims to limit unpleasant surprises when markets turn choppy.
- Strengthen your income stream by scanning a focused 7 dividend fortresses that targets higher yields backed by sturdier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com