


Lucid Group (LCID) Stock Climbed, What Is Behind The Move?
Lucid Group (LCID) has put its software story front and center with Air UX 3.0, a broad infotainment refresh that reworks navigation, controls, and smartphone integration across Lucid Air vehicles.
Air UX 3.0 lands at a time when Lucid Group’s recent 1-day share price return of 2.95% and 7-day share price return of 0.96% sit against a much weaker backdrop, with the 90-day share price return down 31.09% and the 1-year total shareholder return down 82.61%. Any renewed interest around software upgrades is therefore emerging in the context of a stock where long term holders have already faced heavy declines.
Compare Lucid Group’s software focused EV story with other hand picked electric and future mobility plays by scanning 90 robotics and automation stocks, which could benefit as vehicles become more computer than car.
Lucid Group just logged a small bounce while long term returns remain deeply negative, which leaves you deciding whether to treat this as an early reset point or wait for an even cheaper entry before running the valuation math.
Most Popular Narrative: 50% Undervalued
Lucid Group closed at $4.19 against a widely followed fair value estimate of $8.40, which frames the current debate around whether today’s pricing already reflects execution risk or still leaves a wide valuation gap.
The newly announced Uber and Nuro partnership, including a planned $300 million Uber investment and a commitment to deploy at least 20,000 Lucid Gravity vehicles as robotaxis over six years, is expected to open a large and fast-growing autonomous fleet market to Lucid, driving significant revenue expansion and potential margin improvement via technology licensing and high-volume fleet sales.
See why 184 investors see Lucid Group as 50% undervalued.
Analysts behind this narrative apply a 12.46% discount rate and arrive at fair value based on long term expectations for revenue, margins, and capital intensity. They also flag that Lucid is currently loss making and reliant on external funding. The same framework links that $8.40 fair value to assumptions about future production in Saudi Arabia, a midsized EV platform, and ongoing partnerships, set against risks such as dilution, intense EV competition, and less than one year of cash runway.
Result: Fair Value of $8.40 (UNDERVALUED)
Still, Lucid Group faces two pressure points that could unravel this upside story: ongoing heavy losses and reliance on fresh capital that raises dilution risk.
Find out about the key risks to this Lucid Group narrative.
Another View: Lucid Group Looks Expensive On Sales
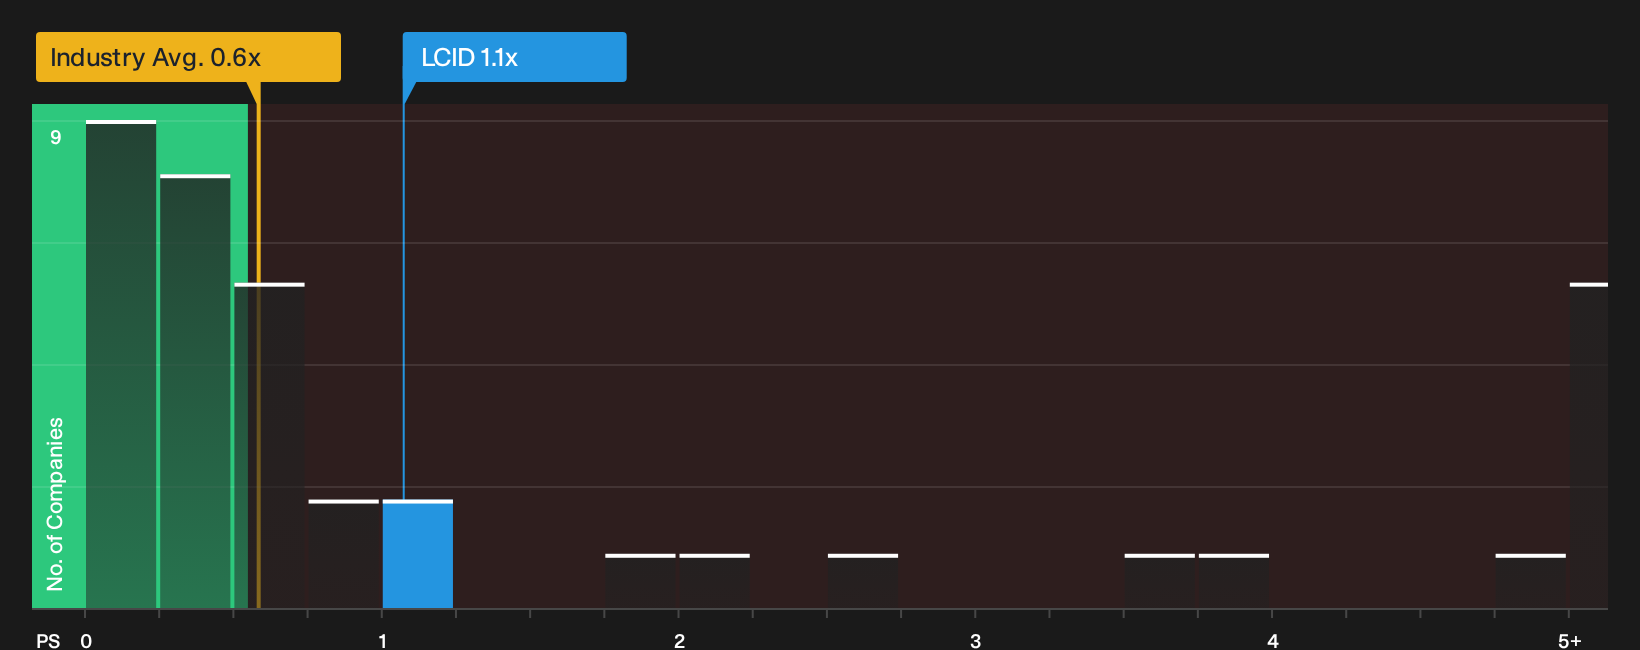
A second lens on Lucid Group strips out the fair value target and instead compares what you pay for each dollar of revenue. On this measure, the stock trades on a P/S of 1.1x versus 0.6x for the US Auto industry and 0.5x for peers, while the fair ratio sits at 0x. This points to valuation risk if sentiment turns.
For anyone weighing those gaps against the earlier upside case, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Lucid Group’s valuation and business risks make this a judgement call, so move quickly to review the underlying data yourself and weigh both sides of the story. Start with the 1 key reward and 4 important warning signs.
Looking for more Lucid Group investment ideas?
If Lucid Group has your attention, broaden your watchlist with other stocks that match clear themes, strong fundamentals, and different risk profiles across the market.
- Target potential mispricing by scanning for companies that pair quality fundamentals with attractive valuations using the 28 high quality undervalued stocks.
- Secure more dependable income streams by focusing on businesses with higher yields and resilient payouts through the 7 dividend fortresses.
- Dial down portfolio volatility by concentrating on sturdier balance sheets and steadier financial profiles via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com