


Wheaton Precious Metals (TSX:WPM) Stock May Be 41% Undervalued On Cash Flow
Wheaton Precious Metals has delivered a very strong multi year share price run, which naturally raises the question of whether the current valuation can still be explained by the cash it is expected to generate. With the stock now trading at around C$189.48 after a softer recent spell, the real issue for you is how that price lines up with the company's projected cash flows.
- Over the past 5 years, Wheaton Precious Metals has returned about 322.1%, so a lot of investor wealth now hinges on whether the underlying cash flows can keep supporting that kind of market value.
- The business model is built around streaming agreements that can convert commodity production into relatively visible cash inflows, which may support investors who are focused on how dependable and long dated those cash flows look.
- What if you looked at Wheaton Precious Metals through its earnings instead? See why Wheaton Precious Metals's 29.5x P/E tells a different valuation story.
The stock's next move may depend on whether that C$189.48 share price is fully justified by Wheaton Precious Metals' expected cash flows when you compare it with the intrinsic value estimate from the Discounted Cash Flow (DCF) approach.
If you want more ideas that keep the focus on cash generation, a focused stock screen is a useful next step for research, especially one that highlights 5 high quality undervalued stocks.
Is Wheaton Precious Metals a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here uses a 2 Stage Free Cash Flow to Equity framework to link Wheaton Precious Metals' future cash generation to today’s CA$189.48 share price. Latest twelve month free cash flow sits at a loss of about $1.24b, so the whole exercise hinges on whether that dip is temporary rather than a new normal for the business.
Analysts and model estimates point to recovering and then growing free cash flow, with projected annual figures reaching into the multibillion dollar range by the early 2030s. That pattern fits a mature streamer where existing contracts and expected additions are assumed to convert into steadier cash inflows over time rather than rapid expansion. On those cash flow projections, the DCF output suggests an intrinsic value that sits substantially above where Wheaton Precious Metals currently trades, so the question for you is whether those long range assumptions feel realistic enough to underpin that gap. Find out what Wheaton Precious Metals could be worth using our Discounted Cash Flow (DCF) estimate.
The Wheaton Precious Metals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Wheaton Precious Metals sit between that DCF puzzle and your own view by spelling out which future paths for growth, margins and earnings would need to play out for the shares to end up worth materially more or less than today’s price on the Community page. Each scenario links its number to a clear stance on how Wheaton Precious Metals' expansion prospects, profitability and risk profile could evolve, so you have something concrete to revisit as new information comes through.
Community views on Wheaton Precious Metals are split between investors who see extra upside and those who think expectations already look full.
Bull case: 23% undervalued
"Wheaton's strong financial position, with $1B in cash and a $2B undrawn credit facility, provides flexibility to pursue additional accretive streaming deals."
Discover why this Narrative puts Wheaton Precious Metals at 23% undervalued.
Bear case: roughly fairly valued
"The company is exposed to a relatively concentrated asset base, with core assets like Salobo representing a significant portion of production."
Explore why this Narrative puts Wheaton Precious Metals at roughly fairly valued.
One more unresolved piece of the Wheaton Precious Metals puzzle
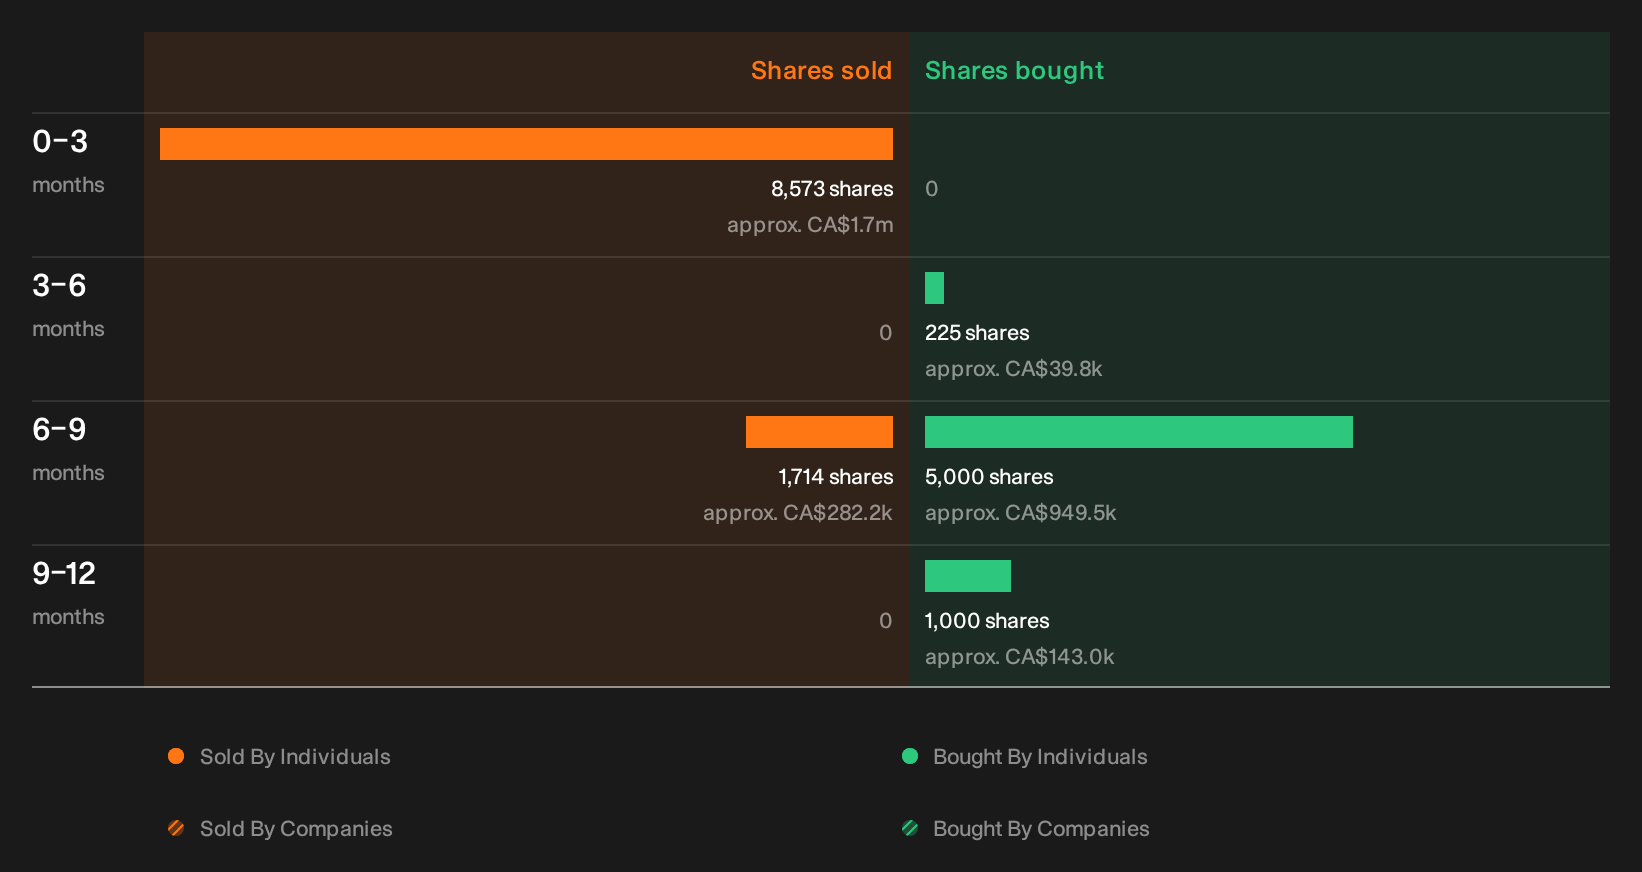
Before calling the picture complete, it is worth checking what insiders have been doing with their own holdings, since recent selling has been flagged and the specific sellers, sizes and possible read throughs are still for you to review. See the recent insider selling flagged for Wheaton Precious Metals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com