


Can Ocular Therapeutix (OCUL) Justify Its Price On Sales?
Ocular Therapeutix has seen a sharp pullback this year after a very strong three year share price run, which puts the focus squarely on whether the current valuation can be explained by its sales profile. With the stock now around US$7.29, investors are weighing the recent news around its wet age related macular degeneration program against what the business is actually generating in revenue.
- The share price has risen 144.6% over the past three years, which raises the question of how much of that move can be backed up by the company’s sales base.
- The positive pre New Drug Application meeting for AXPAXLI and plans for a future filing may support expectations for higher product revenue and a longer commercial runway if the therapy eventually reaches the market.
- There is a second opinion on Ocular Therapeutix worth weighing. See what analysts think Ocular Therapeutix's shares could be worth.
For investors, the debate is whether today’s Ocular Therapeutix share price is adequately supported by what its sales suggest the business is worth.
To pressure test Ocular Therapeutix against similar opportunities in your watchlist, it can help to compare it with 35 healthcare AI stocks.
Is Ocular Therapeutix Getting Expensive on Sales?
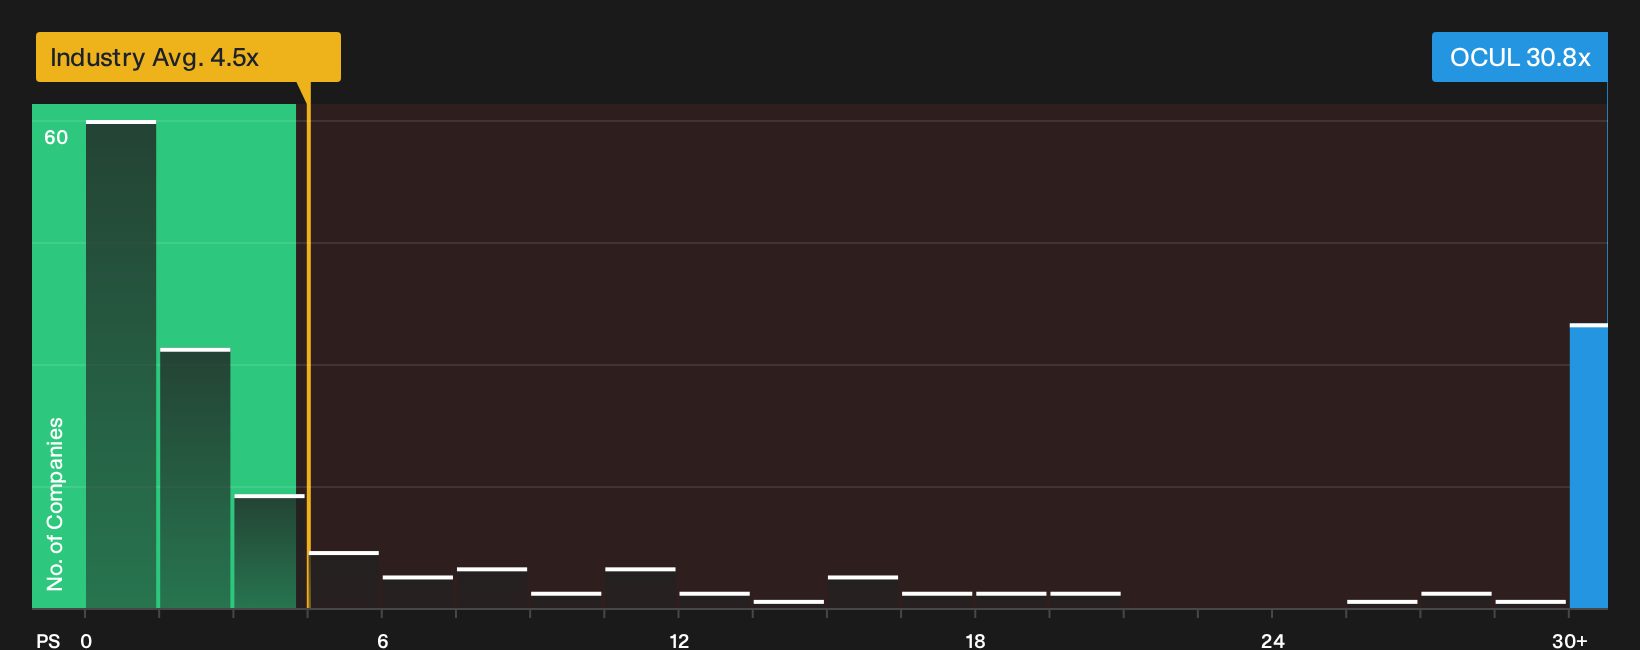
P/S is a common yardstick for Ocular Therapeutix because the company is still working toward sustained profitability, so revenue is the cleaner anchor for the share price. On this measure, the stock trades on a P/S of 30.8x, which is far above the Pharmaceuticals industry average of 4.5x and also well above the peer group around 5.5x. That is a big gap for a company whose current sales base is still relatively modest in sector terms.
The fair multiple model, which adjusts for factors like growth potential, margins, risk and size, flags the present P/S as overvalued. The implied fair P/S is much lower than 30.8x, and the extreme difference suggests the framework is heavily penalising Ocular Therapeutix for losses and execution risk rather than pointing to a precise target level. Despite the positive AXPAXLI regulatory progress and plans for a possible 2027 launch, the current valuation still implies a very rich P/S compared with what this model would usually assign to a business with a similar profile. Explore the numbers behind Ocular Therapeutix's P/S valuation.
The Ocular Therapeutix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle for Ocular Therapeutix leaves off by explaining which future paths for revenue growth, profitability and earnings power would need to occur for the stock to be worth materially more or less than it is today. Each scenario on Ocular Therapeutix's Community page turns that view of fair value into a thesis about the business that you can track over time, rather than a one off snapshot.
One of the top community narratives on Ocular Therapeutix: 73% undervalued
"Heavy dependence on a single pipeline asset exposes Ocular Therapeutix to clinical, regulatory, and competitive risks that threaten margins, revenue, and sustainable growth..."
Discover why this Narrative puts Ocular Therapeutix at 73% undervalued.
Before focusing on Ocular Therapeutix's valuation, there is one more piece to check
Price multiples only tell part of the Ocular Therapeutix story, because our broader checks have flagged specific areas of concern that some investors may want to review for themselves. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com