


Learn Why The Bull Case For Besi Shares Could Change Following EPIC Center Partnership
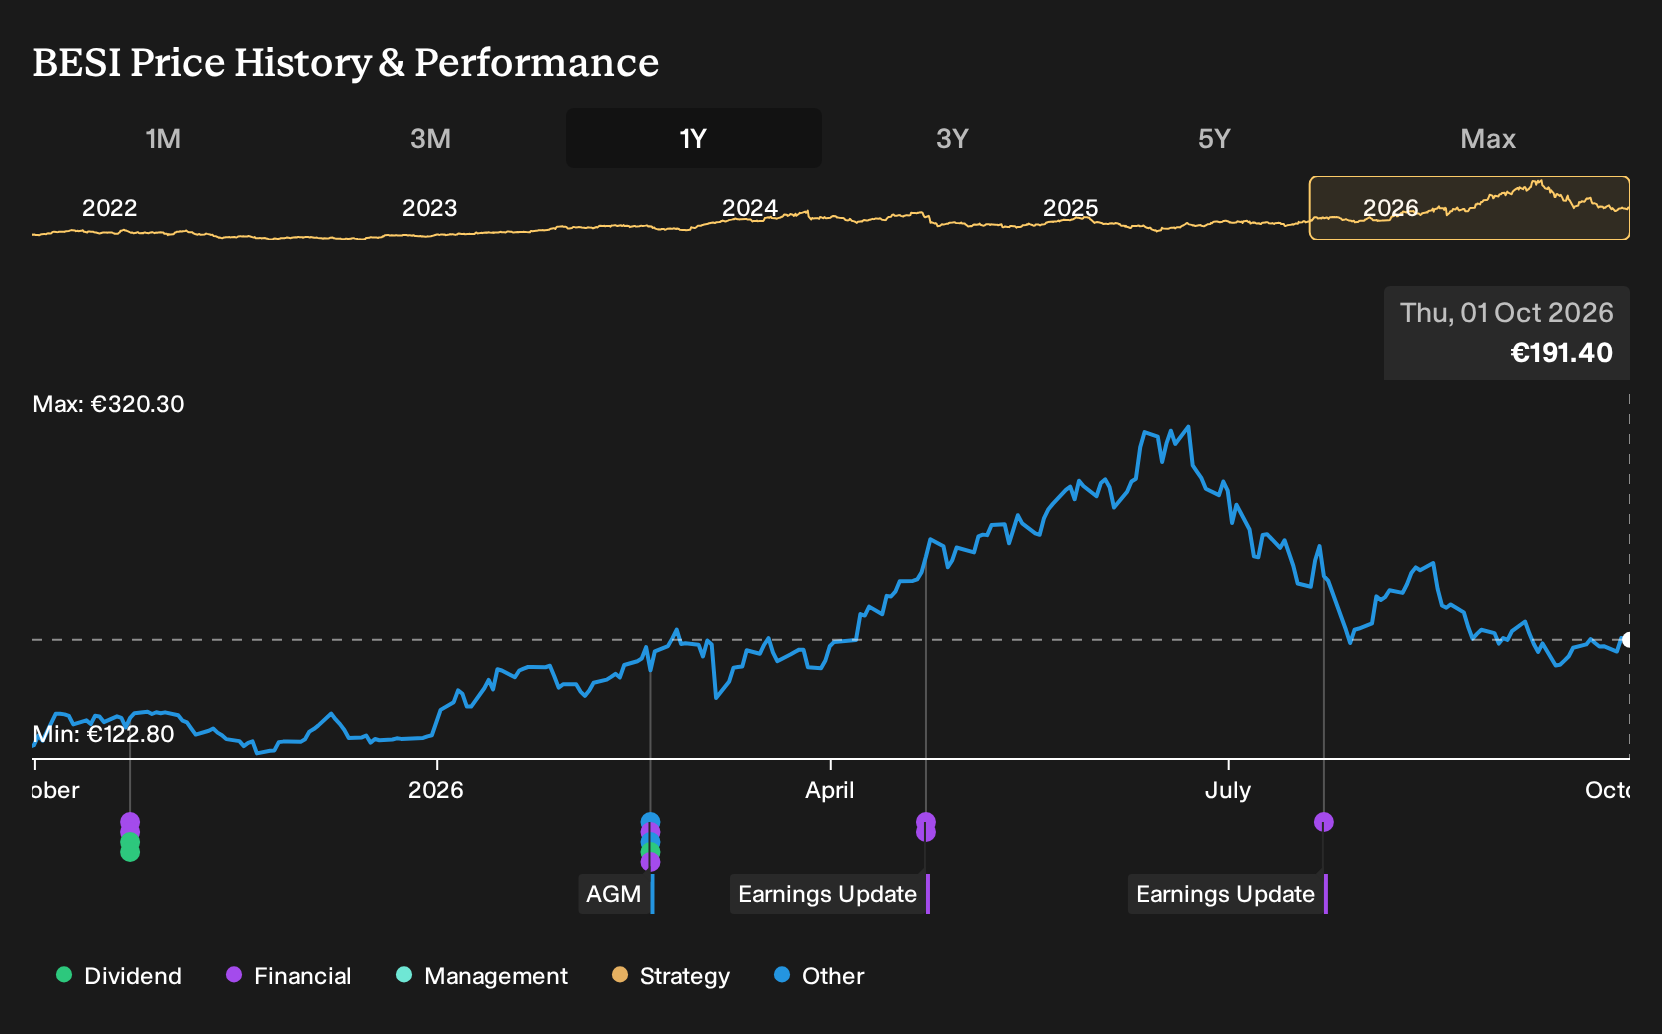
- Applied Materials and BE Semiconductor Industries announced an expanded partnership in 2026, with Besi joining Applied’s new EPIC Center as an Innovation Partner to co-develop advanced packaging and interconnect technologies for AI focused chips.
- The collaboration brings Besi engineers directly into Applied’s €5b EPIC Center R&D environment, giving shared customers earlier access to co-optimized process and assembly flows from wafer-level hybrid bonding through panel-scale integration.
- The next area of focus will be how BE Semiconductor Industries’ deeper role at the EPIC Center could influence its investment narrative around advanced packaging.
BE Semiconductor Industries Investment Narrative Recap
To hold BE Semiconductor Industries, you need to believe the long term shift toward advanced packaging for AI, data center and high bandwidth memory stays intact, and that the firm keeps converting its R&D into equipment that customers actually order. The Applied EPIC Center partnership fits directly into that story, but by itself does not change the near term setup.
The near term swing factor still looks like order momentum in advanced packaging versus ongoing softness in mainstream mobile and automotive tools, where activity has fallen back toward 2019 levels. The biggest risk is that recovery in these legacy segments stays slow while R&D and currency headwinds keep pressing on margins and earnings.
The expanded EPIC Center partnership is the announcement that matters most for this news. Applied is putting up about €5b of R&D capacity around process equipment and advanced packaging flows, and BE Semiconductor Industries now has engineers embedded there. That gives the Dutch group another high profile platform to align its hybrid bonding and TCB tools with front end process steps.
From a catalyst angle, this matters because analysts already frame BESI’s story around accelerated adoption of hybrid bonding, TCB Next and advanced packaging for AI compute and HBM. Faster co development with a major equipment supplier could help shorten the path from pilot tools to volume shipments. Execution risk does not disappear though, especially around timing of customer CapEx, product mix and the return on higher R&D spend.
BE Semiconductor Industries Consensus Setup
BE Semiconductor Industries is being modeled on some punchy numbers. Analysts are working with a view that revenue could compound at 35.3% a year over the next three years, while profit margins move from 28.4% today toward 40.9% over the same horizon. That backdrop feeds directly into how the EPIC Center story connects to earnings power, rather than just headlines about AI packaging.
On current forecasts, earnings today of €208.7 million are expected to reach consensus earnings of €743.0 million by 2029, which implies roughly a 3.5x step up in profit over the period. BE Semiconductor Industries' narrative also anchors on revenue reaching €1.8b and earnings of €743.0 million by 2029, which would require 35.3% yearly top line growth from here.
Uncover why BE Semiconductor Industries' fair value indicates a 51% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts think the real swing factor for BE Semiconductor Industries is not just AI demand but how fast hybrid bonding converts into revenue. Before this EPIC Center news, the bullish camp was already modeling revenue growth of 50.3% a year and earnings of €891.3 million by 2029. That is far above the consensus view, which assumes €743.0 million, and it shows how far opinions can stretch. Use this partnership update as a prompt to compare these different stories and decide which version of the future you find more convincing.
Explore 3 other BE Semiconductor Industries fair value estimates, including one that suggests potential upside of up to 51% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BE Semiconductor Industries research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BE Semiconductor Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BE Semiconductor Industries' overall financial health at a glance.
Looking For More Ideas Beyond BE Semiconductor Industries?
Once you have a view on BE Semiconductor Industries, it can help to set it alongside a few other opportunities with very different profiles. The Simply Wall St Screener lets you do that quickly by filtering for specific traits across thousands of listings.
- For investors who care most about balance sheet strength and fundamental resilience, start with a list of solid balance sheet and fundamentals (207 results) that already clear a high bar for financial quality.
- If you are hunting for mispriced opportunities where quality and valuation intersect, scan a hand picked group of 191 high quality undervalued stocks that may line up better with your risk and return preferences.
- For those who like the idea of getting paid while they wait, focus on income ideas through a selection of 168 dividend fortresses that combine higher yields with an emphasis on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com