


Omeros (OMER) Stock Looks Cheap After Its Huge Three Year Run
Omeros Corporation has delivered a very large share price gain over the past few years, which now puts a spotlight on whether that move is supported by its earnings power. After such a strong run, the question for anyone looking at Omeros today is whether the current market value lines up with what the business is actually earning.
- Omeros has returned about 571.6% over the past 3 years, which puts real pressure on the current earnings profile to justify that kind of share price reset.
- The launch of Yartemlea and an analyst upgrade tied to early sales can influence how investors think about future profitability, cash generation and the earnings base that might support today’s valuation.
- There is a second opinion on Omeros worth weighing. See what analysts think Omeros's shares could be worth.
The issue now is whether Omeros's current share price of US$18.47 is supported by its earnings when stacked against the Fair Ratio benchmark.
If you are weighing whether Omeros's recent share price surge matches its earnings profile, it can help to compare it with a broader set of 28 high quality undervalued stocks.
Is Omeros a Bargain on Earnings?
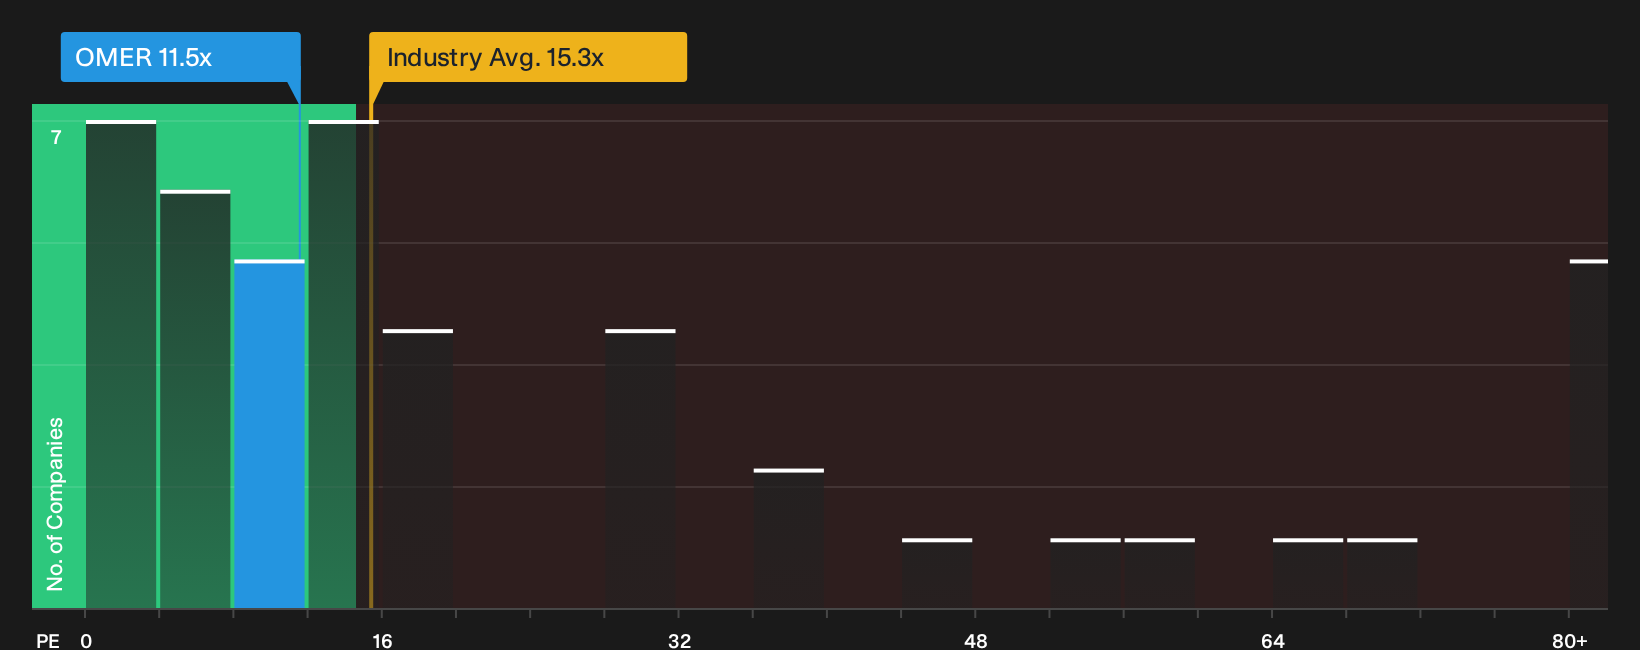
The P/E ratio is a useful lens for Omeros because earnings sit at the center of how investors are reassessing the stock after its recent surge. On this measure, Omeros trades at about 11.5x earnings, which is below the Pharmaceuticals industry average of roughly 15.3x. That gap is even wider against the peer group, where the average P/E comes in near 37.2x.
On Simply Wall St's Fair Ratio framework, which estimates the kind of P/E multiple that might fit Omeros given its risk profile, business model and sector, the current valuation screens as undervalued on earnings. Because the recent Yartemlea momentum and analyst upgrade have already pushed the share price higher, a P/E still below this tailored benchmark suggests the excitement has not fully erased the discount implied by the model. For anyone weighing whether the rally has gone too far or not far enough, this P/E context puts more weight on the idea that the stock may still be pricing in a lower earnings base than the framework would suggest. Explore the numbers behind Omeros's P/E valuation.
The Omeros Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St’s Community page pick up where Omeros' valuation puzzle leaves off, by spelling out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than today’s share price. Each scenario links a fair value estimate to a clear storyline about Omeros' potential catalysts and key risks, so you can see over time which version of events appears to be unfolding.
One of the top community narratives on Omeros: 16% undervalued
"The numbers and recent balance sheet moves together imply that the current share price already reflects a cautious view on Omeros..."
Discover why this Narrative puts Omeros at 16% undervalued.
One more thing about Omeros that deserves your attention
Before you focus only on where Omeros trades on a P/E basis, it is worth checking the specific risk checks that have triggered on this business and weighing what they might signal for you as a shareholder. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com