


What Has Actually Changed At PolyNovo (PNV)?
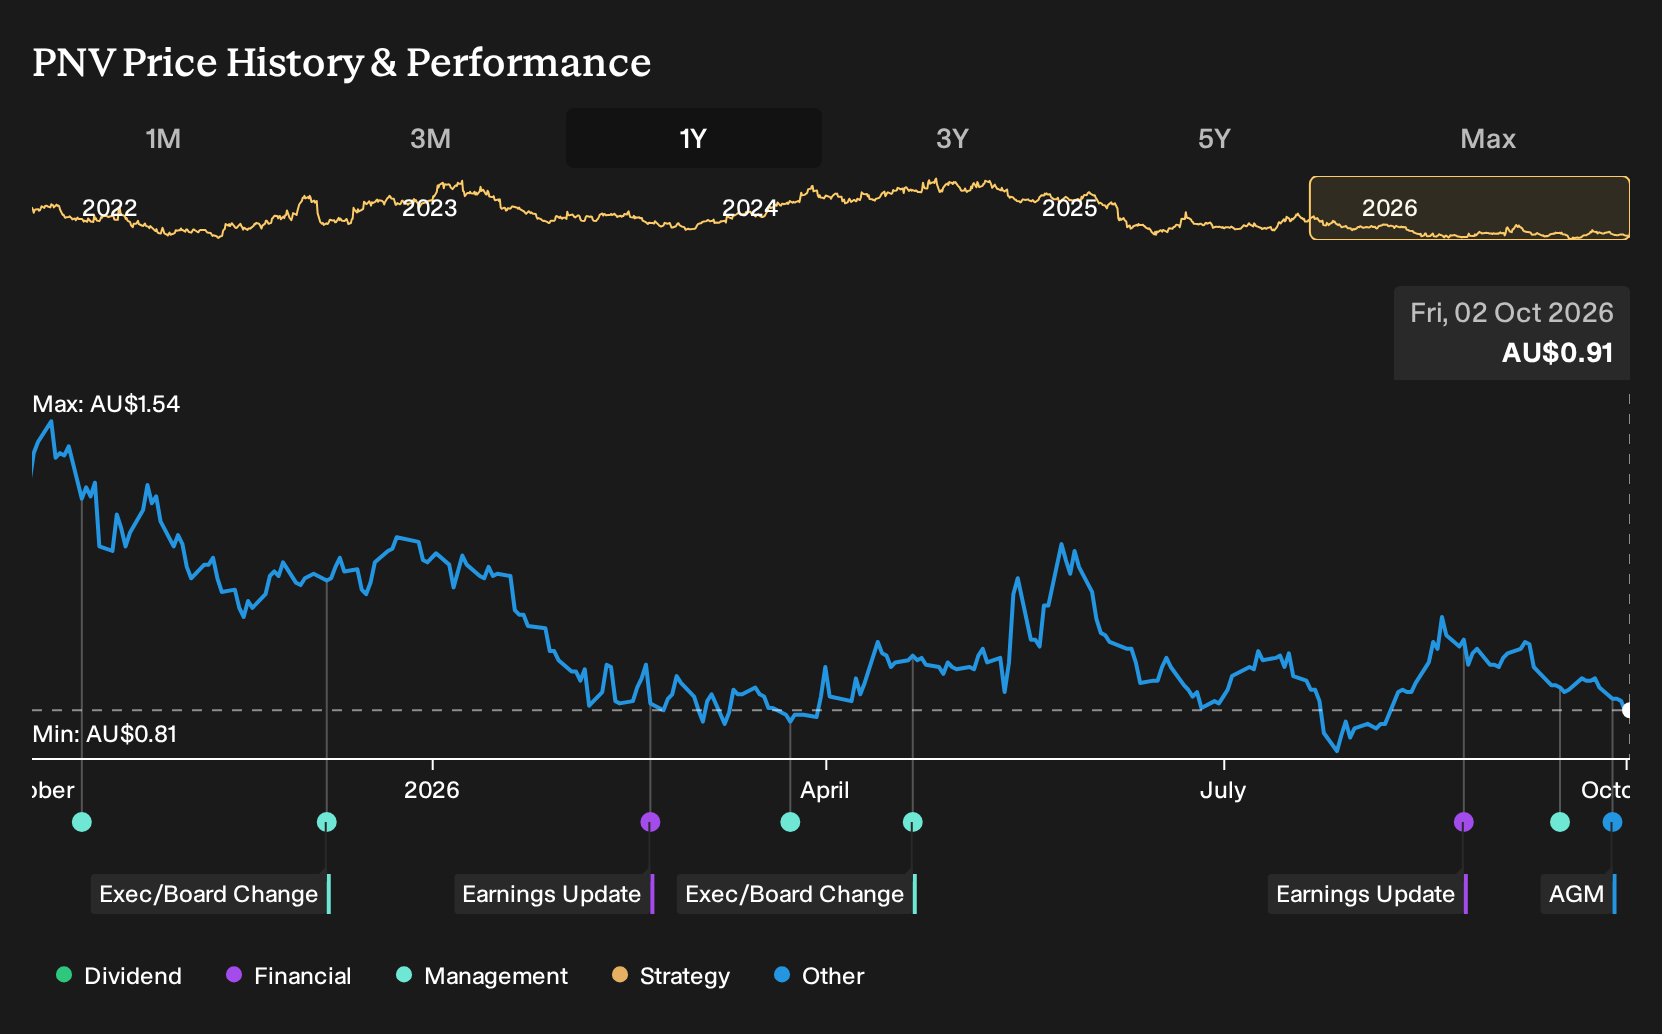
If you had paused on PolyNovo in late 2025 because the bullish and bearish analyst targets seemed too far apart to trust, the past year probably feels like a narrow escape. Investors who held PolyNovo over the past year are down 39.5%, including dividends. Recent results show higher revenue with a thinner net margin. The key question is simple: Which early clues about pricing power, product concentration, or regulation would you have wanted to stress test before committing?
If the move has made PolyNovo harder to judge, start where the gap is still open and scan 5 high quality undervalued stocks.
The Two PolyNovo Stories Investors Had To Hold In Their Heads
The shares cost A$1.47 at the start of the period, and anyone looking at PolyNovo then had to choose which storyline felt more plausible.
The bullish narrative saw aging populations and chronic wounds as a long runway, with a Fair Value near A$2.65, meaning a price implied by strong assumptions, backed by expectations that NovoSorb products would gain broad, clinician led adoption across trauma, plastics, and new indications.
The bearish view pointed to a Fair Value around A$1.2 based on tighter assumptions, focused on mounting global cost pressures and reimbursement risk that could squeeze premium pricing and keep margins under pressure even if sales kept growing.
What The PolyNovo Results Actually Tested
The clearest datapoint came from PolyNovo’s latest filing. Total revenue moved from A$69.164m in H2 2025 to A$79.522m in H2 2026, which supported the bullish focus on demand and product uptake. Net income slipped from A$9.876m to A$7.338m and net margin moved from 14.3% to 9.2%, which backed the cautious view on pricing pressure and costs. Overall, the evidence cut both ways.
The takeaway travels well. When a thesis leans on premium pricing and operating leverage, you stress test it by tracking revenue against net margin and checking whether higher sales actually translate into stronger profitability.
What Today’s PolyNovo Share Price Seems To Be Asking
PolyNovo now trades at A$0.91, while the selected Narrative’s Fair Value sits above the current price according to its own modelling. That view leans on an argument that the business is broadening its reach and mix rather than relying on a single wound product or geography.
The drop of 39.5% over the past year forces a sharper question. A buyer today would need to believe that international expansion, manufacturing investment and new indications for NovoSorb can offset regulatory, reimbursement and concentration risks over time.
"Broadening of the product portfolio with MTX and pipeline innovations (e.g., hernia mesh), as well as expanding indications (chronic wounds, plastics, trauma), reduces concentration risk and allows PolyNovo to target a larger addressable market, leading to long-term diversification of revenue sources and improved earnings stability."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond PolyNovo’s Wounds
PolyNovo asks you to think about wound repair and soft tissue. One step away, surgeons still need tools that make those procedures possible.
Hospitals look for devices that help treat chronic disease, guide surgery and monitor recovery. A large medical technology player focuses its energy on that need.
It supplies hardware and software used in cardiac care, brain and spine procedures and soft tissue surgery. Those systems aim to make interventions more precise and predictable.
As chronic conditions keep patients in operating rooms, demand for these technologies can evolve. The broader toolkit could reshape who captures value in advanced procedures.
That argument has a Narrative and a number behind it. → See the company one Narrative values 21% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com