


Learn Why The Bull Case For Paymentus Holdings (PAY) Could Change Following Raised Guidance
- Paymentus Holdings recently reported exceptionally strong Q2 results, with revenue growth outpacing diversified financial services peers and management lifting full year guidance.
- The combination of rapid top line expansion and the highest guidance raise among peers highlights how Paymentus’ platform is scaling across multiple end markets.
- We will now explore how Paymentus Holdings’ investment narrative is affected by its raised guidance after exceptionally strong recent quarterly results.
Scan Paymentus Holdings’ performance alongside hand-picked peers by running your filters against our 19 high quality undiscovered gems for fast growing platforms that the market may be underpricing.
Paymentus Holdings Investment Narrative Recap
For Paymentus Holdings, the core belief is that digital bill payment volumes will keep deepening across utilities, finance, healthcare and other recurring billers, and that its cloud platform can capture a meaningful share of that activity. The latest quarter, with strong revenue and a raised full year outlook, supports the idea that the operating model is scaling across billers and channels.
The near term swing factor is whether that momentum in bookings and transaction volumes holds up while Paymentus manages pricing pressure from large enterprises. The key risk remains margin compression as bigger clients seek discounts and as compliance, data security and potential open banking alternatives add costs or cap pricing power.
The most relevant recent update is the Q2 report itself. Paymentus Holdings delivered revenue that exceeded analyst expectations and management raised full year guidance, which was the largest guidance lift among its diversified financial peers. That combination points to healthy demand from billers using its omnichannel, cloud based payment platform.
Investors watching catalysts may focus on how this higher guidance interacts with existing concerns around valuation, client concentration and competition from banks, fintechs and big tech. Stronger near term execution can support the view that Paymentus can use its scale, integrations and automation efforts, including agentic AI, to offset volume discounts, manage regulatory costs and align earnings with the trajectory currently reflected in analyst forecasts.
Paymentus Holdings' current narrative assumes revenue reaches $2.1b and earnings climb to $164.5 million by 2029, based on analysts forecasting 16.4% yearly revenue growth and an earnings increase of about 94% from $84.9 million today.
Uncover why Paymentus Holdings' fair value indicates a 30% potential upside to its current price that could narrow quickly.
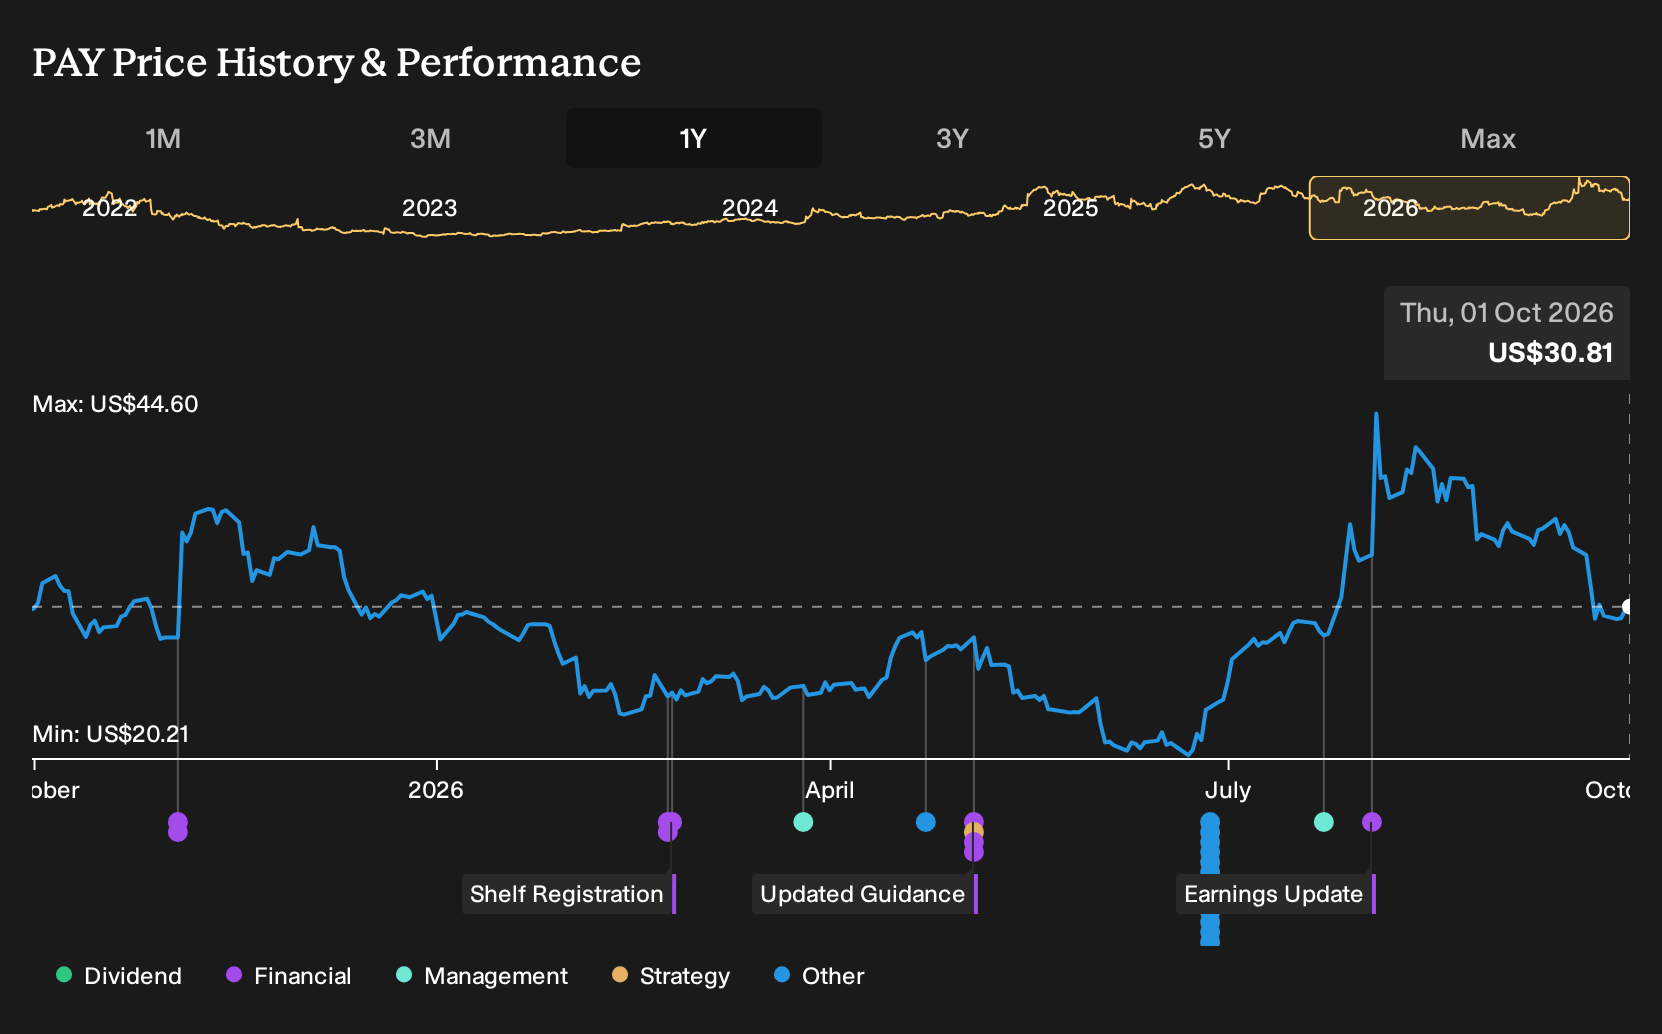
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community are on record for Paymentus Holdings, stretching from about $5.87 to $40 per share. That wide gap shows how differently private investors frame upside and risk. Before the Q2 surprise, some already flagged margin pressure and enterprise discounting as potential brakes on future performance.
Explore another Paymentus Holdings fair value estimate, including one that suggests there may be as much as 30% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Paymentus Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Paymentus Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paymentus Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Paymentus Holdings?
If Paymentus Holdings has sharpened your thinking about growth, risk and valuation, you can apply that same lens to a wider watchlist. The Simply Wall St screener lets you filter by balance sheet strength, income reliability or potential mispricing so you can build a line up that fits your goals.
- If capital preservation is high on your list, start with a basket of 31 resilient stocks with low risk scores that score well on resilience and consistency.
- For investors who care about steady income streams, scan a curated set of 7 dividend fortresses that pair higher yields with sustainability checks.
- If you want to look for potential mispriced opportunities beyond the usual tickers, sort through our 28 high quality undervalued stocks and see which businesses may warrant a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com