


DLocal (DLO) Expands Payment Options, Is It Still 73% Undervalued?
Cooling inflation data and steady consumer spending have pushed payment volumes into focus, putting DLocal (NasdaqGS:DLO) and its emerging market platform squarely on the radar for transaction driven investors.
Recent trading tells a mixed story. At a share price of US$13.73, DLocal has seen its 30 day share price return decline 7.42%, with the 90 day move down 7.73%. However, the 1 year total shareholder return is only down 0.47%, hinting at cooling short term momentum on top of a much steeper 5 year total shareholder return decline of 74.55%.
Scan other payment processors and fintech platforms with similar transaction driven potential using our hand picked 19 high quality undiscovered gems alongside DLocal.
DLocal keeps signing up merchants and expanding payment options, yet the share price has drifted this year. Are you looking at a strong franchise that is temporarily marked down, or a business already fairly priced for its potential?
Most Popular Narrative: 73% Undervalued
On valuation, the current DLocal share price of $13.73 sits well below a widely followed fair value estimate of $50.96, which frames a very different picture from the recent share price drift.
DLocal trades below the value implied by discounting its own free cash flow. Using a two-stage model running 10 years of +25.0% growth fading to a 2.5% terminal rate, discounted at 9.8%, the shares are worth USD 50.96 against a market price of USD 15.24, a 70% discount, or +234% to fair value. 58% of that value sits in the terminal period, which is the honest caveat: the further out the cash flow, the more the answer is a statement about assumptions rather than about this year. The business earns 37.0% on invested capital on a 20.7% operating margin struck against 36.6% gross margins. Of USD 1.09B in trailing revenue, 40.0% converts all the way to free cash flow, and the balance sheet carries debt at 0.16 times equity, in fact a net cash position of USD 733.78M, which buys the time a levered peer would not have.
See why 6 investors see DLocal as 73% undervalued.
According to J_Tyrader, this free cash flow framework argues that most of the implied value in DLocal comes from cash generation well beyond the next few years, which puts a lot of weight on how long its current economics can be sustained.
Result: Fair Value of $50.96 (UNDERVALUED)
Still, two pressure points could upset the DLocal story: any slowdown in its emerging market volume growth, and sharper competition compressing its payment economics.
Find out about the key risks to this DLocal narrative.
Another View On DLocal’s Valuation
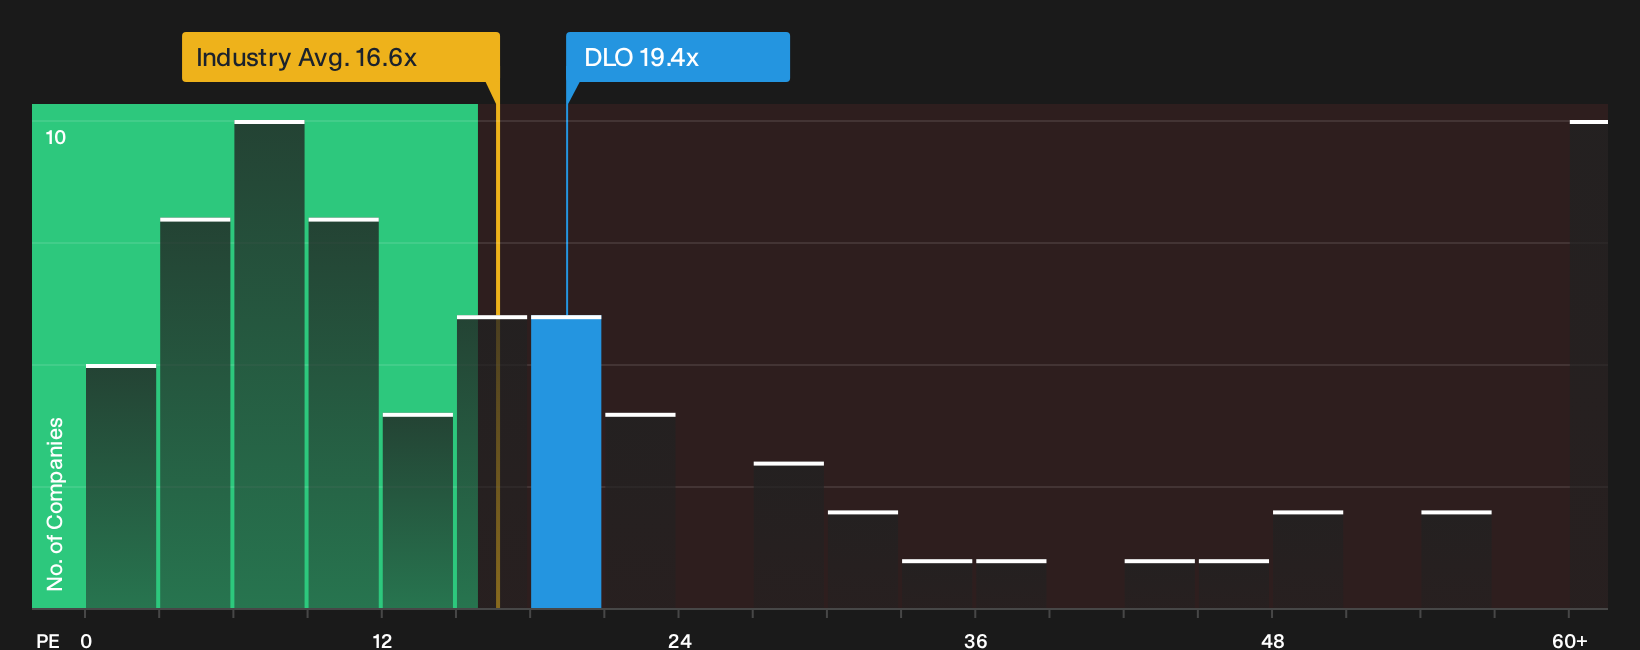
Multiples tell a cooler story than the punchy cash flow case. DLocal trades on a P/E of 19.4x, richer than the US Diversified Financial industry on 16.6x and also above a fair ratio of 15.6x that the market could move toward, yet below a 36.5x peer average. Is this a quality premium that endures or a valuation gap that eventually closes?
See what the numbers say about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the valuation debate around DLocal feels divided, take that as a signal to review the underlying data yourself and carefully weigh the 4 key rewards.
Looking for more DLocal sized ideas?
If you only stop at DLocal, you risk missing other opportunities. Let the data do the heavy lifting and widen your opportunity set with a few focused screens.
- Target income first and stress test your cash flow plan against steady payers through the 7 dividend fortresses.
- Hunt for mispriced quality and see what rises to the top in the 28 high quality undervalued stocks.
- Focus on resilience and protect the downside by filtering for sturdier balance sheets with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com