


5% Undervalued? Freeport McMoRan (FCX) After Reaffirming Its Capital Return Policy
Freeport-McMoRan (FCX) just reaffirmed its performance-based capital return policy, with the Board declaring a total cash dividend of $0.15 per share that combines a base payout and a variable component.
Freeport-McMoRan’s reaffirmed dividend policy lands after a strong run, with the share price up 33.41% year to date and the 1-year total shareholder return at 80.15%, even as the 30-day share price return has eased 4.40%. This suggests powerful longer-term momentum with some recent cooling as investors reassess valuation risk around its premium P/E and Indonesian smelter ramp up.
Scan how Freeport-McMoRan compares with other copper focused miners by running a curated list of potential peers through the 17 top copper producer stocks today.
Freeport-McMoRan now couples a premium P/E with a cooling share price after a steep run. Does that recent pause reset the odds in favor of new buyers, or signal a stretched valuation that limits upside from here?
Most Popular Narrative: 5% Undervalued
Freeport-McMoRan’s most followed narrative points to a fair value of $72.59 against a last close of $69.28. This frames the recent pullback as a modest discount rather than a clear warning signal.
Freeport's new Indonesian smelter, starting up ahead of schedule and expected to reach full capacity by year-end, will make the company a fully integrated global copper producer. This is expected to lower operating costs, capture more downstream value, and reduce exposure to export duties, directly supporting higher future margins and cash flows.
See why 106 investors see Freeport-McMoRan as 5% undervalued.
Result: Fair Value of $72.59 (UNDERVALUED)
Still, the Freeport-McMoRan story hinges on sensitive levers, especially long term Indonesian policy risk and any reversal in the current U.S. copper tariff premium.
Find out about the key risks to this Freeport-McMoRan narrative.
Another View On Freeport-McMoRan’s Value
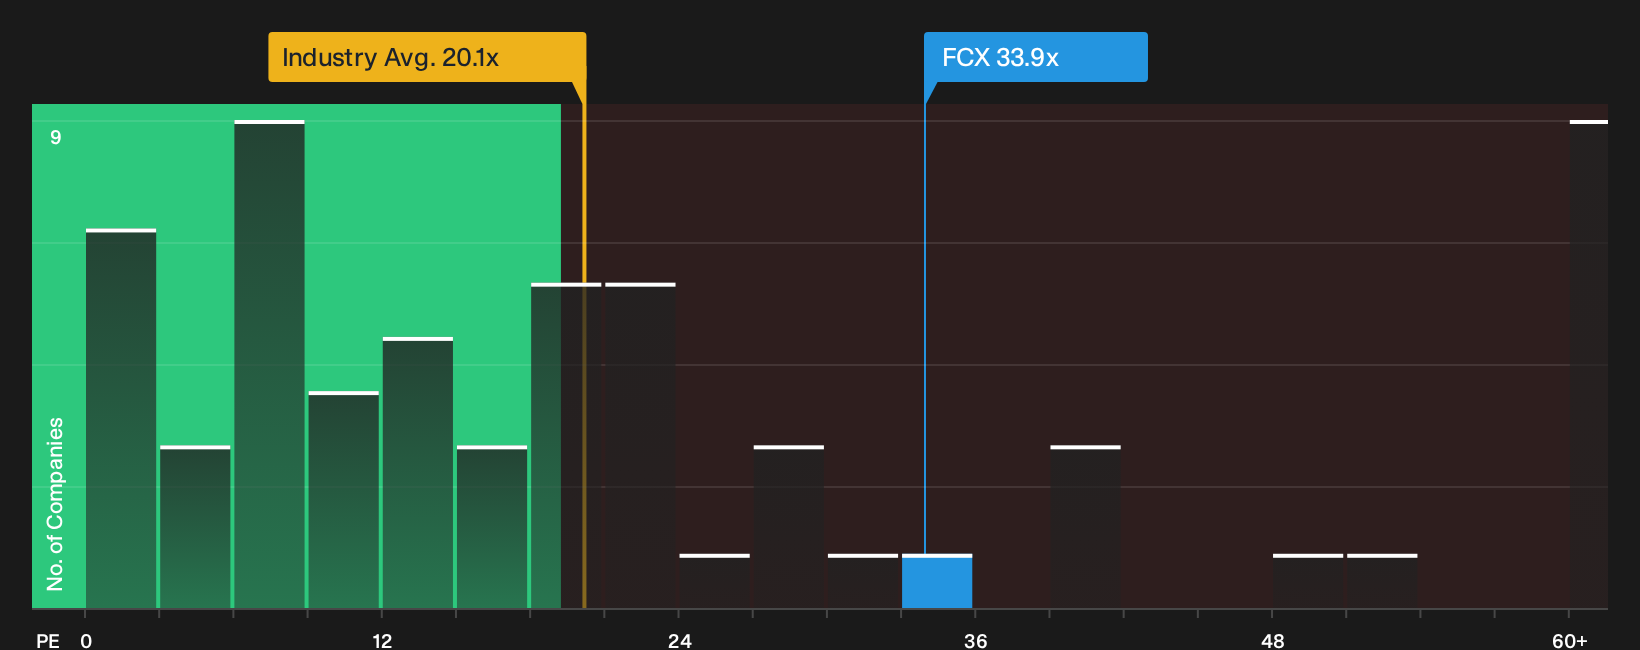
Analysts see Freeport-McMoRan as modestly undervalued around $72.59, yet the current P/E of 33.9x tells a tougher story. That multiple sits well above the US Metals and Mining sector at 20.1x and the fair ratio of 24x, which points to meaningful valuation risk if sentiment cools.
See what the numbers say about this price by reviewing the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed message or balanced setup for Freeport-McMoRan investors. If you want to move quickly and build your own view from the ground up, start with the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Freeport-McMoRan?
If Freeport-McMoRan has sharpened your interest in resource and income plays, do not stop there. Use the Simply Wall St screener to spot fresh opportunities early.
- Target resilience first and focus on companies with sturdier financial footing by zeroing in on a list of solid balance sheet and fundamentals (25 results).
- Hunt for value and seek businesses that combine strong fundamentals with appealing pricing through a curated 19 high quality undiscovered gems.
- Prioritise stability and aim for candidates with more defensive characteristics using a 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com