


Weyerhaeuser (WY) Stock Looks Reasonable Despite Its 37% Slide
Weyerhaeuser has seen a long slide in its share price, and that raises a simple but important question for investors who still care most about earnings. Are you paying a fair price for this stock given what the business is actually making today?
- Over the past 5 years, Weyerhaeuser has fallen about 36.9%. This puts the spotlight squarely on whether the current valuation is still anchored to its earnings power.
- The group’s real estate and timber operations tie its profitability closely to lumber demand and wood product pricing, so shifts in those markets can quickly change how its earnings support the present share price.
- Your read on Weyerhaeuser is one view; the desks covering it have another. See what analysts think Weyerhaeuser's shares could be worth.
The issue now is whether Weyerhaeuser’s recent share price reflects a reasonable multiple of the earnings investors can expect from the business.
If you are weighing whether Weyerhaeuser’s recent slide leaves better value elsewhere, it can help to compare its earnings profile with companies in the 28 high quality undervalued stocks
Does Weyerhaeuser Look Undervalued on Earnings?
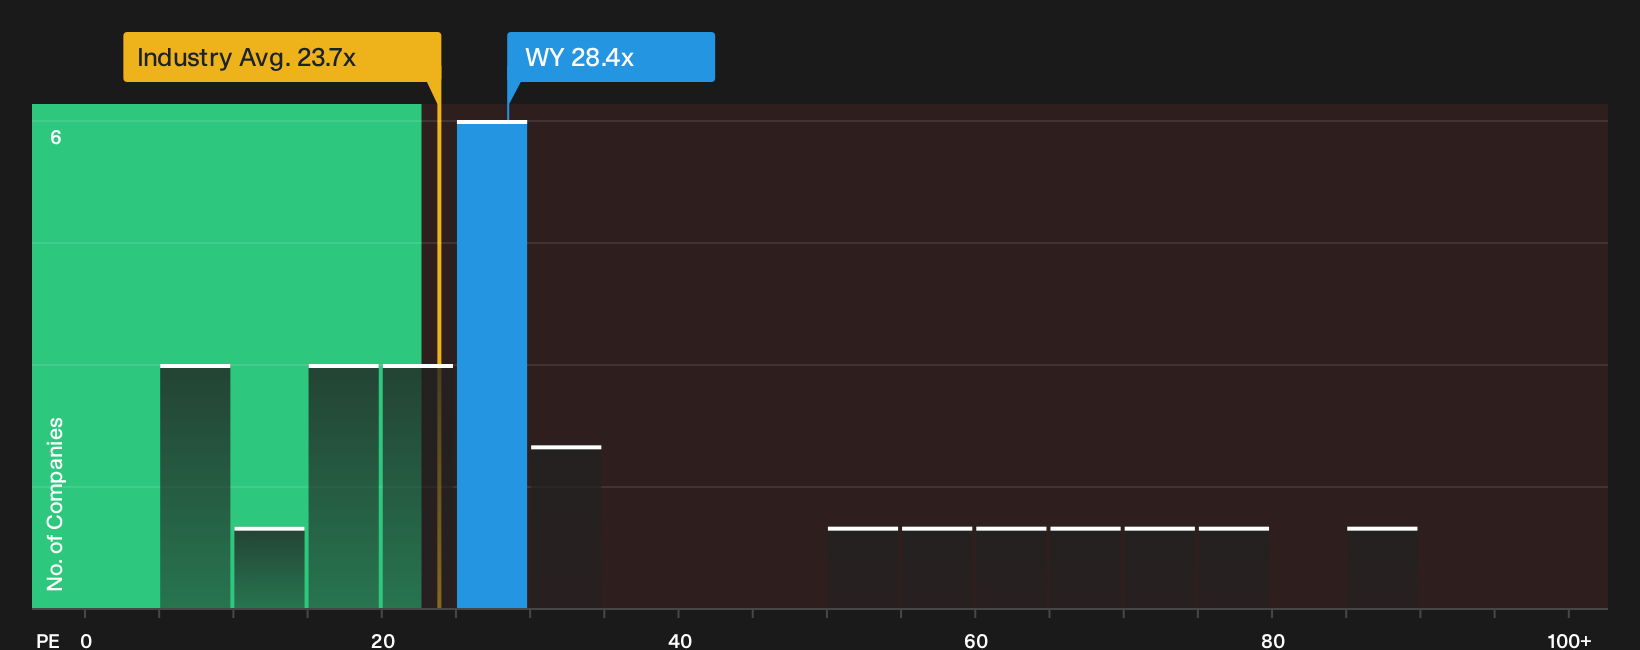
P/E fits Weyerhaeuser because earnings remain the main lens most investors use for a mature, income oriented real estate and timber group. The stock currently trades on a P/E of 28.4x, which is above the Specialized REITs industry average of 15.7x. That gap indicates the market is willing to pay more for each dollar of Weyerhaeuser earnings than for the typical sector peer.
The company also trades below a more tailored P/E level implied by its own fundamentals and risk profile, so the current multiple screens as undervalued against that customised yardstick rather than the raw sector mean. Compared with a peer group average of 31.5x, the valuation sits at a discount to similar businesses on this earnings metric, which leaves the share price looking lower than both that peer reference and the model driven fair range. Explore the numbers behind Weyerhaeuser's P/E valuation.
The Weyerhaeuser Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Weyerhaeuser pick up where that valuation puzzle leaves off and explain which future for Weyerhaeuser's earnings, margins and growth would need to occur for the current P/E to appear too low or too rich. Rather than giving only a single figure from a ratio or model, they unpack the business assumptions that number rests on so you can track over time whether those conditions still hold on the Community page.
One of the top community narratives on Weyerhaeuser: 40% undervalued
"The current valuation implies that the market is not fully pricing in the potential cash generation from Weyerhaeuser’s targeted 75 to 80% Adjusted FAD capital return framework…"
Discover why this Narrative puts Weyerhaeuser at 40% undervalued.
One more piece of the Weyerhaeuser puzzle worth checking
Before you move on from Weyerhaeuser, it is worth asking who is actually steering the business and how their incentives line up with your interests as a shareholder. See who runs Weyerhaeuser and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com