


Peloton Interactive (PTON) Is Back In The Spotlight, What Is Driving Attention Now?
Peloton Interactive (PTON) just rolled out three new treadmills and fresh Peloton IQ software features, pairing an accessibly priced folding model with higher end, computer vision equipped gear for runners and walkers.
Peloton Interactive’s latest treadmill launch comes after a tough stretch for the stock, with the share price down 18.79% year to date and the 1-year total shareholder return falling 42.74%. However, the 7-day share price return of 3.76% hints at tentative positive momentum building around the new product story.
Spot similar fitness and AI coaching stories in our hand picked list of 37 profitable AI stocks that aren't just burning cash.Peloton Interactive trades at a steep gap to both its own history and the current analyst target of US$7.90, with the stock at US$4.97 after the recent bump. Does that discount still reflect the business, or has the launch shifted where fair value really sits?
Most Popular Narrative: 37% Undervalued
Peloton Interactive’s most followed valuation story points to a fair value of $7.88 against the last close at $4.97, which puts the fresh treadmill and software launch against a stock that screens as materially cheaper than that narrative estimate.
Peloton is leveraging advanced technologies, including AI-powered personalized coaching and human-driven community features, to broaden its offerings from cardio into holistic wellness (strength, sleep, stress, nutrition). This aligns with growing global health consciousness and is expected to support future subscription revenue growth and higher engagement and churn reduction.
See why 24 investors see Peloton Interactive as 37% undervalued.
That widely followed view uses an 8.9% discount rate and arrives at a fair value of $7.88 per share, compared with Peloton Interactive’s current market value of about $2.2b and a share price that is still well below both the narrative estimate and the $7.90 analyst target. The result is a 36.9% discount to that fair value, which leaves a wide gap that hinges on the same themes driving the new product cycle, including subscription engagement, AI coaching adoption and the balance between hardware sales and membership earnings.
Result: Fair Value of $7.88 (UNDERVALUED)
Still, Peloton Interactive’s narrative could be knocked off course if competition continues to pressure subscriptions or if further guidance resets undercut confidence in earnings power.
Find out about the key risks to this Peloton Interactive narrative.
Another View: Peloton Interactive Through The P/E Lens
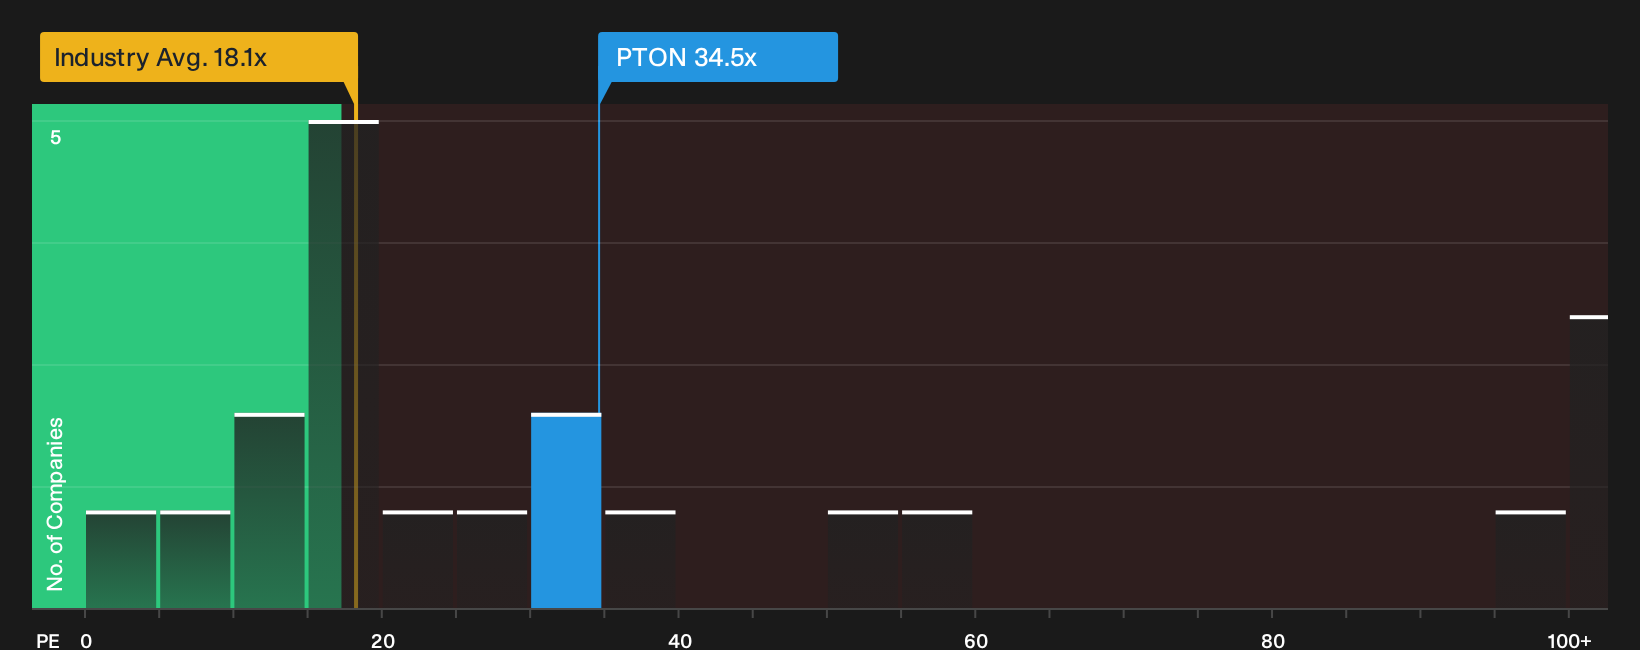
Peloton Interactive looks very different when you swap the story-based fair value for the simple P/E check. The stock trades on 34.5x earnings, compared with 17.8x for the global Leisure industry, 20.2x for peers, and a fair ratio of 24.8x. That points to a valuation that leans expensive rather than cheap. So the bigger risk may now be overpaying for the turnaround story, rather than underappreciating it.
To see what the numbers say about this price, read the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Peloton Interactive so far. If you want to move quickly and form your own view, start with the full picture of 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Peloton Interactive?
If Peloton Interactive has caught your attention, do not stop there. Use the same disciplined approach to size up other opportunities that could fit your portfolio.
- Target potential upside in beaten down stories by scanning 19 high quality undiscovered gems that pair quality fundamentals with limited market attention.
- Protect your downside first and hunt for resilience using a 31 resilient stocks with low risk scores that focuses on businesses with more stable risk profiles.
- Prioritize financial strength and filter for durability through a list of solid balance sheet and fundamentals (25 results) that highlights companies with cleaner debt and liquidity positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com