


Electra (TASE:ELTR) Joins FTSE All World As Valuation Questions Grow
Electra (TASE:ELTR) has been added to the FTSE All-World Index in US dollar terms, a move that can draw fresh attention from index-tracking funds and broader global investors.
Recent trading has been mixed, with Electra’s share price down about 9% over the past month and 7% over the last quarter. However, total shareholder return over the past year is 16.68%, suggesting long term holders have still seen meaningful gains as interest builds around the index inclusion.
Compare Electra’s index inclusion with other construction and infrastructure players by reviewing the hand picked list of solid balance sheet and fundamentals (207 results).
Electra looks like a solid contractor with years of built out operations and fresh index attention, yet the recent share pullback raises a sharper question. Is that quality on offer at a fair price today?
Price-to-Earnings of 44.1x: Is it justified?
On the numbers, Electra trades on a P/E of 44.1x against the IL Construction industry at 34.4x, so the market is currently paying a richer price for each shekel of earnings than for many local peers. That sits awkwardly beside our SWS DCF model output, which estimates a fair value of ₪286.76 per share versus a last close of ₪111.7, implying the shares change hands at about a 61% discount to that cash flow based estimate.
The P/E ratio compares the current share price with earnings per share and is a quick way to see how much investors are willing to pay for current profitability. For a contractor like Electra, that multiple often reflects how durable investors think the project pipeline and margins are, especially in sectors such as construction and infrastructure where cycles and contract timing can move profits around.
There are some important tensions inside the earnings profile. Reported net income over the last twelve months includes a sizeable one off gain of ₪66.0m, which inflates the profit base that the 44.1x multiple is built on. At the same time, earnings have declined by about 4.5% per year over the past 5 years and fell 11% over the most recent year, while return on equity sits at 10.1%, which is described as low by the methodology used here.
That context makes the valuation bridge tricky. Compared with the IL Construction industry average P/E of 34.4x, Electra screens as expensive on a simple sector comparison. However, relative to a narrower peer set with a 97.8x average, its 44.1x P/E is classed as good value. Adding the SWS DCF model estimate of ₪286.76 per share into the mix gives a stock trading at ₪111.7 that screens as expensive versus the sector on earnings, yet heavily discounted versus an internal cash flow model that treats future cash generation far more generously.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 44.1x (ABOUT RIGHT)
Still, Electra’s rich P/E, recent share price declines over 1 and 3 months, and reliance on one-off income gains could quickly flip sentiment if project activity softens.
Find out about the key risks to this Electra narrative.
Another view on Electra’s value
On one hand, the SWS DCF model suggests Electra could be worth about ₪286.76 per share, which is far above the current ₪111.7 price. On the other hand, earnings have declined over 5 years, interest cover is weak, and results relied on a ₪66.0m one off gain. Which signal do you treat as more important?
Look into how the SWS DCF model arrives at its fair value.
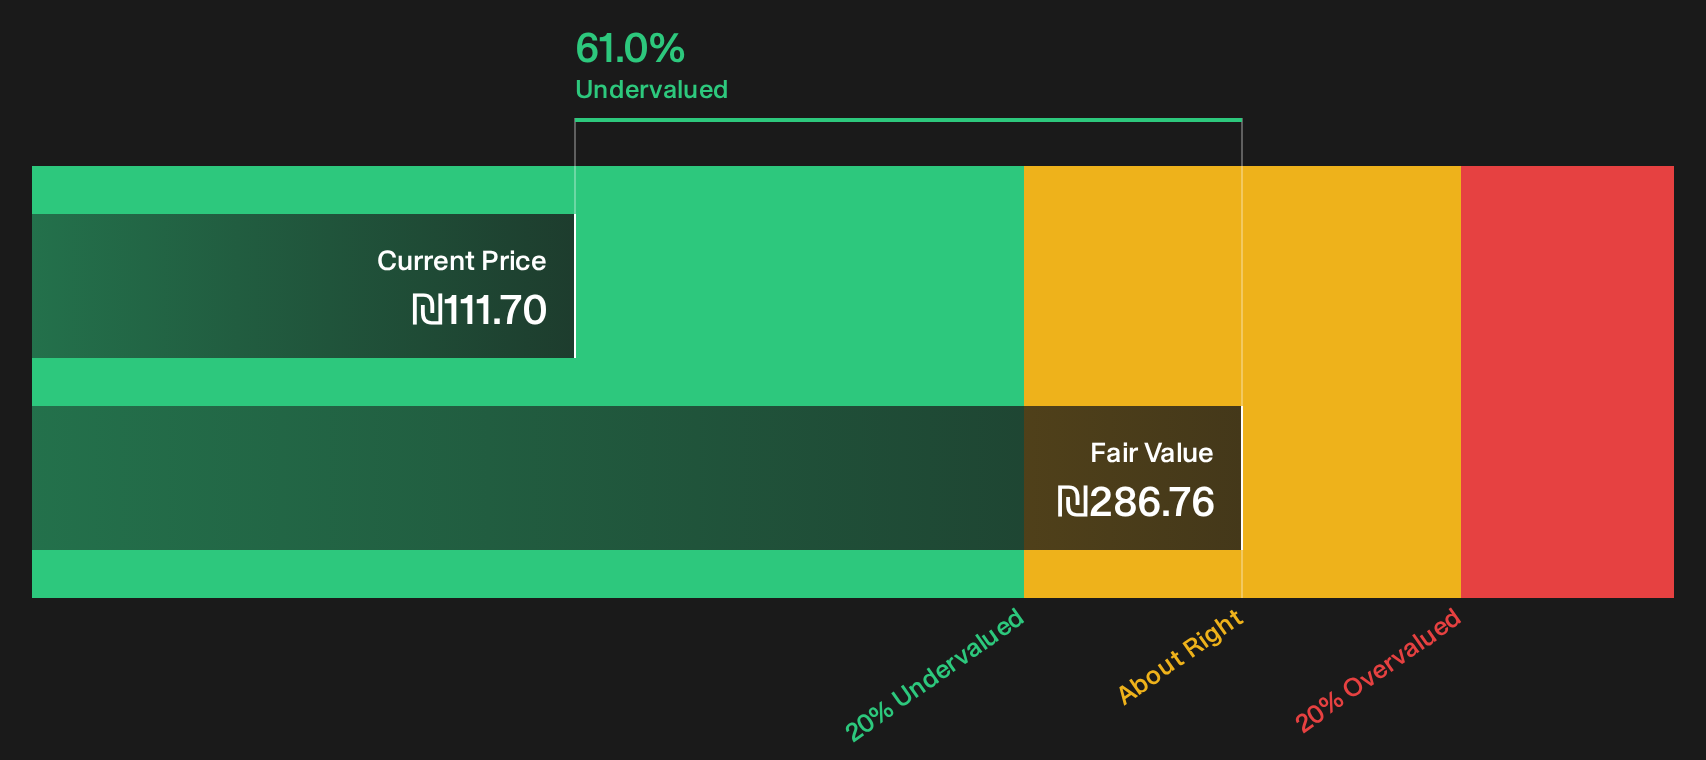
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Electra for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Electra can feel confusing, especially with both risks and rewards in play. Act quickly, review the numbers yourself, and then weigh the 1 key reward and 4 important warning signs.
Want more ideas beyond Electra?
If Electra has sharpened your valuation instincts, do not stop here. Use the Simply Wall St Screener to spot fresh opportunities that fit your style.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive price tags through the 190 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies with robust payouts and yields using the 159 dividend fortresses.
- Lower portfolio stress by concentrating on businesses that carry resilient financial profiles via the 224 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com