


Humana (HUM), Why Is It Back In The Spotlight?
Humana (HUM) just outlined its 2027 Medicare Advantage lineup, highlighting $0 in-network primary care and labs, dental, vision and hearing benefits, and an expanded footprint for chronic condition special needs plans.
Humana’s latest Medicare Advantage refresh lands after a strong run, with the share price up 43.56% year to date and a 1 year total shareholder return of 49.57%, although the 3 year and 5 year total shareholder returns remain in decline. This suggests recent momentum is building from a weaker longer term base.
Scan for other insurers that are seeking to benefit from the same Medicare Advantage momentum as Humana by reviewing our hand picked list of solid balance sheet and fundamentals (25 results).
Humana has rolled out richer Medicare Advantage benefits and the share price has surged this year. The real tension now is simple: Is a solid healthcare insurer being valued fairly after this run, or not yet?
Most Popular Humana Narrative: 9% Undervalued
Humana’s most followed narrative pegs fair value at $419.04 using a 7.3% discount rate, compared with a last close of $379.68. That gap frames the current Medicare Advantage enthusiasm as only partly reflected in the share price.
The main thing that has to go right is that Humana delivers on its multiyear Medicare Advantage margin and cost-transformation program, including disciplined plan pruning, operating cost ratio reductions, and effective value-based partnerships, while managing regulatory and compliance risks.
The current narrative that Humana is fairly valued and bullish implies the share price already reflects meaningful progress on margin restoration, operating cost efficiencies, and balance sheet optimization with limited room for disappointment if these plans slip.
See why 60 investors see Humana as 9% undervalued.
Result: Fair Value of $419.04 (UNDERVALUED)
Still, this Humana narrative can be knocked off course if Medicare Advantage plan exits reduce member retention more than expected, or if tighter coding and Stars oversight lift compliance costs and pressure earnings.
Find out about the key risks to this Humana narrative.
Another View: Humana Through The P/E Lens
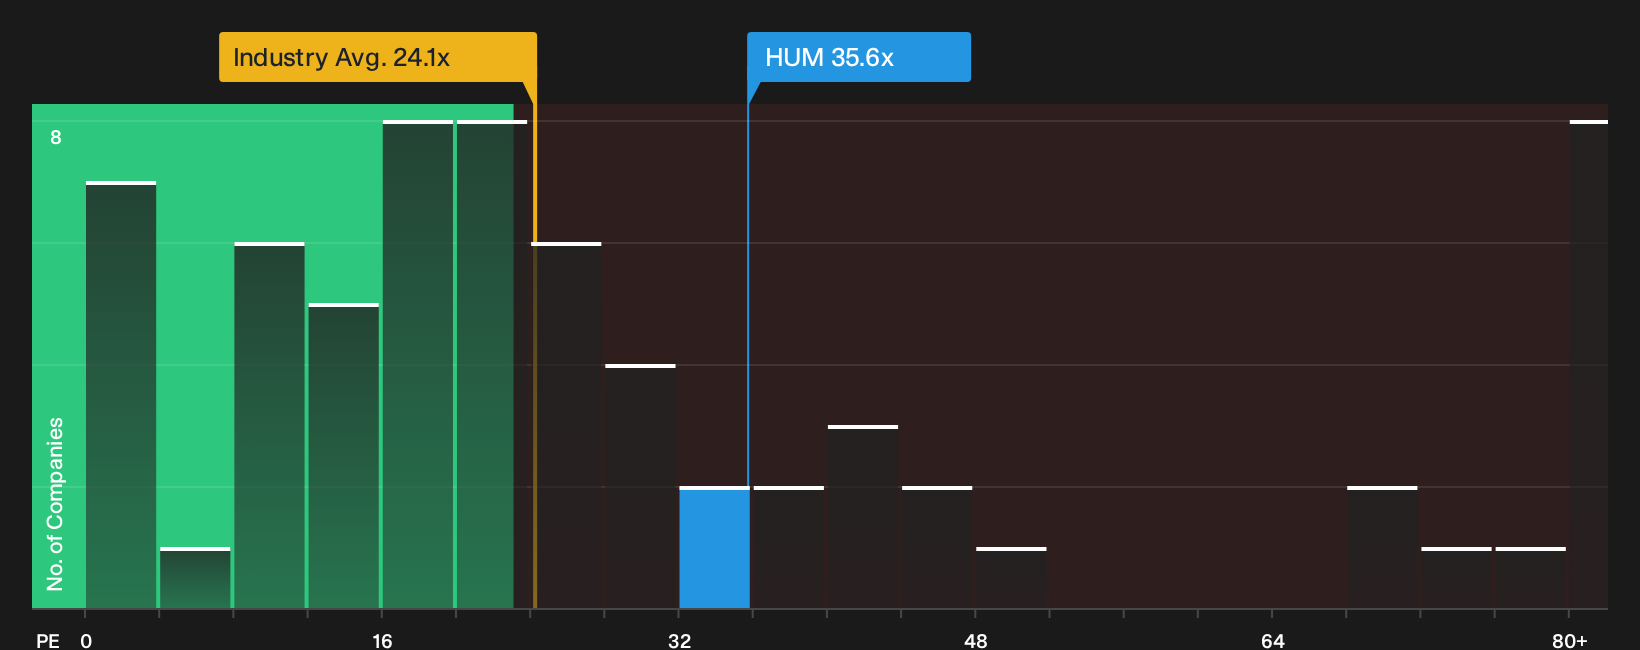
There is a very different picture when Humana is viewed through its current P/E ratio of 35.6x. That level sits well above both the US Healthcare industry on 24.1x and its peer average of 23.8x, yet below a fair ratio estimate of 43.4x that the market could eventually move toward.
This mix of being expensive against sector and peers, but cheap against the fair ratio, points to real valuation risk if sentiment cools, alongside room for upside if the market leans into the fair ratio instead. Which side of that trade off do you think is more realistic?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions on the tone of this Humana debate are mixed. Move quickly, review the underlying numbers and sentiment yourself, then evaluate the 2 key rewards and 2 important warning signs.
Looking For More Humana Investment Ideas?
If the Humana story has you thinking harder about where you put capital next, do not stop here. Broader idea hunting now can reshape your portfolio.
- Target potential mispricing by scanning companies with solid fundamentals and room for a rerating through the 28 high quality undervalued stocks.
- Strengthen your cash flow with payouts that matter by reviewing the income focused 7 dividend fortresses.
- Prioritise resilience and sleep better at night by checking companies screened for stability in the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com