


3 Asian Growth Companies With High Insider Ownership Growing Earnings At 55%
Amidst a backdrop of fluctuating global markets, Asian equities continue to capture investor interest with their potential for growth and innovation, particularly in sectors like technology and manufacturing. In this environment, companies with high insider ownership can be appealing due to the alignment of interests between management and shareholders, potentially enhancing the company's performance as they navigate economic challenges.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Meitu (SEHK:1357) | 23% | 26.7% |
| Meiko Electronics (TSE:6787) | 19.2% | 34.3% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| HUMAN MADE (TSE:456A) | 29.1% | 29.5% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
We'll examine a selection from our screener results.
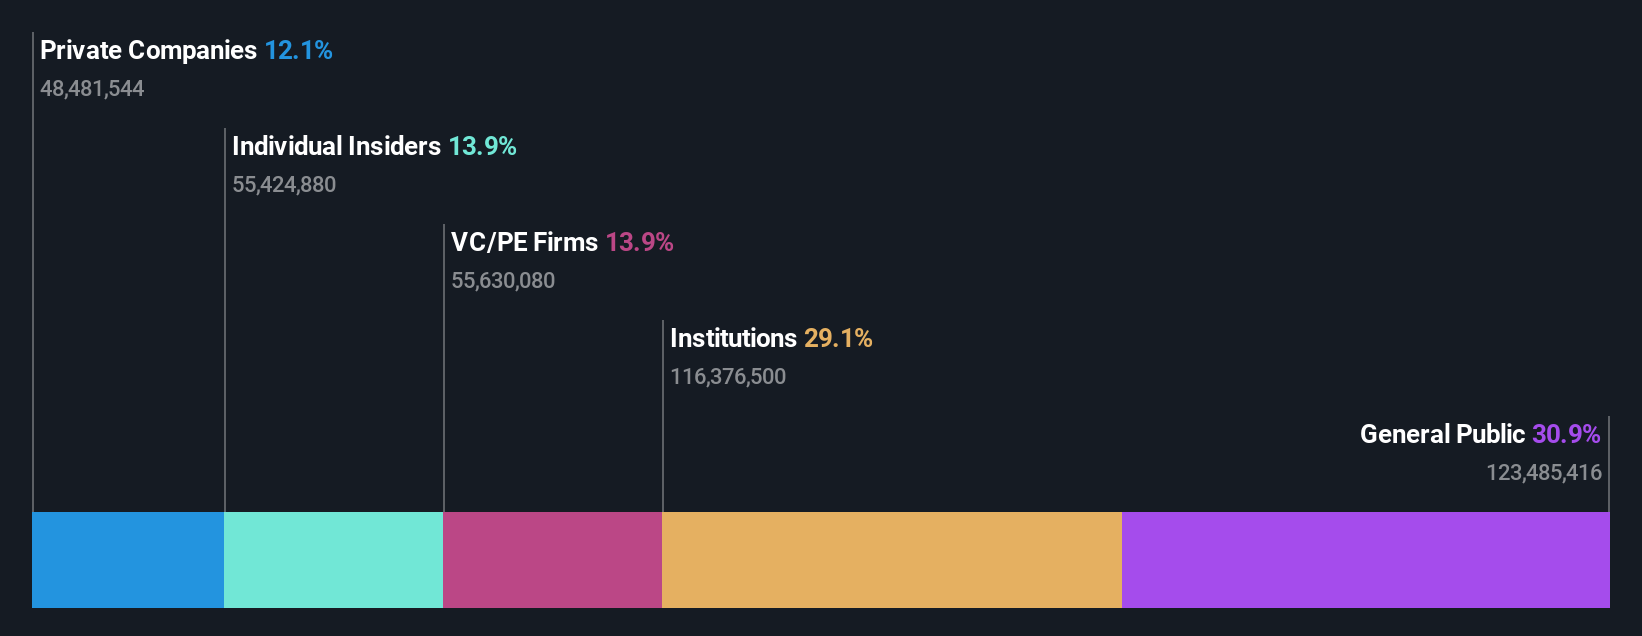
Biocytogen Pharmaceuticals (Beijing) (SEHK:2315)
Simply Wall St Growth Rating: ★★★★★★
Overview: Biocytogen Pharmaceuticals (Beijing) Co., Ltd. is a biotechnology company focused on the research and development of novel antibody-based drugs and pre-clinical research services across China, the United States, and internationally, with a market cap of approximately HK$57.60 billion.
Operations: Biocytogen Pharmaceuticals generates revenue from several segments, including CN¥77.76 million from gene editing, CN¥387.35 million from antibody development, CN¥878.48 million from disease models selling, and CN¥440.53 million from pre-clinical pharmacology and efficacy evaluation.
Insider Ownership: 14.1%
Earnings Growth Forecast: 39.2% p.a.
Biocytogen Pharmaceuticals (Beijing) is experiencing robust growth, with revenue projected to increase at 22.8% annually and earnings anticipated to grow significantly above market rates. Despite recent insider selling, the company's strong proprietary platforms like RenNano and RenLite are driving innovation through strategic partnerships, such as the recent licensing agreement with Qilu Pharmaceutical. The firm's financial performance has strengthened considerably, evidenced by a substantial rise in net income and improved profitability metrics.
- Click to explore a detailed breakdown of our findings in Biocytogen Pharmaceuticals (Beijing)'s earnings growth report.
- According our valuation report, there's an indication that Biocytogen Pharmaceuticals (Beijing)'s share price might be on the expensive side.
Aoshikang Technology (SZSE:002913)
Simply Wall St Growth Rating: ★★★★★☆
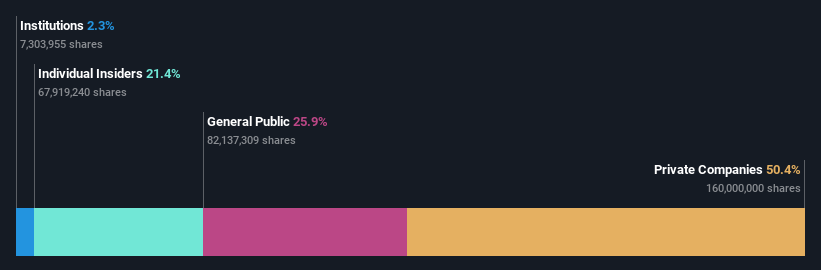
Overview: Aoshikang Technology Co., Ltd. specializes in the research, development, production, and sale of printed circuit boards both in China and internationally, with a market capitalization of CN¥29.03 billion.
Operations: The company's revenue primarily comes from its printed circuit boards segment, totaling CN¥5.85 billion.
Insider Ownership: 19.6%
Earnings Growth Forecast: 55.8% p.a.
Aoshikang Technology is poised for growth with revenue expected to rise 21.9% annually, surpassing the Chinese market average. Despite a decline in profit margins from 6.6% to 3.3%, earnings are projected to grow significantly by 55.8% per year, outpacing the market's 27.2%. Recent financial activities include a CNY 1 billion fixed-income offering and a share buyback program worth CNY 120 million, reflecting strategic capital management despite recent earnings pressure.
- Click here to discover the nuances of Aoshikang Technology with our detailed analytical future growth report.
- The analysis detailed in our Aoshikang Technology valuation report hints at an inflated share price compared to its estimated value.
Money Forward (TSE:3994)
Simply Wall St Growth Rating: ★★★★★☆
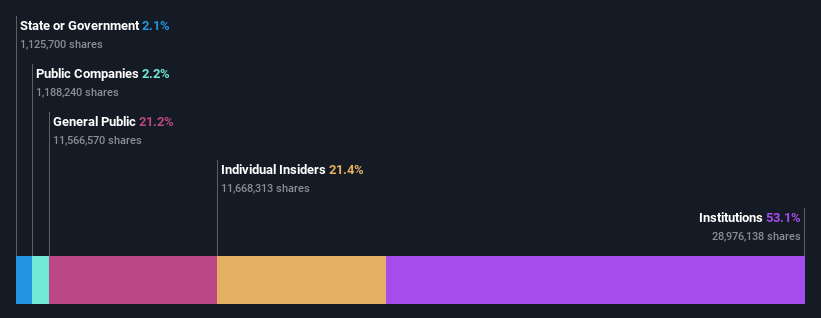
Overview: Money Forward, Inc. offers financial solutions for individuals, financial institutions, and corporations mainly in Japan with a market cap of ¥332.79 billion.
Operations: Revenue Segments (in millions of ¥): Personal Finance Services: ¥5,200; Financial Institution Solutions: ¥9,450; Business Finance Solutions: ¥12,300.
Insider Ownership: 17.6%
Earnings Growth Forecast: 40.5% p.a.
Money Forward's earnings are forecast to grow significantly at 40.5% annually, outperforming the Japanese market average of 9.2%. The company recently revised its financial guidance upwards due to strong performance in its Fintech segment and expected gains from operational investment securities. Despite being dropped from the FTSE All-World Index, Money Forward trades at a substantial discount to fair value and has become profitable this year, although share price volatility remains a concern.
- Get an in-depth perspective on Money Forward's performance by reading our analyst estimates report here.
- Our comprehensive valuation report raises the possibility that Money Forward is priced higher than what may be justified by its financials.
Turning Ideas Into Actions
- Reveal the 501 hidden gems among our Fast Growing Asian Companies With High Insider Ownership screener with a single click here.
- Ready To Venture Into Other Investment Styles? Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 33 best rare earth metal stocks of the very few that mine this essential strategic resource.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com