


Undiscovered Gems In Asia To Watch October 2026
As the Asian markets navigate a landscape marked by fluctuating interest rates and inflationary pressures, small-cap stocks have shown resilience despite broader market volatility. In this dynamic environment, identifying promising opportunities involves looking for companies with strong fundamentals and growth potential that can thrive amid economic shifts.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Management SolutionsLtd | 7.61% | 23.78% | 29.72% | ★★★★★★ |
| Kyosan Electric Manufacturing | 46.17% | 7.20% | 17.51% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| SPRIX | 13.12% | 6.95% | -5.71% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
Here we highlight a subset of our preferred stocks from the screener.
Sing Investments & Finance (SGX:S35)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Sing Investments & Finance Limited offers financing and related nominee services to both individuals and corporations in Singapore, with a market capitalization of SGD364.12 million.
Operations: Sing Investments & Finance Limited's primary revenue stream is derived from its financing business and related nominee services, generating SGD85.99 million. The company's net profit margin reflects its profitability efficiency in managing costs relative to its revenue.
Sing Investments & Finance, a smaller player in the financial sector, has shown promising growth with earnings increasing by 7% annually over the last five years. Despite not outpacing the Consumer Finance industry average, its recent half-year results reported net income of SGD 25.17 million compared to SGD 21.7 million previously. The company trades at a compelling value, 28.6% below estimated fair value and boasts a strong balance sheet with more cash than total debt, while its debt-to-equity ratio improved significantly from 50.9% to just 0.1%. However, free cash flow remains negative despite these positive indicators.

Shenzhen Highpower Technology (SZSE:001283)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Shenzhen Highpower Technology Co., Ltd. focuses on the research, design, development, manufacture, and sale of lithium-ion and nickel-metal hydride (Ni-MH) batteries both in China and internationally, with a market capitalization of CN¥6.05 billion.
Operations: Shenzhen Highpower Technology generates revenue primarily from New Energy Solution Products for Consumer Application Scenarios, amounting to CN¥5.31 billion, and New Energy Solution Products for Energy Storage Application Scenarios, totaling CN¥817.17 million.
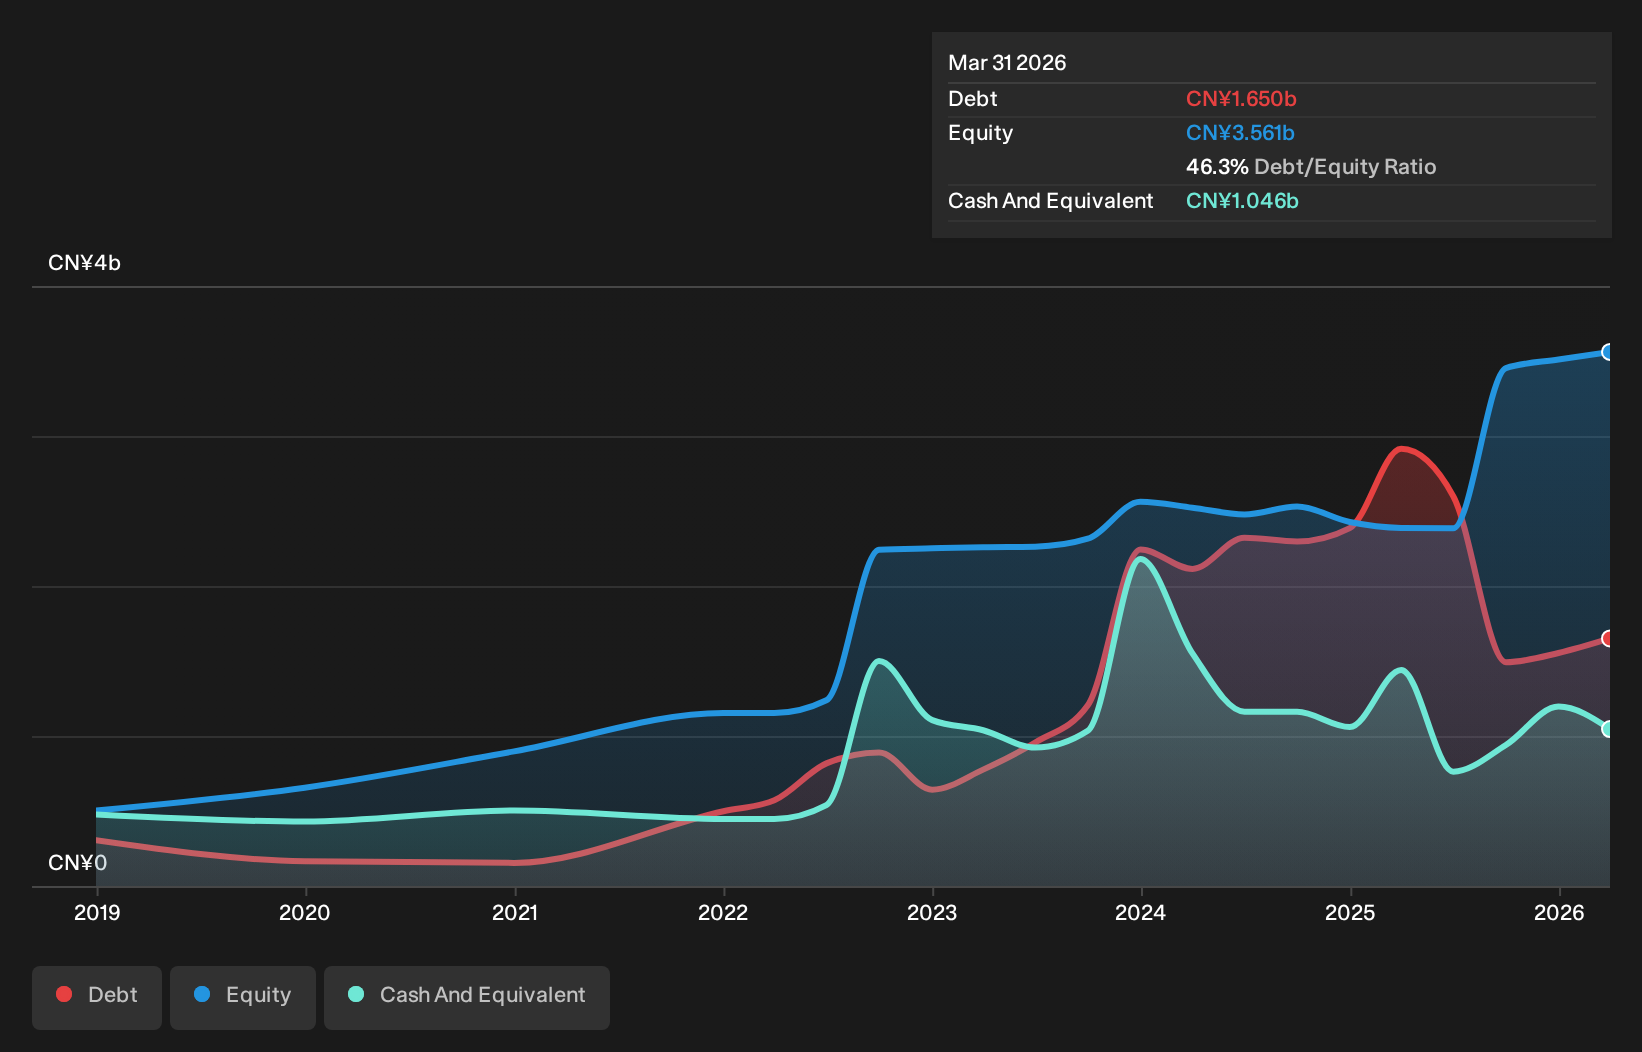
Shenzhen Highpower Technology, with a satisfactory net debt to equity ratio of 32.5%, offers an intriguing profile in the electrical industry. Over the past year, earnings surged 42.8%, significantly outpacing the industry's growth rate of 0.2%. The company trades at an attractive valuation, being 51.6% below its estimated fair value and has high-quality earnings despite not generating positive free cash flow recently. Recent inclusion in the S&P Global BMI Index highlights its growing recognition, while half-year revenue climbed to CNY 3,184 million from CNY 2,762 million last year; however, basic EPS slightly dipped from CNY 0.99 to CNY 0.95 during this period.
Charm Care (TSE:6062)
Simply Wall St Value Rating: ★★★★★☆
Overview: Charm Care Corporation, along with its subsidiaries, offers nursing care services across Japan and has a market capitalization of approximately ¥46.02 billion.
Operations: Charm Care's revenue is primarily derived from its nursing care services in Japan. The company has a market capitalization of approximately ¥46.02 billion, reflecting its position in the industry.
Charm Care, a smaller player in the healthcare sector, has demonstrated robust performance with earnings surging 37.8% over the past year, outpacing the industry average of 3.9%. The company is trading at a value 20.1% below its fair estimate and boasts high-quality earnings with interest payments well-covered by EBIT at 97.7 times. Recent announcements indicate an increase in dividends to JPY 24 per share for the second quarter, up from JPY 17 last year, reflecting confidence in future prospects as they project net sales of JPY 51 billion and operating profit of JPY 5.97 billion for the fiscal year ending June 2027.

Turning Ideas Into Actions
- Unlock more gems! Our Asian Undiscovered Gems With Strong Fundamentals screener has unearthed 112 more companies for you to explore.Click here to unveil our expertly curated list of 115 Asian Undiscovered Gems With Strong Fundamentals.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com