


Does New CFO Appointment Change The Bull Case For Mercialys Stock (ENXTPA:MERY)?
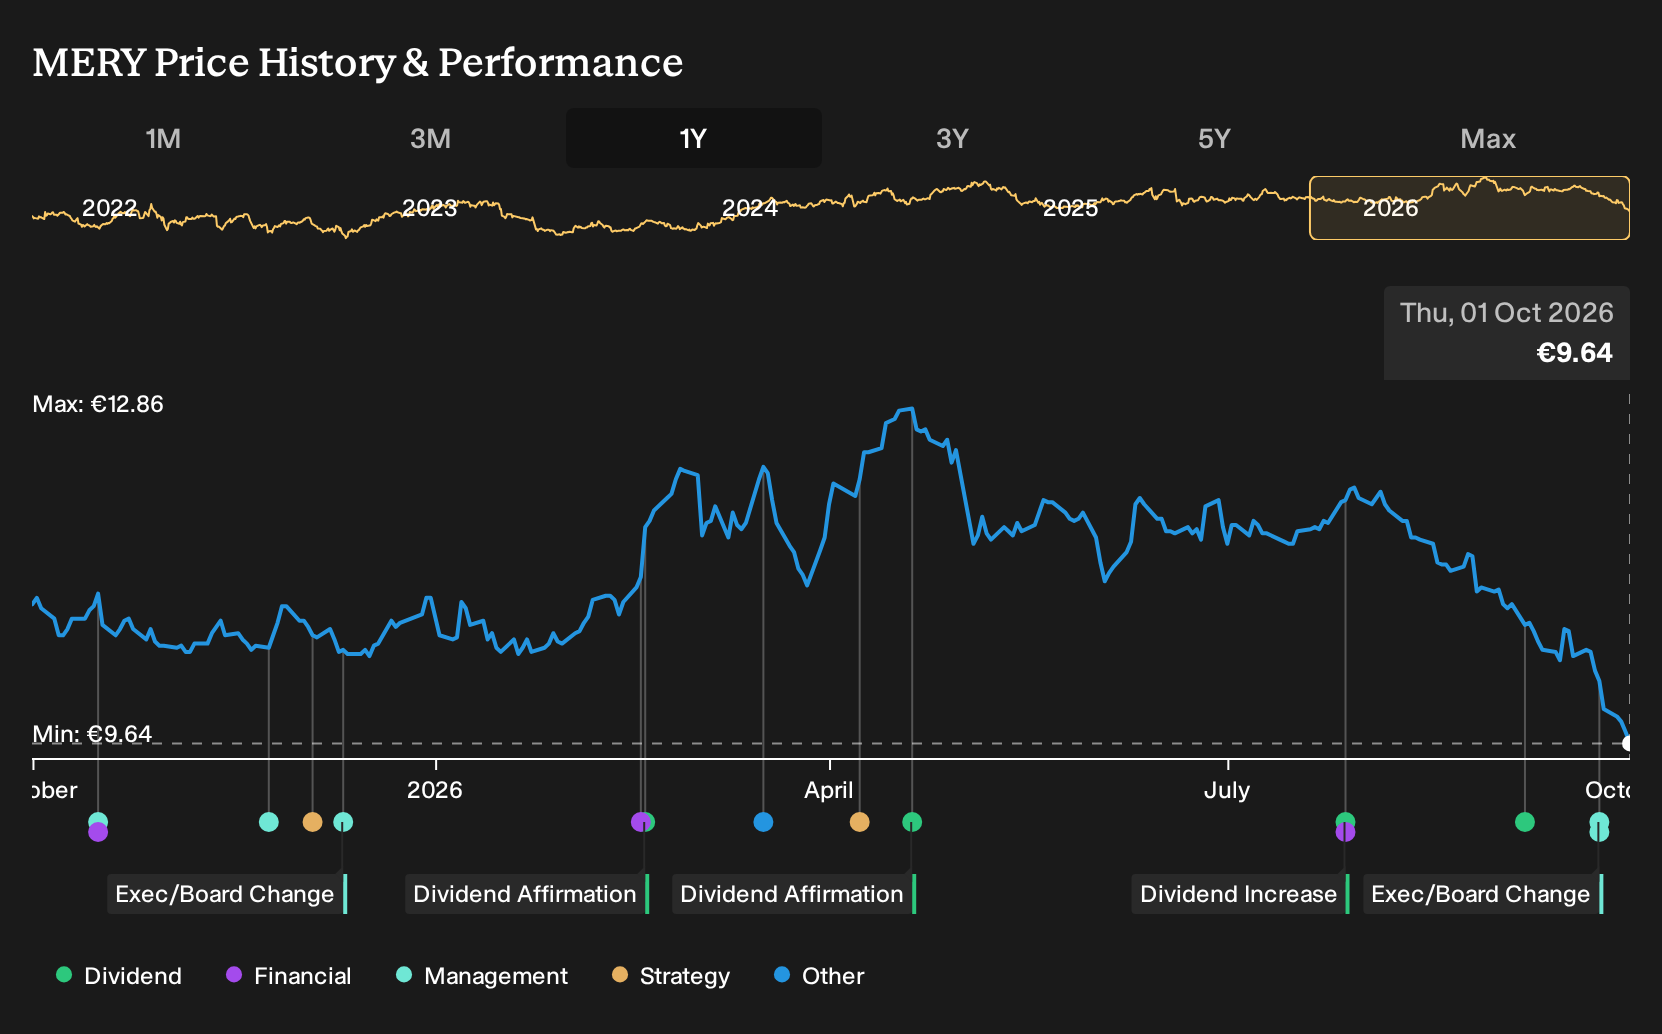
- Mercialys has appointed Jérôme Engelbrecht as Group CFO and Executive Committee member, effective 1 September 2026. He will be responsible for all finance functions and investor relations after nearly twenty years in corporate finance and French real estate.
- The hire brings experience from Proudreed, Icade, Gecina and KPMG directly into Mercialys' capital structure, funding and planning decisions. This background is highly relevant for a business focused on disciplined financial execution and asset recycling.
- We will look at how Mercialys' investment narrative around disciplined growth and capital allocation is affected by Engelbrecht's arrival as CFO.
Scan for other real estate groups that are putting experienced CFOs at the center of their capital plans with our curated list of solid balance sheet and fundamentals (207 results).
Mercialys Investment Narrative Recap
To own Mercialys, you need to believe its French retail assets can stay relevant as shopper habits change, while the balance sheet remains under control. The near term story still turns on filling and reshaping units left by weaker anchors and keeping occupancy and rents resilient against e commerce pressure. Engelbrecht’s arrival does not alter that core bet.
Where the new Group CFO can matter is in execution on funding and capital recycling. Interest cover is already tight and loan to value is elevated, so the biggest operational risk is misjudged leverage or capex. The key short term catalyst remains clear delivery on retenanting and asset repositioning plans.
The most directly relevant announcement is the combined move to appoint Jérôme Engelbrecht as Group CFO and to the Executive Committee from 1 September 2026. That puts one person in charge of financing, planning and investor dialogue at a time when Mercialys is leaning on portfolio refocusing, digital tools and asset recycling to support earnings forecasts.
With interest payments not well covered by earnings and a recent year marked by one off losses and lower margins, the execution bar for the finance function is high. Engelbrecht’s background in financing, treasury and business plans at large French real estate groups may help the company align funding, recycling and investment decisions with its main operational catalysts and risk constraints.
Mercialys' current analyst script points to revenues of €205.7 million and earnings of €116.4 million by 2029, which would imply 4.4% yearly revenue growth and an earnings increase of about €82.4 million from €34.0 million today.
Uncover how Mercialys' fair value indicates a 43% potential upside to its current price before the market closes the discount.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket Mercialys between €13.78 and €20.07 per share, which is a wide spread for such a small sample. That gap reflects how differently retail investors weigh execution risk around retenanting, e commerce pressure and higher leverage. Use this range as a prompt to explore contrasting views.
Explore another Mercialys fair value estimate, including one that suggests it could be worth just €13.78.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Mercialys research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Mercialys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mercialys' overall financial health at a glance.
Looking for more investment ideas beyond Mercialys?
Once you have formed a view on Mercialys, it can help to compare it with other listed businesses that share similar qualities or solve different portfolio needs.
- For readers hunting for mispriced opportunities with strong fundamentals, start with our carefully filtered 190 high quality undervalued stocks that might warrant a place on your watchlist.
- If you prefer income reliability over headline growth stories, check out a focused set of higher yield candidates in the 158 dividend fortresses to see which ones deserve deeper research.
- For capital preservation and steadier profiles, use our risk focused 224 resilient stocks with low risk scores to spot companies that may better fit a defensive allocation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com