


Trigano (ENXTPA:TRI) Could Be 43% Undervalued On Sales And Dividend News
Trigano (ENXTPA:TRI) has just combined fresh unaudited sales figures with a higher cash payout. The business reported €858.4 million in fourth quarter sales and confirmed a second interim dividend of €2.40 per share.
Despite the upbeat sales update and higher payout, Trigano’s shares have come under pressure, with the 1 month share price return down 19.14% and the year to date share price return down 27.67%, even though the 3 year total shareholder return is still positive at 6.99%.
Compare Trigano’s setback with other companies that have seen recent selling pressure but still screen well on fundamentals in our curated list of 190 high quality undervalued stocks.
Bulls see Trigano’s recent sales and dividend news as a mismatch with the falling share price. Bears see a value trap taking shape. Which side do the current valuation markers support?
Price-to-Earnings of 9.5x: Is it justified?
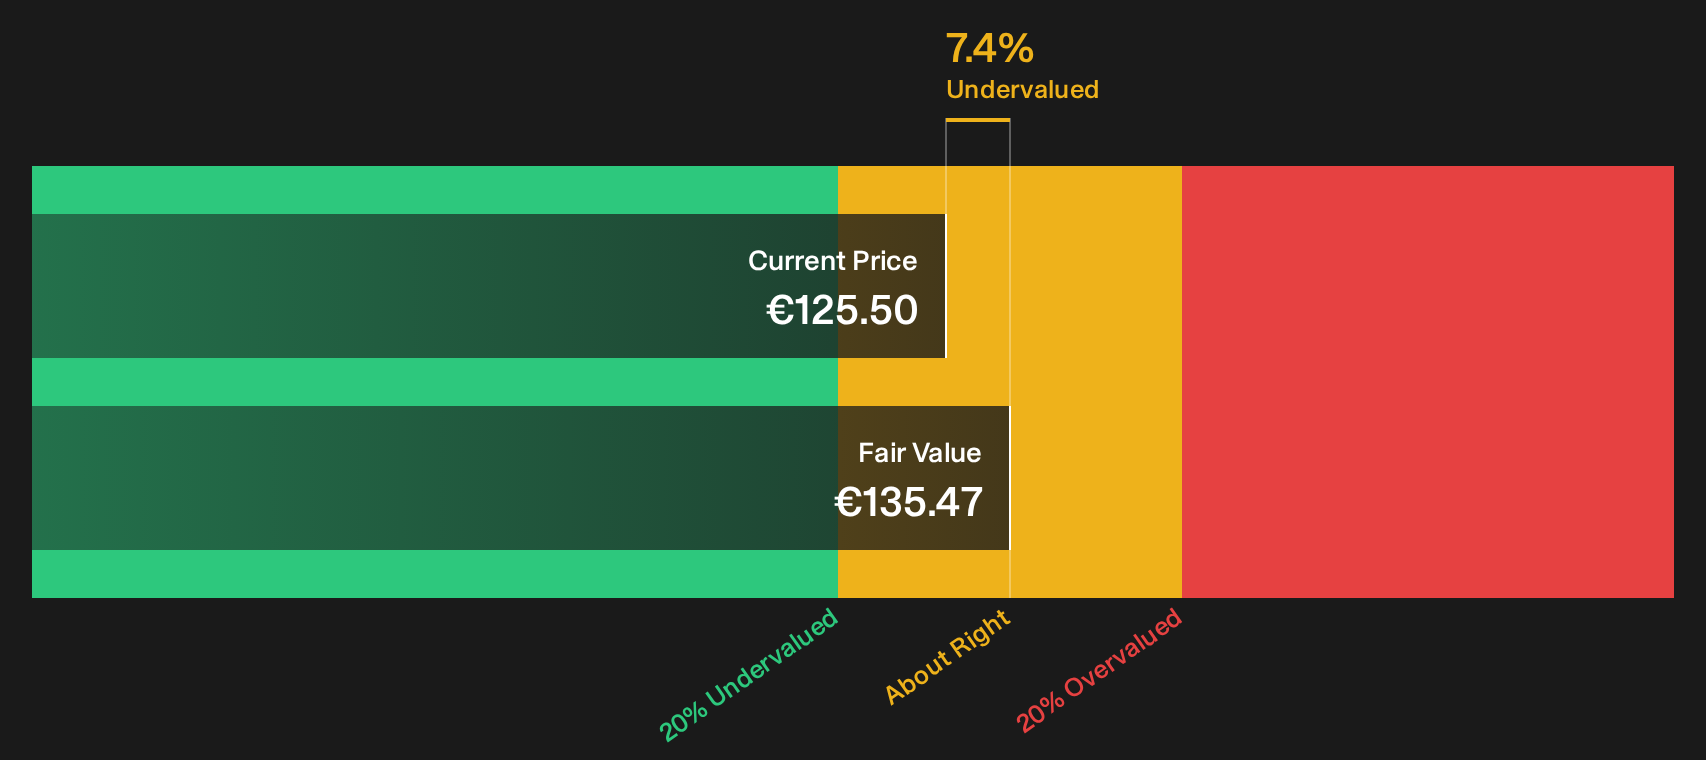
Trigano now trades on a P/E of 9.5x at a last close of €125.5, while analysts see a higher price target of €179.88 and the stock is described as trading 7.4% below an estimate of fair value.
The P/E ratio compares the current share price to earnings per share. It reflects what investors are paying today for each euro of profit. For a leisure vehicle manufacturer with €3,764.7m of revenue and €254.9m of net income, that multiple frames how the market is weighing recent earnings pressure alongside a longer history of profit growth.
On one hand, Trigano is labelled good value versus the broader Global Auto industry, where the average P/E sits at 13.5x. On the other hand, the same 9.5x is described as slightly expensive relative to a direct peer average of 9.3x and above an estimated fair P/E of 8.7x. This suggests the ratio could compress if sentiment cools.
Within that context, the shares are also flagged as trading below an internal future cash flow value of €135.47 and at a 43.3% discount to the analyst price target, which points to a wide gap between current pricing and what external models and coverage imply.
Explore the SWS fair ratio for Trigano.
Result: Price-to-Earnings of 9.5x (ABOUT RIGHT)
Still, Trigano’s exposure to discretionary leisure spending, along with its concentration in motorhomes and caravans, could quickly pressure earnings if consumer demand or regional budgets weaken.
Find out about the key risks to this Trigano narrative.
Another View on Trigano’s Value
The P/E of 9.5x paints Trigano as roughly fairly priced on earnings, yet our DCF model points to a different angle. On that cash flow view, the shares sit below an internal future value estimate of €135.47. Is this a pricing gap that closes, or a warning that the cash assumptions are too generous?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Trigano for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or emerging opportunity? If the debate around Trigano leaves you undecided, move quickly, review the upside markers yourself, then weigh the 4 key rewards.
Looking for more investment ideas beyond Trigano?
Do not stop at one ticker. Broaden your watchlist with other opportunities that share solid fundamentals, clearer income potential, or a different balance of risk and reward.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (207 results) that already pass strict financial health checks.
- Hunt for mispriced quality by reviewing the 617 high quality undiscovered gems that pair strong metrics with limited market attention.
- Build a cushion of income potential by examining the 158 dividend fortresses that combine higher yields with sturdier business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com