


Siemens (XTRA:SIE) Gains Attention Following Amtrak Airo Launch, Is It A Bargain?
Siemens (XTRA:SIE) is back in the spotlight after Amtrak’s new Airo fleet entered passenger service in the Pacific Northwest, tying real-world rail deployment to the group’s largest North American contract.
Siemens has seen short term momentum cool, with the share price declining over the past month and quarter. At the same time, the year to date share price return of 12.77% and 1 year total shareholder return of 15.11% sit alongside a very large 3 year total shareholder return of about 12x and a strong 5 year total shareholder return of 124.56%.
Scan how Siemens compares with other industrial and automation plays by reviewing hand picked 90 AI infrastructure stocks that are tied into AI, smart grids, and critical hardware.
Bulls point to Siemens’ rail and automation wins, while bears focus on the recent share pullback and past gains already on the table. Which story does the current valuation actually support next?
Most Popular Narrative: 9.8% Undervalued
On the most followed narrative, Siemens screens below its estimated fair value of about €301.57 compared with the last close at €271.90. This focuses attention on the company’s digital, grid, and automation engines that are meant to support that gap.
The large, resilient order backlog (€117 billion) and continued strong book to bill ratios in core areas such as Mobility and Smart Infrastructure position the company for robust multi year revenue visibility and support higher consolidated earnings.
See why 175 investors see Siemens as 10% undervalued.
Result: Fair Value of €301.57 (UNDERVALUED)
Still, the bullish Siemens narrative can unravel if weak automation demand or tougher global competition in industrial software affects orders and profitability.
Find out about the key risks to this Siemens narrative.
Another View On Siemens Valuation
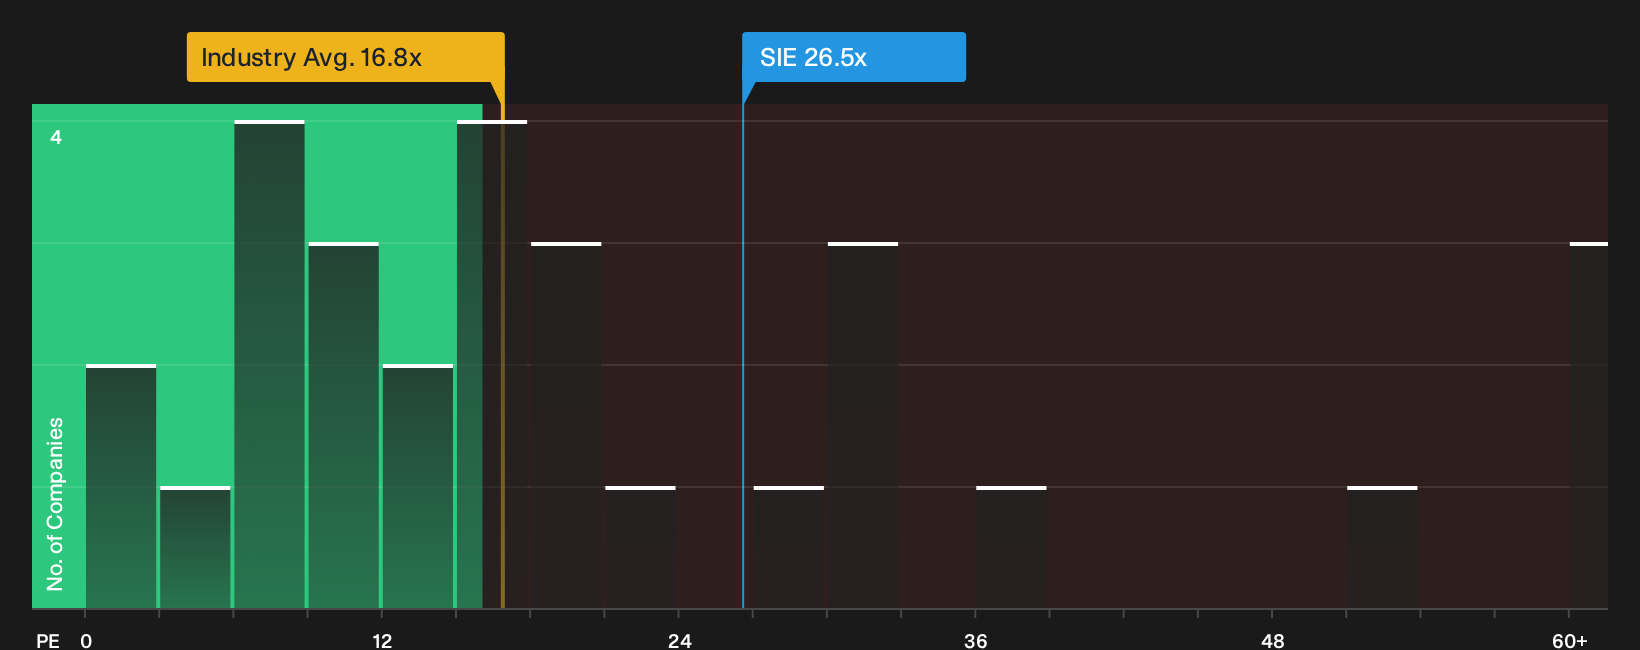
The earlier narrative framed Siemens as about 9.8% undervalued relative to a €301.57 fair value. On a simple earnings multiple, the picture looks less generous. The stock trades on a P/E of 26.5x, which is higher than the European Industrials group at 16.8x, yet very close to peers at 26.7x.
Against the estimated fair ratio of 30.4x, that premium to the wider sector could still imply room for the market to move closer to the higher benchmark over time. For you as an investor, the question is whether that gap represents extra upside or simply extra valuation risk compared with cheaper industrials.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Siemens valuation and sentiment can be useful, but the real edge comes when you test the numbers yourself and move fast to decide whether this story fits your portfolio. Start with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Siemens?
If you have built a view on Siemens, the next edge often comes from comparing it with a few sharply defined investment shortlists.
Use the Simply Wall Street Screener now so you do not miss fresh opportunities lining up with your risk profile, income needs, and growth focus.
- Target resilient potential by reviewing a curated set of 224 resilient stocks with low risk scores that aim to keep volatility in check while still participating in market moves.
- Hunt for quality at a discount by scanning a focused pool of 190 high quality undervalued stocks that combine fundamentals with pricing that may not fully reflect them yet.
- Secure your cash flow goals by assessing a hand picked group of 157 dividend fortresses that concentrate on higher yields and more established payout histories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com