


Is North Atlantic Energies (ENXTPA:NAE) Below Fair Value After Narrower Half Year Losses?
What the latest earnings mean for North Atlantic Energies
North Atlantic Energies (ENXTPA:NAE) has just posted half year results to June 30, 2026, with sales and revenue slightly higher and the net loss narrowing to €30.3 million.
Loss per share from continuing operations also improved, moving to €2.36 on both a basic and diluted basis, compared with a much deeper deficit a year earlier that had weighed heavily on the company.
North Atlantic Energies’ latest earnings land after a sharp pullback, with a 7 day share price return of down 17.17% and a 30 day move of down 6.33%. This comes even though the 90 day share price return of 64.20% and 1 year total shareholder return of 114.38% indicate strong longer term momentum that has radically outpaced the short term weakness.
Scan beyond North Atlantic Energies and evaluate hand-picked peers with similar turnaround potential using our 616 high quality undiscovered gems.
After a sharp rally over the past year and a recent pullback, North Atlantic Energies now screens at a steep intrinsic discount of about 91%. Is that genuine mispricing, or is the market correctly pricing ongoing losses?
Preferred Price-to-Sales of 0.1x for North Atlantic Energies: Is it justified?
On the numbers, North Atlantic Energies trades on a P/S of roughly 0.1x, which is far lower than both peers and the wider European oil and gas group. The share price closed at €84.4.
The P/S ratio compares the market value of the equity with the revenue the business generates, so it tells you how much investors are currently willing to pay for each euro of sales. For a refiner and fuel retailer like North Atlantic Energies, where earnings are currently negative, this kind of top line yardstick often becomes one of the cleaner reference points for valuation.
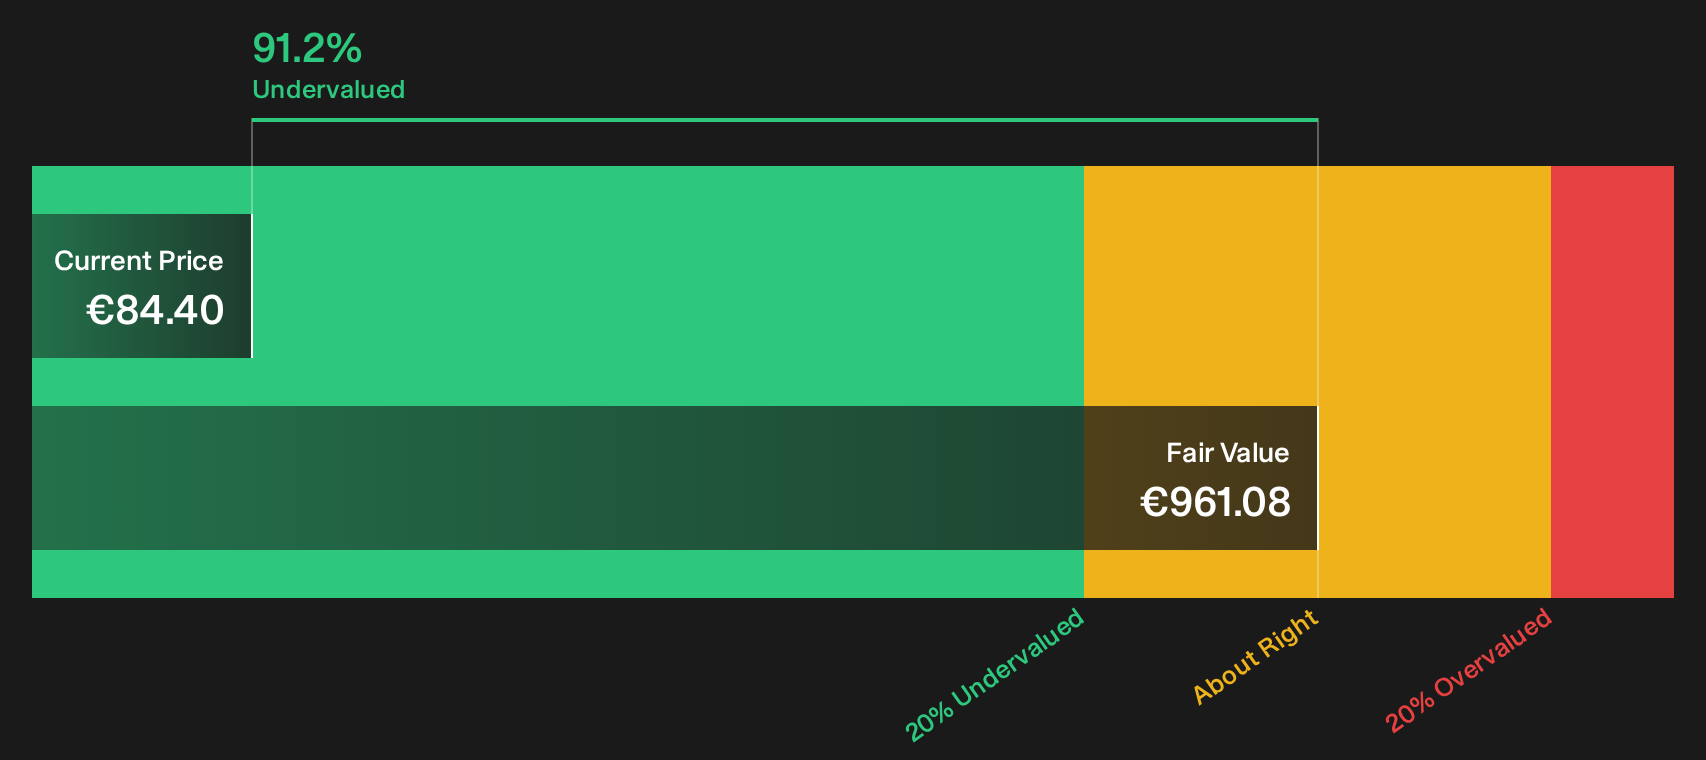
Here, the gap is wide. The stock is described as trading at 91.2% below an internal fair value estimate, and its 0.1x P/S is flagged as good value compared both with a 3.8x peer average and a 1.8x European oil and gas benchmark. That combination suggests the market is heavily discounting ongoing losses, balance sheet pressure and the dividend coverage issues instead of paying up for current sales. Whether that is justified depends on how investors weigh those risks against the potential for a turnaround.
Relative to the industry, the discount is stark. A P/S of 0.1x versus 1.8x for the broader European oil and gas group points to investors valuing each euro of revenue at only a small fraction of what similar businesses trade at. This implies sentiment is materially weaker around North Atlantic Energies despite the long term share price gains already on the board.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Sales of 0.1x (UNDERVALUED)
Still, the ongoing net loss of €38.4 million and the fact that North Atlantic Energies is a subsidiary of North Atlantic France SAS could limit flexibility if conditions worsen.
Find out about the key risks to this North Atlantic Energies narrative.
Another view on North Atlantic Energies’ valuation
The SWS DCF model presents a very different picture for North Atlantic Energies. On this framework, the stock at €84.4 is compared with an estimated future cash flow value of €961.08, which indicates a very steep implied undervaluation.
This kind of gap can reflect deep scepticism about long term cash generation, balance sheet strain and the fact that losses have widened over the past 5 years. It raises a simple question for investors: is the market correctly bracing for more pain, or is sentiment overshooting the underlying cash flow potential?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out North Atlantic Energies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around North Atlantic Energies can feel confusing, so move fast, pull up the data, and pressure test the story against your own thesis using the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond North Atlantic Energies?
If you stop with North Atlantic Energies, you only see one angle. Push a little further and you give yourself more options when markets move.
- Target potential mispricing by scanning a curated pool of companies that combine low valuations with solid fundamentals using the 189 high quality undervalued stocks.
- Prioritise resilience by reviewing a focused universe of businesses with stronger balance sheets and cleaner finances through the list of solid balance sheet and fundamentals (207 results).
- Hunt for under-the-radar opportunities by checking a filtered set of lesser known stocks with quality metrics via the 616 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com