


3 Canadian Value Stocks To Watch In October 2026
Global bond markets have been hit hard this month, with borrowing costs in major economies pushing to multi decade highs. When yields rise like this, investors often punish companies that look sensitive to higher interest costs and overlook those with solid cash generation. That creates a window in Canadian equities. This piece highlights three cash rich Canadian stocks our cash flow undervaluation screen flags as trading below estimated fair value.
The three examples below are only a sample. The full cash flow screen highlights 1 more Canadian company with a similar mismatch between DCF value and share price that is not covered here. To see the complete picture, analyze and filter potential opportunities directly in the Undervalued Stocks Based On Cash Flows screener.
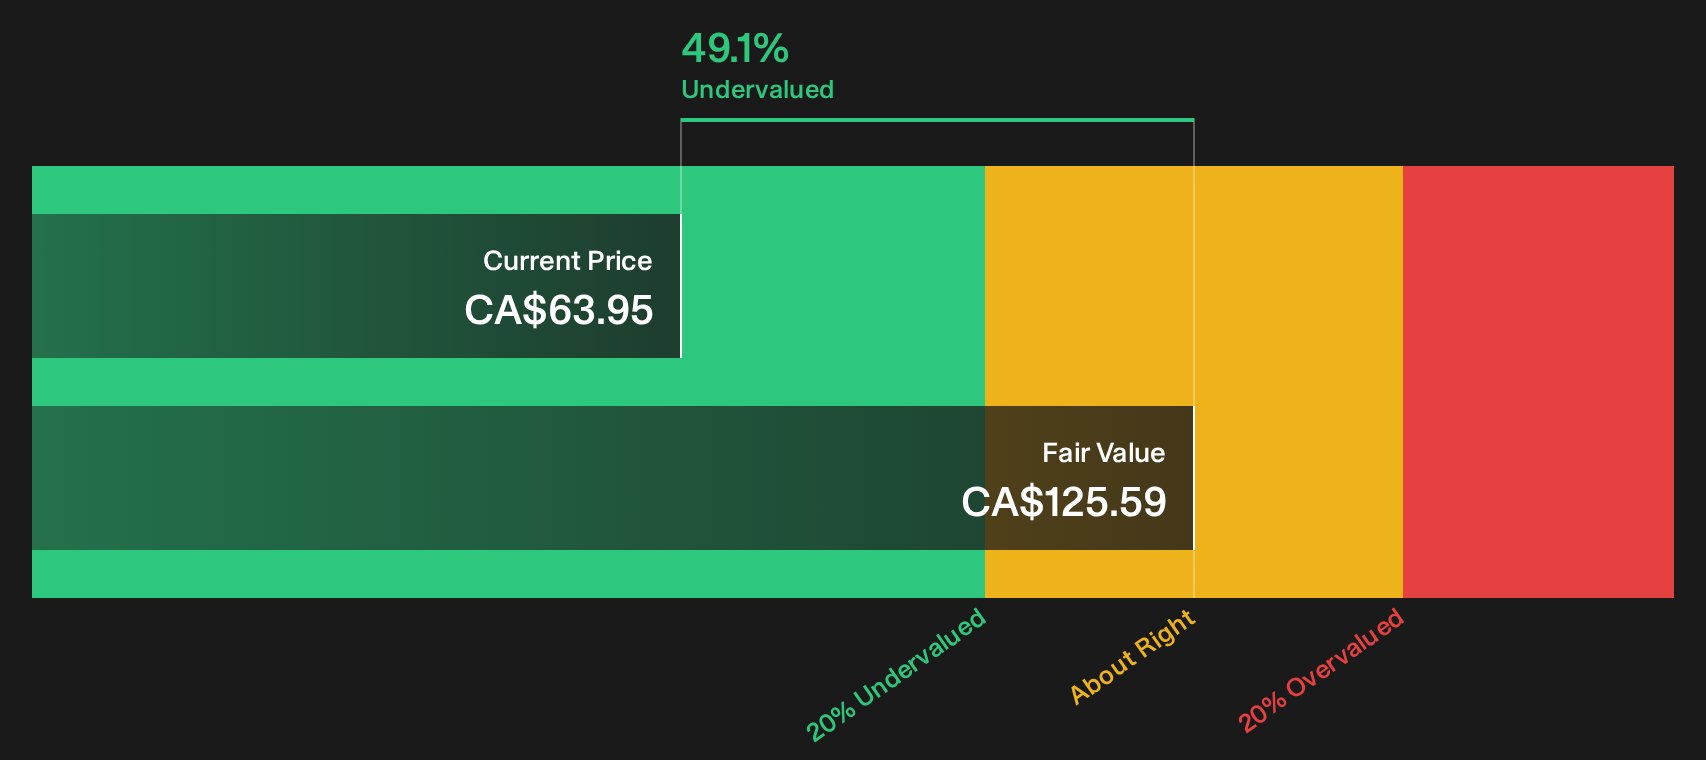
Pan American Silver (TSX:PAAS)
Pan American Silver is a precious metals producer whose cash flow story is anchored in operating silver and gold mines across the Americas, with major revenue coming from Brazil’s Jacobina mine at about US$762 million and Chile’s El Peñon at roughly US$693 million, and the business currently valued near CA$27 billion by the market.
For value focused investors, Pan American Silver matters because its producing mines are already generating operating cash that can be used in DCF models, and management is working on projects that aim to deepen that cash flow pool over time.
"Integration of Juanicipio, with its low cash costs and contribution to attributable silver production and income, refines the cost base and can support higher segment margins and free cash flow generation."
The key question is whether one planned shift in the operating mix will quietly tilt future margins and cash generation in your favour.
If that shift in mix is what really moves the needle for you, read the full narrative for Pan American Silver to see how Pan American Silver’s risk and cash story could be decoupling.
Suncor Energy (TSX:SU)
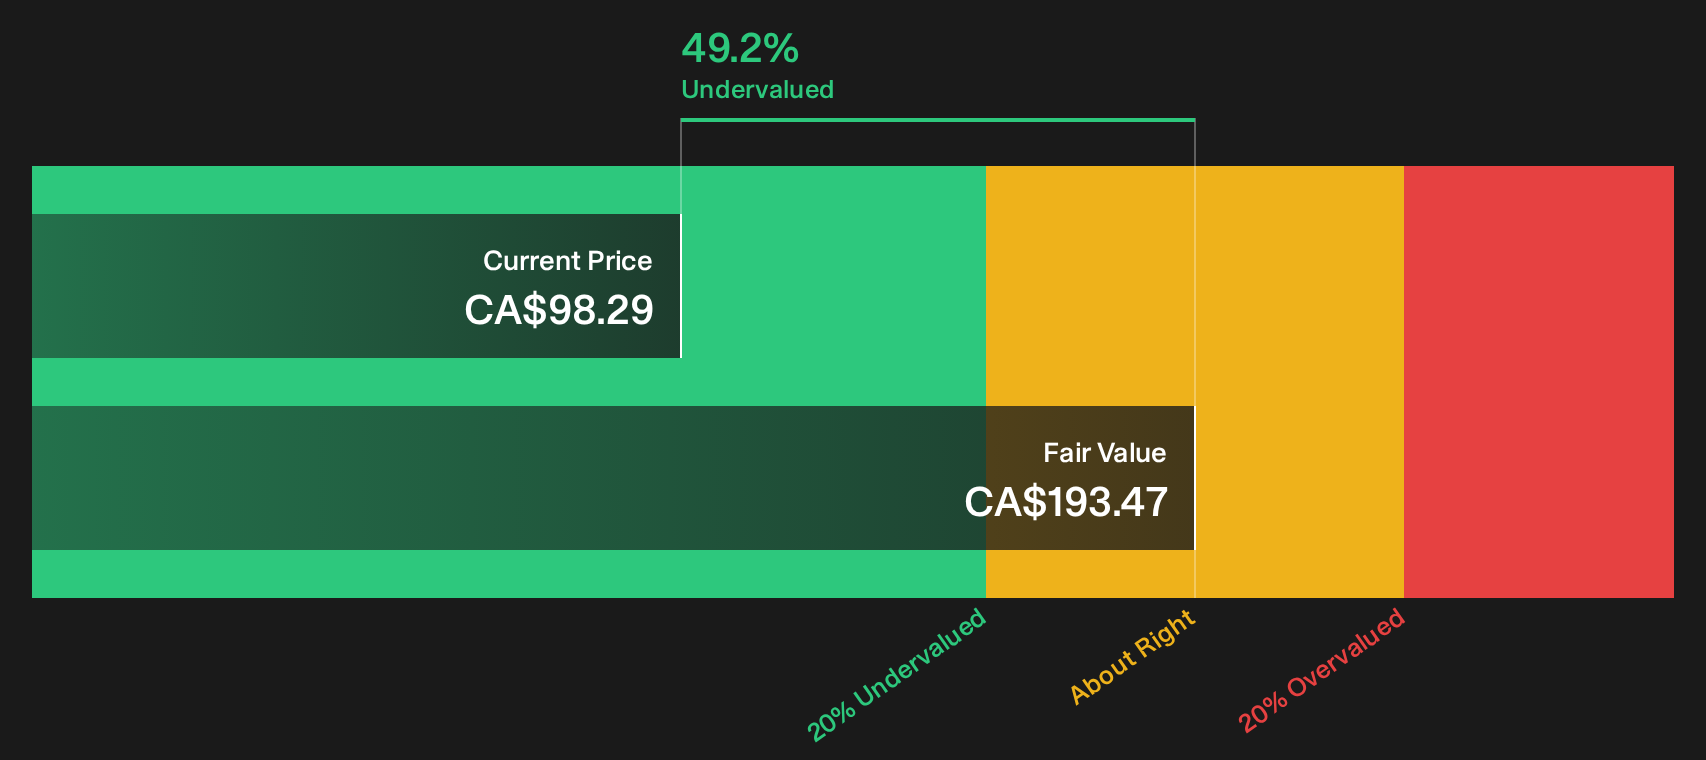
Suncor Energy is an integrated producer and refiner where long lived oil sands cash flows anchor the cash flow undervaluation story, while Refining and Marketing adds a second income stream. The group generated about CA$26.9b from Oil Sands, CA$36.8b from Refining and Marketing and CA$2.5b from Exploration and Production, and is valued around CA$112.9b by the market.
Suncor Energy combines long life oil sands production with refining cash generation in a way that fits neatly with a cash flow focused screen. At the same time, it raises the question of how intensively its physical assets can be run before reliability starts to affect that narrative.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels."
The key issue for Suncor Energy is what happens to margins and cash returns if the underlying assumption about operating intensity does not hold.
If that risk of strain on the asset base is what you are weighing, read the full narrative for Suncor Energy to see how Suncor Energy’s cash engine could still accelerate.
Canadian Natural Resources (TSX:CNQ)
Canadian Natural Resources is a large Calgary based producer of crude oil, natural gas, and NGLs whose upstream operations across Western Canada, the U.K. North Sea, and Offshore Africa are central to the screener’s focus on cash flow driven value.
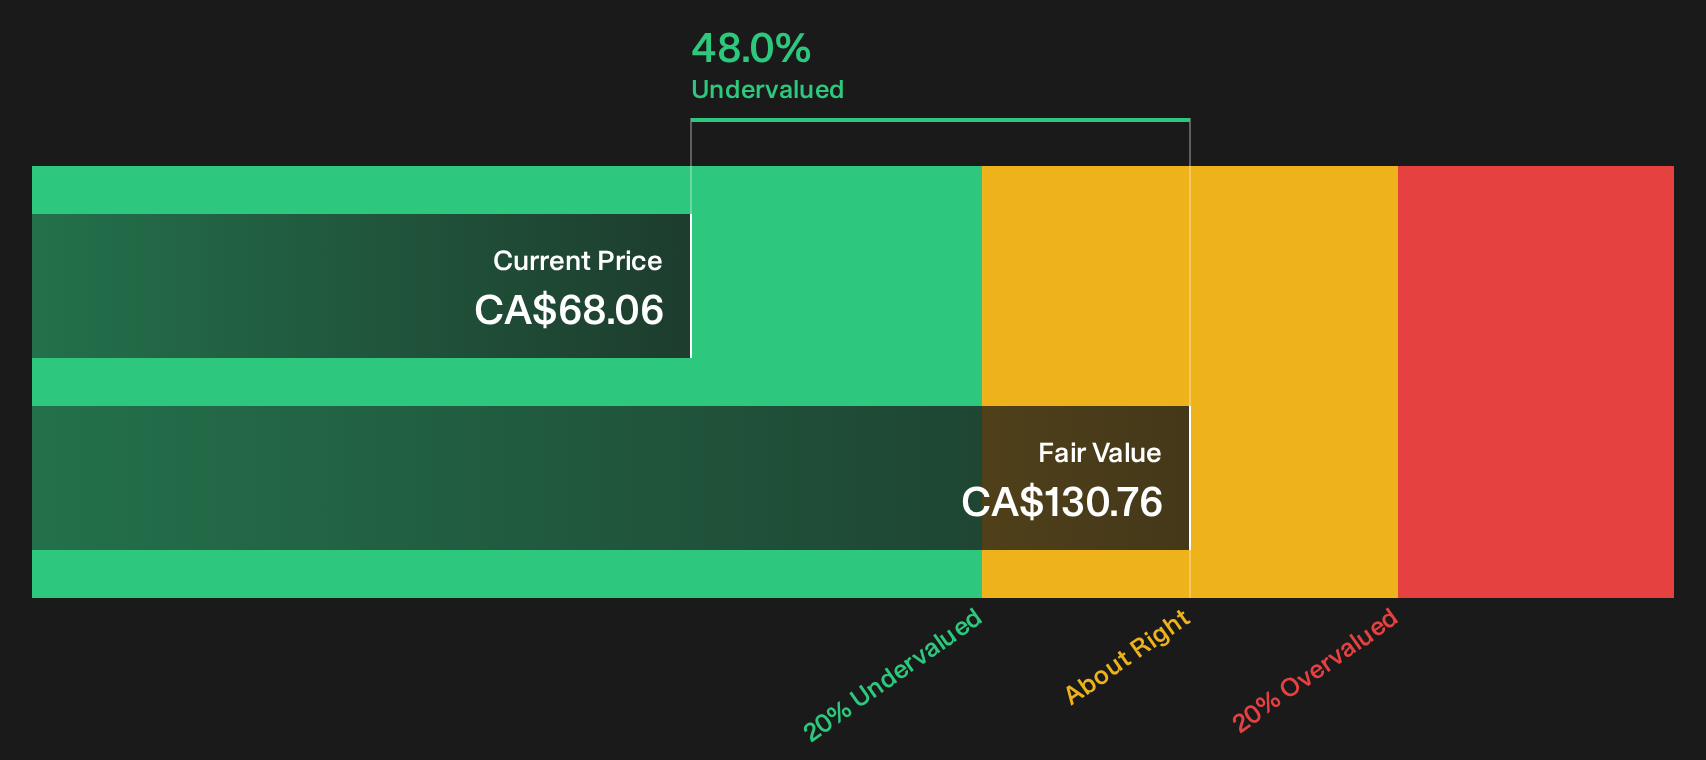
The business generates most of its income from Oil Sands Mining and Upgrading at about CA$20.8b and Exploration and Production in North America at roughly CA$21.3b, with smaller contributions from midstream and other segments, and the company is valued near CA$138.0b by the market.
For investors zeroing in on cash flow, Canadian Natural Resources ties the theme together through long life production assets that feed discounted cash flow models and help explain why valuation can drift away from those underlying streams.
"Recent accretive acquisitions have expanded production and reserves with minimal increase to the 2025 capital budget. This positions Canadian Natural for immediate cash flow growth and increased future revenues as these assets are developed."
The real swing factor is what happens to those cash returns if one pressure on future margins moves in a less friendly direction.
If that margin pressure is what you are weighing, read the full narrative for Canadian Natural Resources to see whether Canadian Natural Resources’ cash engine is quietly accelerating beneath the surface.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Once momentum hits, entry points can fly away as prices react and narratives get caught up. Scan under the radar for now, act now.
- Jump on income streams that can support portfolios when growth cools by tracking potential high yield candidates in the 1 dividend fortresses before others chase the payouts.
- Spot early movers in automation and logistics by scanning the curated 90 robotics and automation stocks while adoption stories are still forming and sentiment has not fully caught up.
- Target growth stories building capacity for future computing demand by reviewing the focused 90 AI infrastructure stocks before capital flows push valuations to tighter ranges.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com