


Is Roche Holding (SWX:ROP) Cheap, Or Are New Drug Wins Priced In?
Roche Holding has delivered a strong multi year share price performance, and with fresh drug data and partnerships in the headlines, the real puzzle for investors is whether that climb is backed up by the earnings the business is generating today.
- Over the past 3 years the stock has gained 56.9%, which puts real pressure on the question of whether the current valuation is still grounded in its profit power.
- Recent clinical milestones in multiple sclerosis, kidney disease and oncology, alongside sizeable research partnerships, can shape expectations for Roche Holding's future earnings stream and the timing of cash flows that matter for valuation.
- Your read on Roche Holding is one view; the desks covering it have another. See what analysts think Roche Holding's shares could be worth.
The stock's next move may depend on whether Roche Holding's current price can be explained by the earnings that underpin it right now.
To see how Roche Holding's recent drug news and 3 year gain of 56.9% compares with other opportunities in healthcare and beyond, line it up against companies in the 189 high quality undervalued stocks
Is Roche Holding Still Cheap on Earnings?
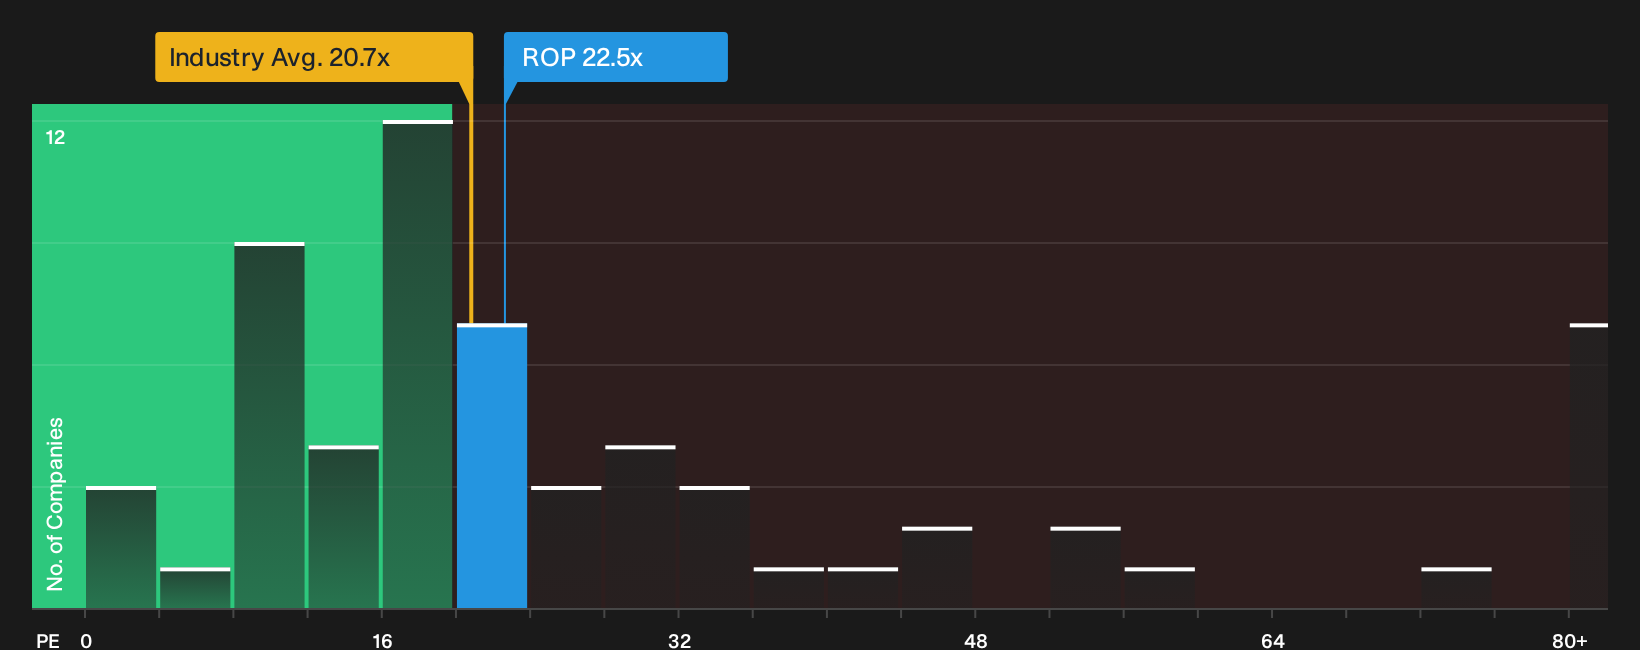
The P/E ratio works well for Roche Holding because earnings remain a central anchor for how investors frame the drug pipeline and new product launches. On this measure, the stock trades on a P/E of 22.5x, which is close to the Pharmaceuticals sector average of 21.9x and well below a peer group average of 40.6x.
Recent FDA priority review status for fenebrutinib has kept attention on Roche Holding's pipeline. However, the current earnings multiple still sits below what a tailored fair P/E model would imply for a business with its profile. That model blends factors such as profitability, risk and size, so a lower live multiple points to the shares being undervalued on this framework. For anyone tracking big pharma valuations, the gap versus peers and the modelled fair level makes this P/E worth a closer look. Explore the numbers behind Roche Holding's P/E valuation.
The Roche Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Roche Holding's valuation puzzle leaves off and explain which future paths for earnings, margins and growth would need to occur for the stock to be worth materially more or less than today. Instead of a single output from a ratio or model, these narratives unpack the future that figure is built on so you can track how Roche Holding's actual progress compares on the Community page.
Community views on Roche Holding are split between those who see the current setup as roughly fair and those who think expectations have crept too high.
Bull case: roughly fairly valued
"Roche represents a high-quality, lower-risk pharma investment relative to biotech, supported by strong cash flows, market leadership in oncology, and a deep pipeline…"
Discover why this Narrative puts Roche Holding at roughly fairly valued.
Bear case: 30% overvalued
"The sheer volume of late stage programs raises execution risk on timelines, regulatory decisions and commercial uptake, which could limit how far this pipeline translates into higher group revenue and earnings…"
Explore why this Narrative puts Roche Holding at 30% overvalued.
One more open question for Roche Holding
Roche Holding’s current share price tells one story, but brokerage models looking a few years out offer a different lens on where profits and cash flows might land, and how that lines up with today’s multiple. Explore where analysts expect Roche Holding to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com